Return Adjustment Framework
Institutional investors often receive preliminary or updated return data directly from fund managers before the same figures appear in vendor databases. Risk Shell's Return Adjustment Framework allows multiple return series to be maintained for the same fund, so manager-supplied data can be used without overwriting the original vendor history.
- Create cloned database assets with independently maintained performance data
- Switch instantly between vendor-reported and adjusted user-defined return series
- Maintain a secondary performance series based on data received directly from fund managers
- Correct provisional returns, reporting delays and inconsistencies in vendor data while preserving the original series
Custom Descriptive Fields
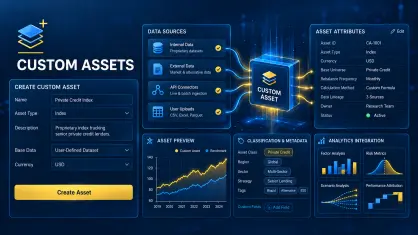
Risk Shell Custom Assets allows users to create proprietary descriptive fields and use them alongside descriptive data supplied by external data vendors. These fields become part of the asset record and can be used throughout Risk Shell for screening, filtering and research.
- Custom field types: text, date and predefined dropdown lists
- Multiple dated records can be maintained for the same field
- Custom fields are available across all supported databases
- Fields can be used together with standard Risk Shell screening and search criteria