Alternative Investment Management Software

Risk Shell

Institutional portfolio management, risk analytics and portfolio construction for alternative and multi-asset portfolios.

Integrated investment data, stress testing, portfolio optimization, alternative investment analytics and shadow accounting within one platform.

FoF Manager hero
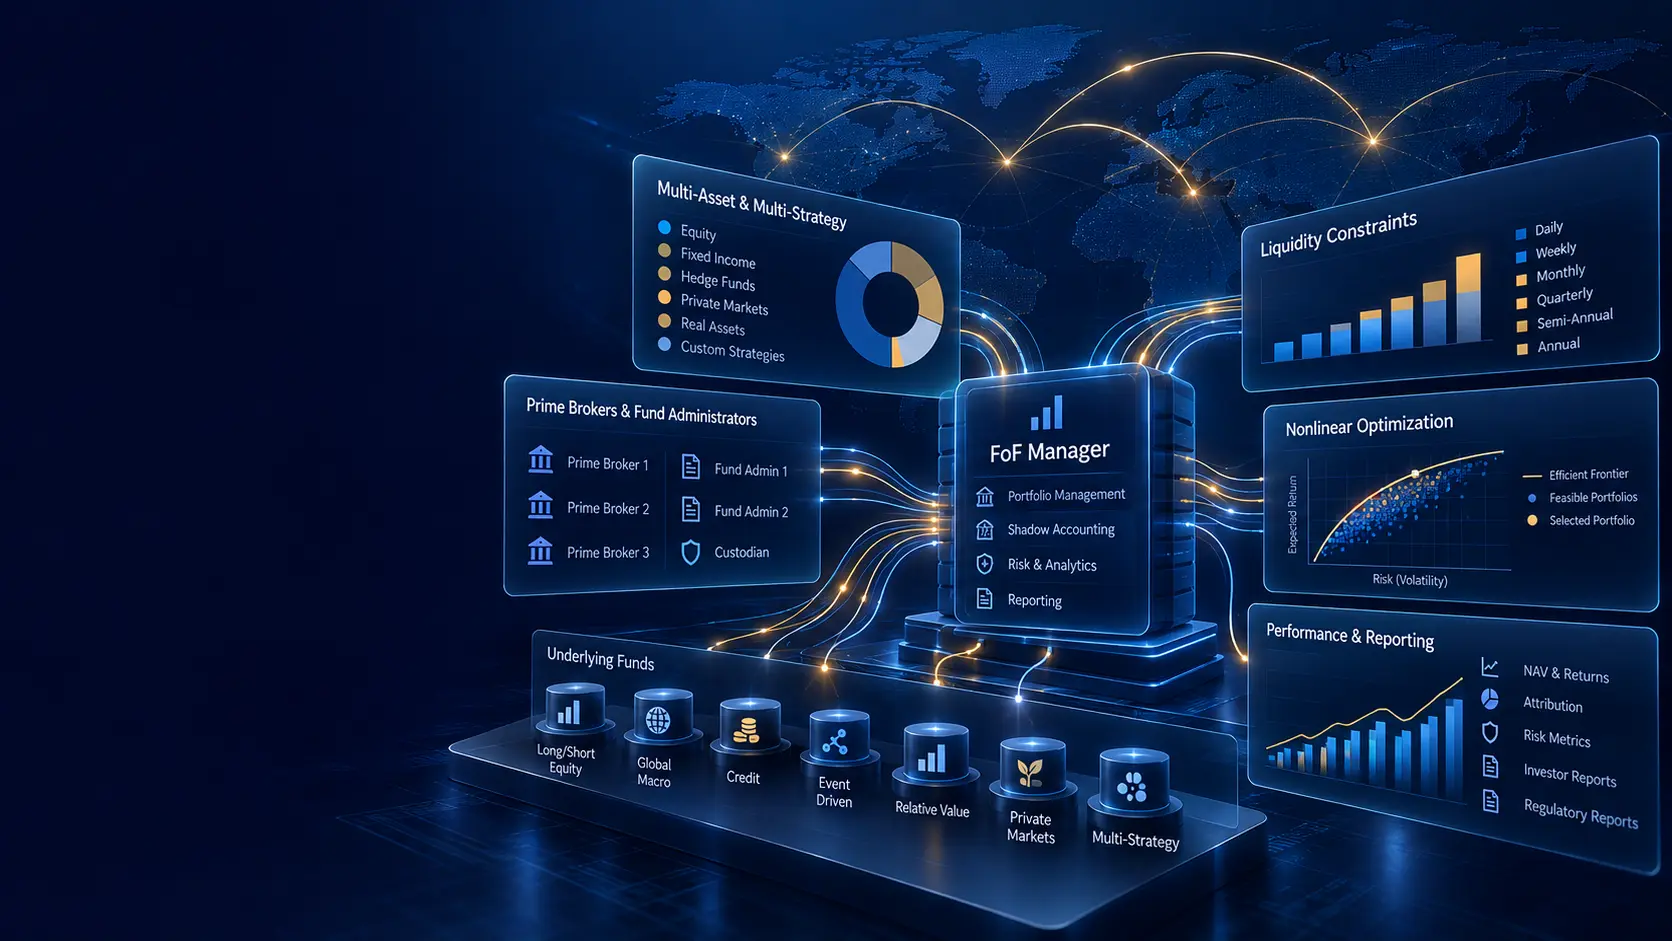
FoF Manager

Shadow Accounting for Alternative Portfolios

Manage hedge funds, private equity and multi-asset portfolios with liquidity controls, custom classifications and flexible historical accounting.

35+ hedge fund liquidity settings
Explore FoF Manager
Optimization hero
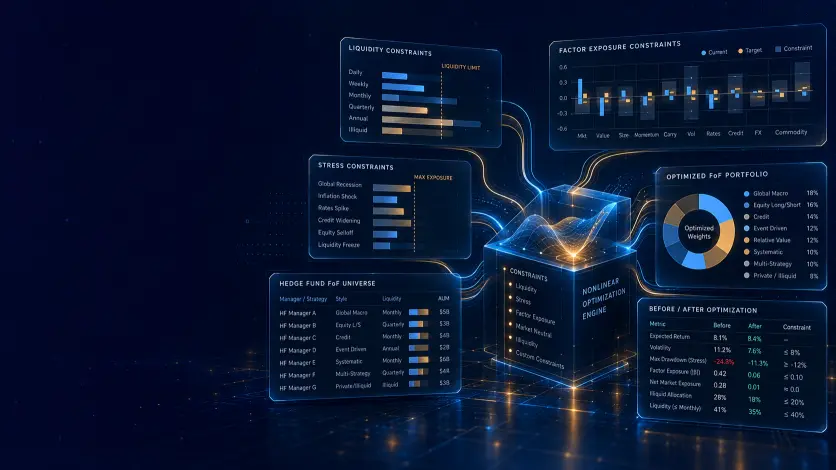
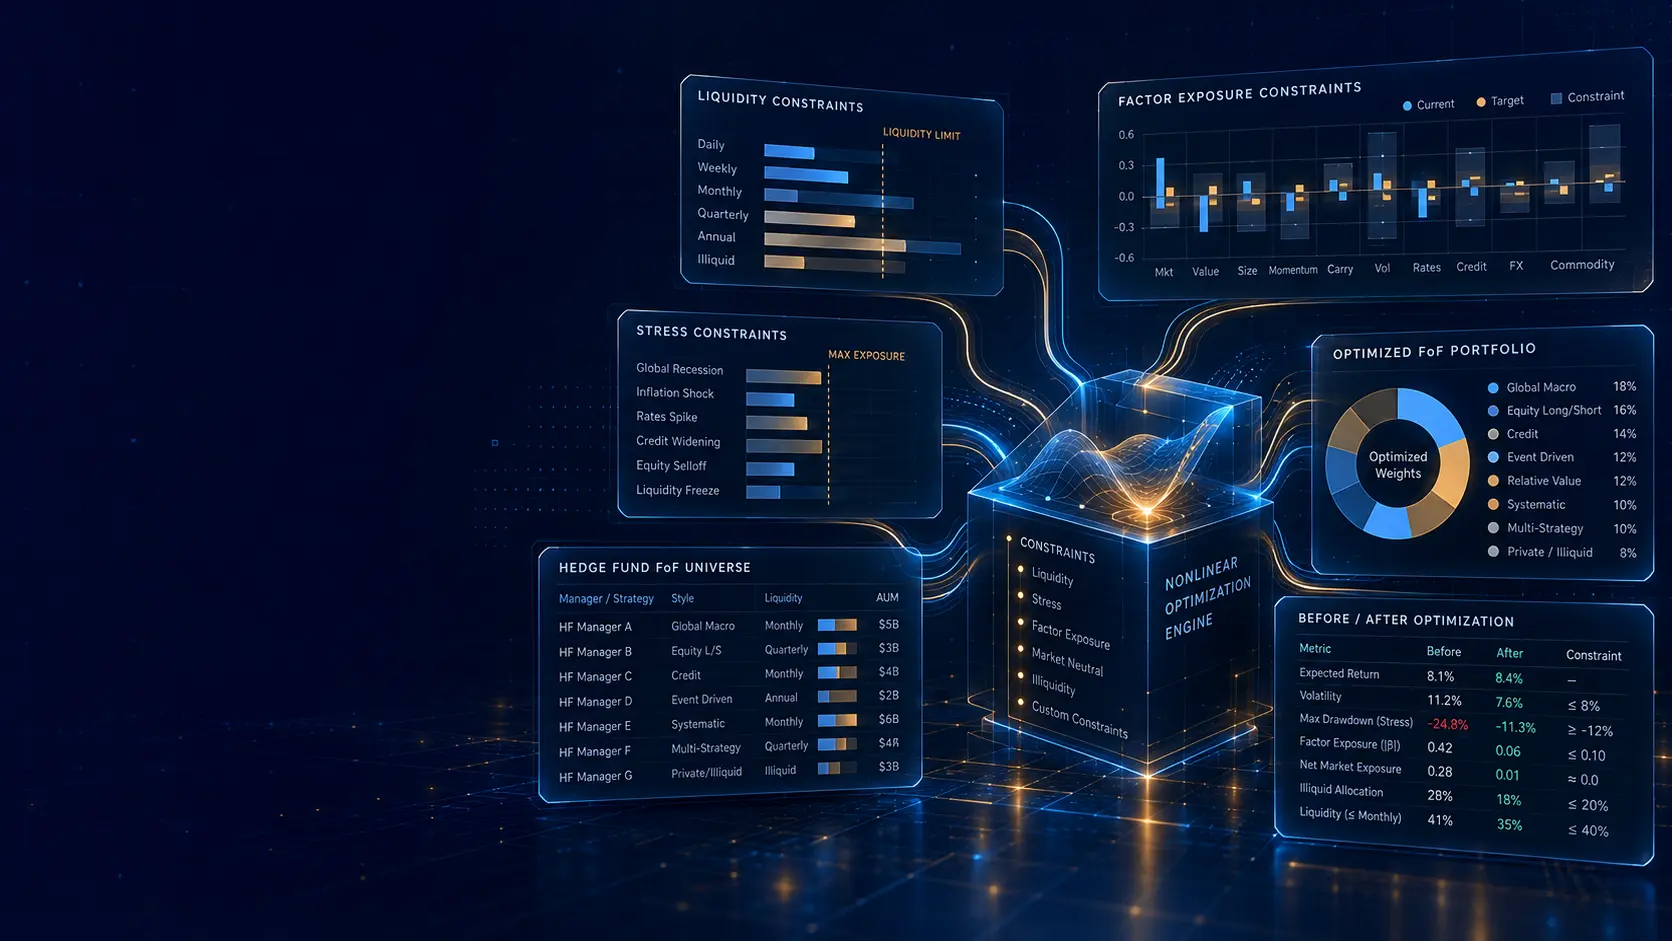
Portfolio Optimization

Nonlinear Portfolio Optimization

Construct hedge fund-of-funds and multi-asset portfolios with stress-test, factor-exposure, liquidity and other user-defined constraints.

Custom Constraints for market-neutral and risk-controlled portfolio construction
Explore Portfolio Optimization
Risk Shell AI hero
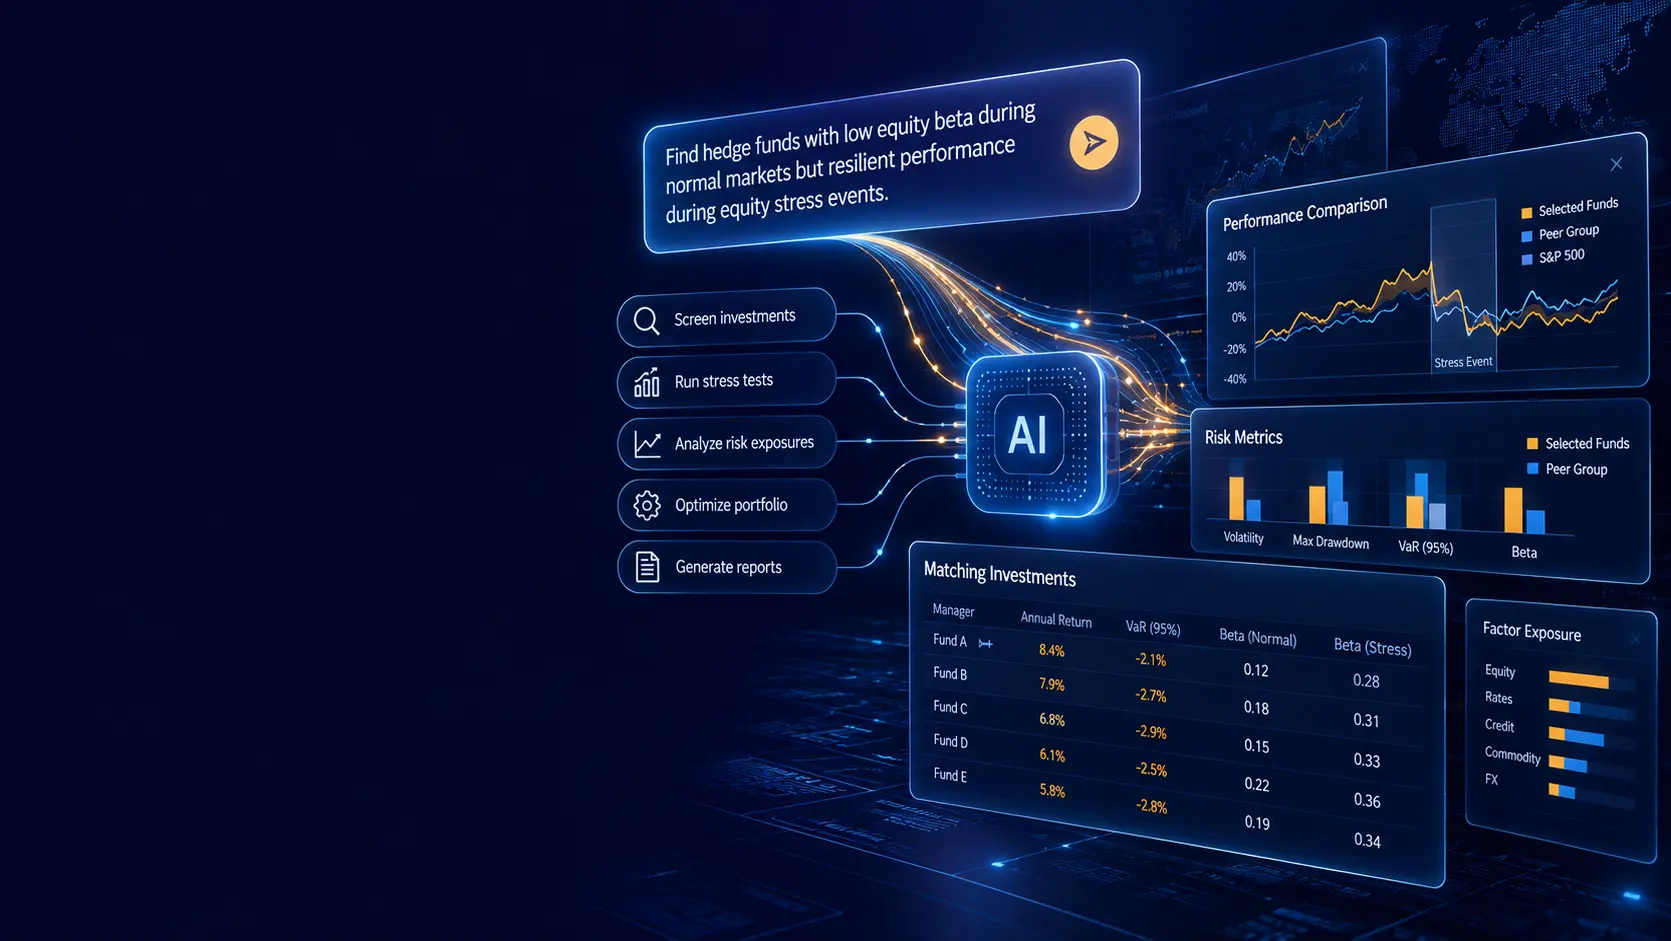
Risk Shell AI

Natural-Language Access to Risk Shell

Use natural language to access investment research, risk analytics and portfolio workflows.

2.3B tokens in our in-house financial LLM
Explore Risk Shell AI
Macroeconomic Scenario Screening hero
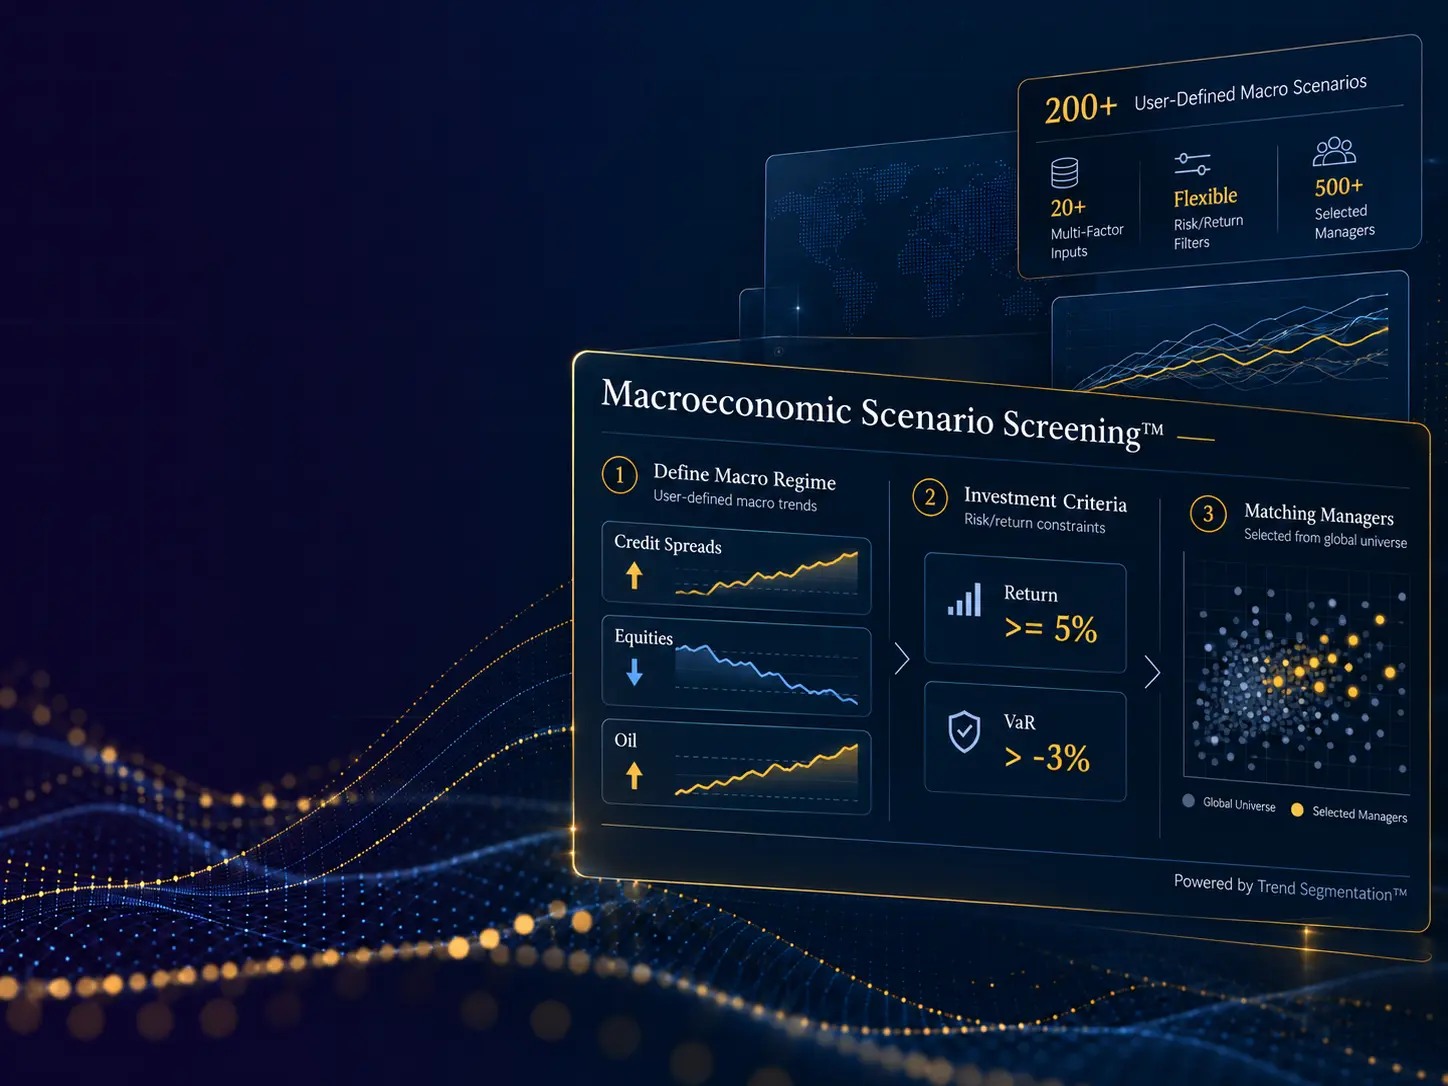
Macroeconomic Scenario Screening

Select Assets for the Scenario You Define

Screen managers by risk and return targets under user-defined macroeconomic scenarios.

Trend Segmentation™ proprietary regime-analysis engine
Explore Scenario Screening
Peer-relative Stress Testing
Portfolio Stress Testing

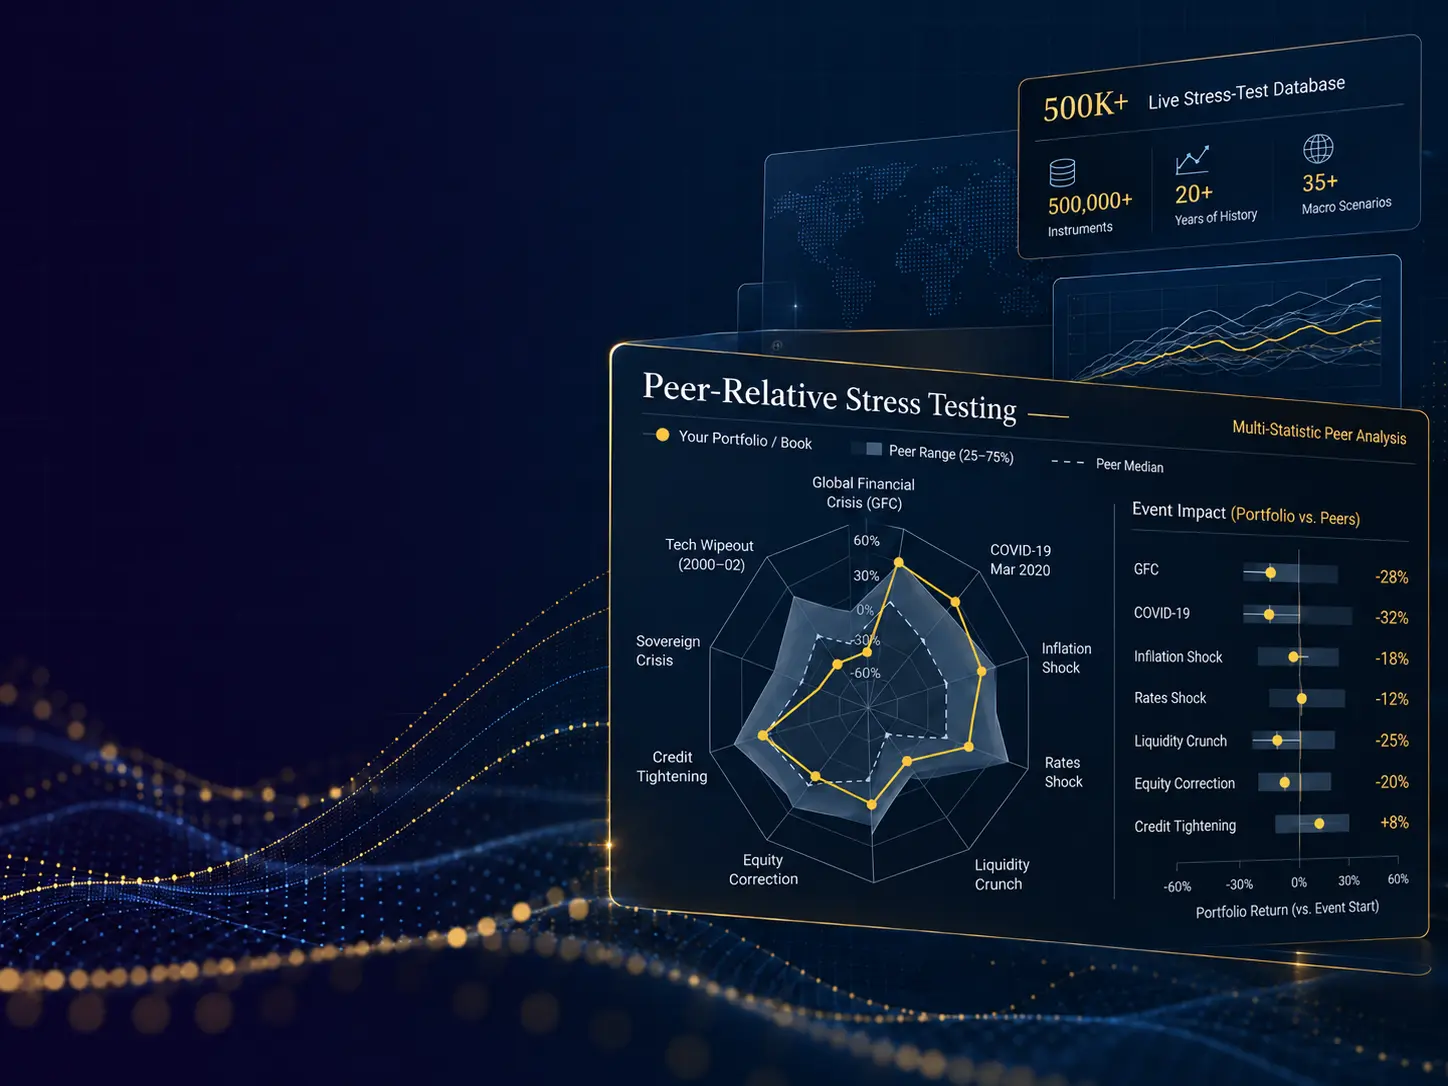
Peer-Relative Stress Testing

Compare extreme-event outcomes with a relevant peer group.

500K+ live stress-tested instruments
Explore stress testing

Risk Shell Training Programs

Risk Shell training is available at several levels, from introductory platform workflows to advanced risk analysis and portfolio construction. The chart provides a detailed comparison of the subject areas covered by each program.

Basic

Introduction to Risk Shell workflows, investment research tools and the core risk measures used throughout the platform.

Advanced

Extends the core workflow into factor analysis, stress testing, manager assessment and more advanced portfolio risk analysis.

Expert

Advanced training in portfolio construction, risk budgeting, nonlinear optimization and the statistical models implemented in Risk Shell.

Full Course

The complete predefined curriculum covering Risk Shell operation, risk analytics, factor models, portfolio construction and optimization.

Custom

A client-specific program assembled from selected Risk Shell components, analytical techniques and portfolio-management workflows.

Risk Shell Workflow Training

Risk Shell training covers the practical use of the platform across investment research, risk analysis and portfolio construction. Sessions follow complete analytical workflows rather than isolated software functions, showing how data selection, model settings and analytical outputs are connected within Risk Shell.

Research & Risk Analysis Workflows

Training covers the full cycle from asset or manager selection through comparative analysis, factor modelling and risk assessment.

  • Search, screening and manager-selection workflows
  • Wallets, peer groups and Side-by-Side Analysis
  • Factor and Style Analysis
  • Stress Testing and scenario analysis
  • Macroeconomic Scenario Screening™
  • Custom Assets and user-defined data
  • FlexiRank™ asset ranking

Portfolio Construction & Management Workflows

Portfolio training follows the complete process from portfolio setup and risk analysis to allocation changes, optimization and ongoing portfolio monitoring.

  • Portfolio What-If Analysis
  • Marginal risk contribution and diversification
  • Risk Budgeting
  • Portfolio Optimization and constraint setup
  • Constructing market-neutral portfolios
  • Optimization backtesting and rebalancing
  • FoF Manager workflows including shadow accounting and portfolio management

Investment Reporting

Training covers the reporting workflow in Risk Shell, from running standard analytical reports to designing industry-standard report templates for recurring manager, portfolio and risk reviews.

  • Creating custom report templates with Report Builder
  • Combining analytical tables, charts and portfolio outputs within a report
  • Running reports for selected funds, managers and portfolios
  • Using saved templates for recurring research and monitoring workflows

Advanced Risk & Portfolio Techniques

Effective use of Risk Shell requires an understanding of the statistical and portfolio models implemented in the platform. Users need to understand what a model measures, its assumptions and limitations, and when its output is appropriate for a particular asset, manager or portfolio.

Risk & Factor Models for Alternative Investments

Many techniques required for hedge funds, nonlinear return distributions and dynamic manager exposures receive only limited treatment in standard finance curricula and professional qualifications. Risk Shell training therefore covers the models used in the platform before they are applied in practice.

  • Tail-risk and downside-risk measures
  • Autocorrelation and non-normal return distributions
  • Static and Dynamic Factor Analysis
  • LASSO, PCA, AIC, Elastic-net, Ridge and Kalman-filter models
  • Trend Segmentation™
  • Stress Testing and Macroeconomic Scenario Screening™
  • Private equity valuation models including the Yale Cashflow Forecastin, Direct Alpha, Index IRR, and KSPME

Portfolio Construction & Optimization Techniques

Risk Shell portfolio models extend well beyond conventional mean-variance optimization. Training covers the techniques required to select an appropriate objective function, specify constraints and interpret optimization results for alternative and multi-asset portfolios.

  • Marginal risk contribution and diversification analysis
  • Risk Budgeting and Equal Risk Contribution
  • Nonlinear Portfolio Optimization
  • CVaR, drawdown and downside-risk objectives
  • Factor, stress-test and liquidity constraints
  • Optimization backtesting and rebalancing

Training Curriculum

Risk Measurement & Alternative Investments

  • Value-at-Risk and tail-risk measures
  • Drawdown and downside-risk analysis
  • Distribution characteristics of hedge fund returns
  • Autocorrelation and serial dependence
  • Peer-relative risk assessment
  • Risk measures used in manager screening

Factor & Style Analysis

  • Static and Dynamic Attribution Analysis
  • LASSO, PCA, AIC and Ridge factor models
  • Kalman-filter models
  • Factor selection and model diagnostics
  • Style drift and Trend Segmentation™
  • Macroeconomic Scenario Screening™

Portfolio Construction & Optimization

  • Portfolio construction workflow
  • Marginal risk contribution and diversification
  • Risk Budgeting and Equal Risk Contribution
  • Nonlinear Portfolio Optimization
  • Factor, stress-test and liquidity constraints
  • Optimization backtesting and rebalancing

FoF Manager & Portfolio Management

  • Portfolio exposure analysis
  • Liquidity profile and cash-flow projections
  • Portfolio limit control
  • Transaction processing
  • Fund classes and master-feeder structures
  • Shadow accounting workflows

Coming Sessions: Risk Shell Workflow

10 Nov 2026;
09:00AM - 10:00AM
Introduction to Risk Shell AI
12 Nov 2026;
09:00AM - 10:00AM
Risk Shell AI Advanced Workflow
16 Nov 2026;
04:00PM - 05:00PM
Macroeconomic Scenario Screening
18 Nov 2026;
04:00PM - 05:00PM
Optimization vs Risk Budgeting
19 Nov 2026;
09:00AM - 10:00AM
Databases & Data Sets
20 Nov 2026;
04:00PM - 05:00PM
Complex redemptions: hedge funds
24 Nov 2026;
09:00AM - 10:00PM
FlexiRank™: Asset Ranking Tutorial
24 Nov 2026;
09:00AM - 10:00AM
Introduction to Risk Shell AI
24 Nov 2026;
10:00AM - 11:00AM
FoF Manager: Portfolio Management
25 Nov 2026;
09:00AM - 10:00AM
Master and Feeder Portfolios

Coming Sessions: Advanced Risk Training

10 Nov 2026;
04:00PM - 05:00PM
Unique Hedge Fund problems
12 Nov 2026;
09:00AM - 10:00AM
Portfolio Optimization Advanced
13 Nov 2026;
03:00PM - 05:00PM
RiskMetrics Integration
16 Nov 2026;
08:30AM - 09:30AM
Portfolio Optimization Basics
16 Nov 2026;
04:00PM - 05:00PM
Macroeconomic Scenario Screening
18 Nov 2026;
04:00PM - 05:00PM
Private Equity Analysis
18 Nov 2026;
04:00PM - 05:00PM
Optimization vs Risk Budgeting
19 Nov 2026;
03:00PM - 04:00PM
Introduction to Style Analysis
20 Nov 2026;
08:30AM - 09:30AM
Portfolio Optimization Basics
24 Nov 2026;
04:00PM - 05:00PM
Unique Hedge Fund problems

Webinar admission terms: free access for the current ABC Quant clients and family offices. All other participants are admitted by invitation only.