Asset Selection & Manager Selection Software for Alternative Investments
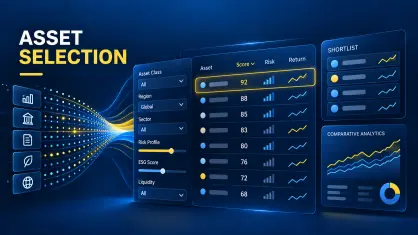
Risk Shell Screening & Asset Selection component helps institutional investors, fund of funds managers and investment research teams identify and compare funds, managers and other investment instruments using quantitative statistics, qualitative criteria, factor exposures, liquidity profiles, stress-test results and benchmark-relative analytics.
Screening rules are combined in one query and run on a trailing period or a closed interval. Users can constrain more than 100 risk and return statistics — VaR at a chosen confidence level, maximum drawdown, annualised return, volatility, the Sharpe ratio and other tail measures — and can set bands on benchmark-relative regression results: correlation, alpha, beta, upside beta and downside beta versus an index, a peer or any other instrument. The same query can bound factor betas, filter on liquidity profile and redemption terms, and apply loss thresholds from stress-test results for historical extreme events such as the 2008 credit crisis and others. Strategy, sub-strategy, dead and non-reporting status, and user-defined manager or fund fields are applied as part of that query, not as a separate pass.
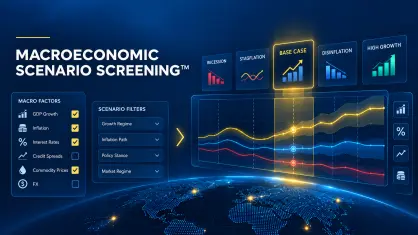
Macroeconomic Scenario Screening
Macroeconomic Scenario Screening™ combines conventional risk-return screening with user-defined macroeconomic scenarios. Macroeconomic Scenario Screening™ is a conditional asset screen. Risk and return statistics are calculated only on the aggregated historical intervals in which a user-defined set of macro factors was in a specified state, then tested against the constraints the user has set.
The constraints come first: maximum drawdown, VaR, annualized return, volatility or any other statistic in the screening set. The scenario is the joint factor state in which those constraints must hold. A stress case can require equities in a bear regime, oil prices rising and credit spreads widening. Risk Shell aggregates the periods in which those states coincided and returns the hedge funds, equities or other assets whose statistics on that sample meet the constraints. Conditional results can be combined in the same query with full-sample filters.