Portfolio Optimization Software For Fund Of Funds
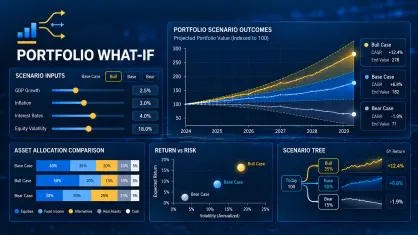
Portfolio optimization is a powerful technique for enhancing the performance of fund of funds and multi-asset portfolios. However, it is often overlooked by portfolio managers due to practical and theoretical challenges limiting its application. Many portfolio analytics vendors provide traditional models based on the mean-variance optimization, the Markowitz framework from the 1950s, which measures risk as volatility and reduces dependence to a single covariance matrix. Hedge fund returns violate both assumptions: they are skewed and fat-tailed, and correlations tend to rise exactly when a drawdown hits. Variance also penalizes upside and downside equally, so a portfolio that is efficient on volatility can still carry the tail loss it was meant to avoid.
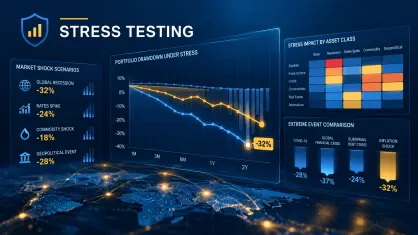
Recognizing these limitations, ABC Quant developed an advanced optimization platform that allows the use of virtually any risk statistic as an objective function or constraint. This includes VaR-based measures, the Omega function, drawdowns, fund correlations, market neutrality, and more. The same model also accepts constraints that are not weight bounds: factor sensitivities, liquidity, strategy exposure, stress-test results from the Risk Shell database, RiskMetrics holdings-based stress data, and user-defined metrics.
In 2004, ABC Quant introduced the industry's first hedge fund of funds optimization system powered by the genetic optimization algorithms and capable of resolving complex non-convex multi-extreme optimization tasks. Today, the Risk Shell optimization engine solves large scale non-convex, multi-extreme problems typical for alternative investments, hedge fund of funds and multi-asset portfolios.