Macroeconomic Scenario Screening™
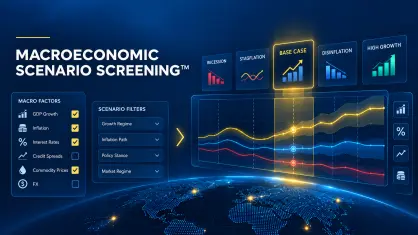
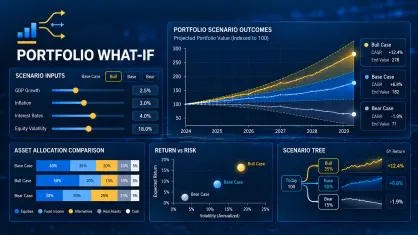
Macroeconomic Scenario Screening™ is Risk Shell's proprietary framework for selecting investments according to their historical behaviour under user-defined macroeconomic conditions. Instead of calculating investment statistics over the complete historical record, the model identifies the periods in which a specified combination of market and economic factors was present and recalculates the relevant statistics using only those observations.
This creates a conditional investment screen. The question is no longer simply whether a fund, equity or other instrument has historically delivered an acceptable return, drawdown or risk profile. The investor can ask whether those characteristics remained acceptable specifically when the macroeconomic environment matched conditions relevant to the investment mandate.
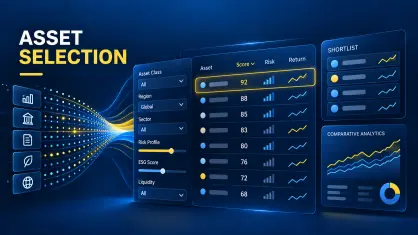
Conditional Asset Selection
The investment constraints and the macroeconomic scenario perform separate functions within the model. The constraints define the characteristics an investment must satisfy: for example, minimum annualised return, maximum drawdown, VaR, volatility, downside risk, correlation or another Risk Shell statistic. The macroeconomic scenario determines the historical sample on which those statistics are calculated.
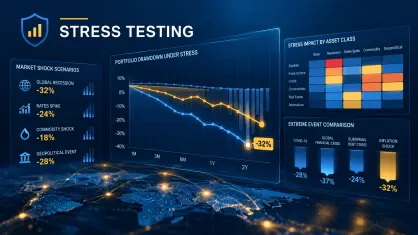
A scenario can, for example, specify equities in a bearish state, oil prices rising and credit spreads widening. Risk Shell identifies the historical intervals in which these factor states occurred simultaneously, aggregates the observations from those intervals and recalculates the selected investment statistics on the resulting conditional sample.
The screening engine then evaluates the investment universe against the user's constraints using those conditional statistics. Assets that performed well over the full historical period but behaved poorly during the selected macroeconomic conditions can therefore be distinguished from investments whose risk-return characteristics remained acceptable within the scenario.
Macroeconomic Factor States
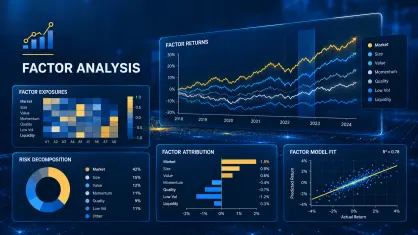
Risk Shell uses Trend Segmentation™ to identify the relevant states of the selected market and macroeconomic factors. Rather than requiring the user to specify individual historical dates, the scenario is expressed directly through factor behaviour — for example rising, falling or neutral conditions — and Risk Shell determines when the required combination occurred historically.
Multiple factors can be combined into the same scenario. The conditional sample consists only of observations for which the required factor states overlap. This makes it possible to analyse investment behaviour under compound environments that are difficult to isolate through conventional performance screening.