
ABC Quant Blog: Views on Risk Management
Credit Risk is the risk of loss resulting from deterioration in the credit quality of an issuer or counterparty, including rating changes, widening credit spreads and default.
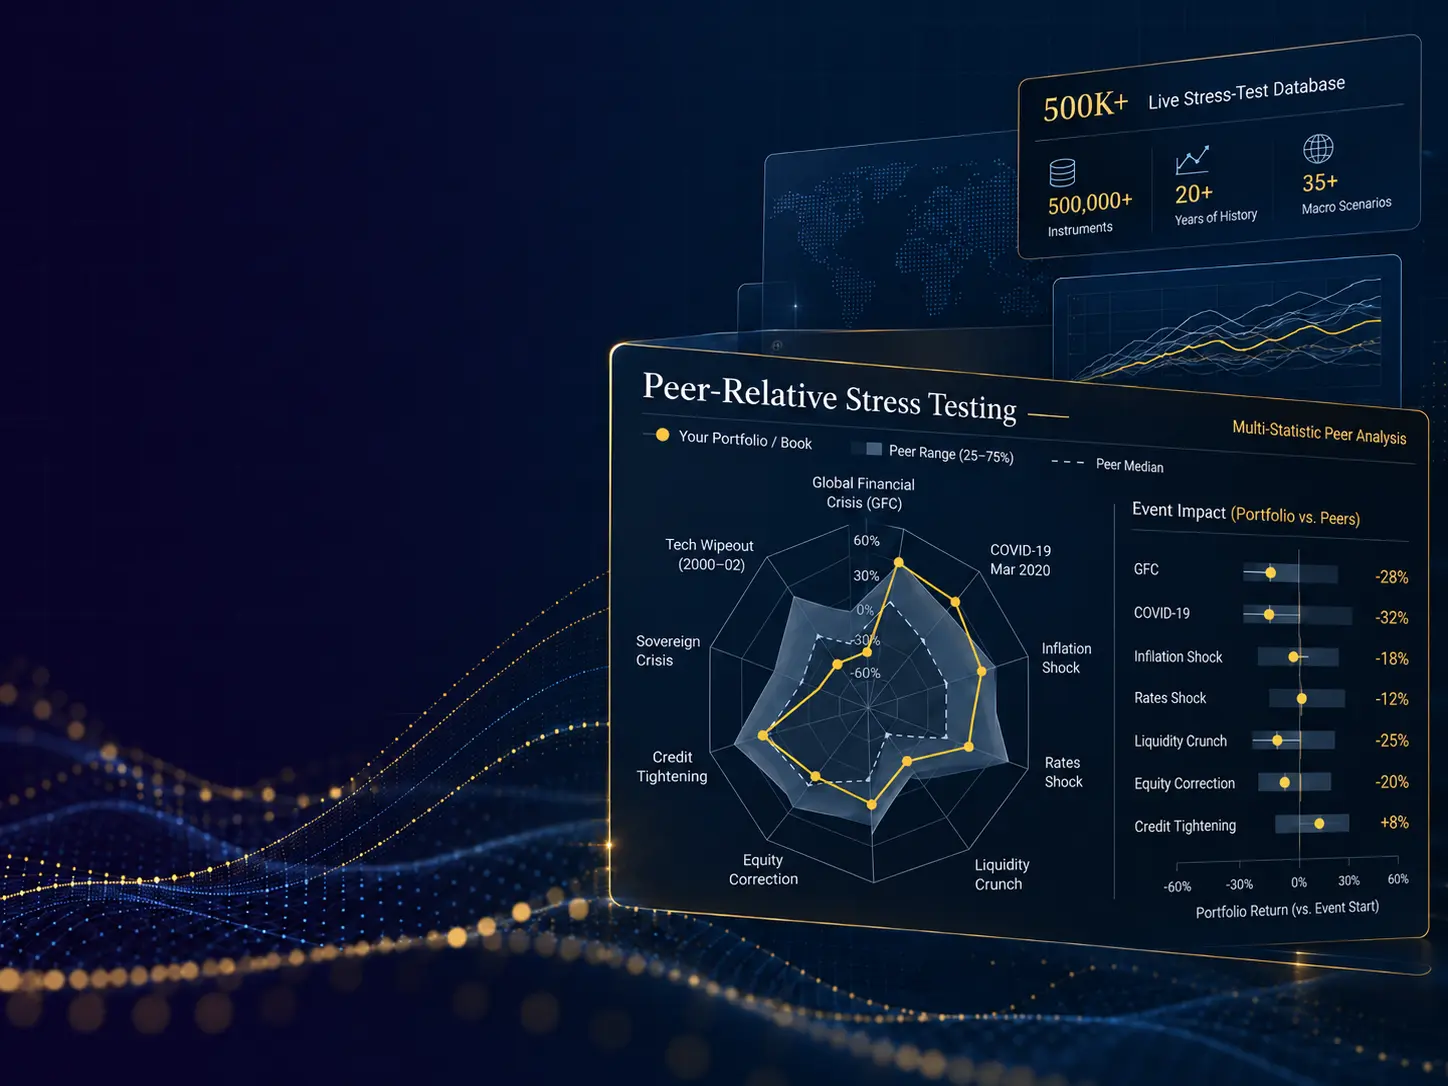
Event Risk is the risk of substantial loss caused by extreme market conditions that cannot be adequately assessed using conventional return and risk statistics.
Currency Risk arises when a hedge fund or portfolio holds assets denominated in currencies different from its reporting or base currency, causing exchange-rate movements to affect portfolio value.
Market Risk is the risk of loss caused by changes in market prices and market factors affecting a hedge fund's positions. For hedge funds, its measurement often requires risk statistics beyond volatility and conventional VaR.
Liquidity Risk is the risk that a hedge fund cannot meet redemption, margin or other cash obligations without delaying payment, borrowing funds or selling assets at materially unfavorable prices.
Volatility Risk refers to losses caused by unexpected changes in market volatility. It can affect a hedge fund directly through volatility-sensitive instruments or indirectly through changes in the behavior of the trading strategy.
Concentration Risk arises when a hedge fund or multi-manager portfolio has excessive exposure to a security, issuer, sector, strategy, manager, market factor or group of economically correlated positions.
Strategy Risk arises when a hedge fund's investment process, portfolio construction or market exposures deviate materially from the strategy expected by investors, potentially changing the fund's market, credit, liquidity or other risk characteristics.
Operational Risk is the risk of loss resulting from failures in a hedge fund's internal processes, personnel or systems, or from external events affecting its investment and operating activities.
Legal Risk is the risk of loss arising from unenforceable or defective contractual arrangements, insufficient legal authority, non-compliance with applicable requirements, legal disputes or changes in laws and regulations affecting a hedge fund, its manager or its investments.
Fraud risk is the risk of loss arising from intentional misconduct, misrepresentation or misappropriation by persons able to influence a hedge fund's assets, records, valuations or reporting.
Value-at-Risk (VaR) estimates the potential loss in the value of a portfolio or investment over a specific time horizon and under a given level of confidence.
Page 1 of 2