
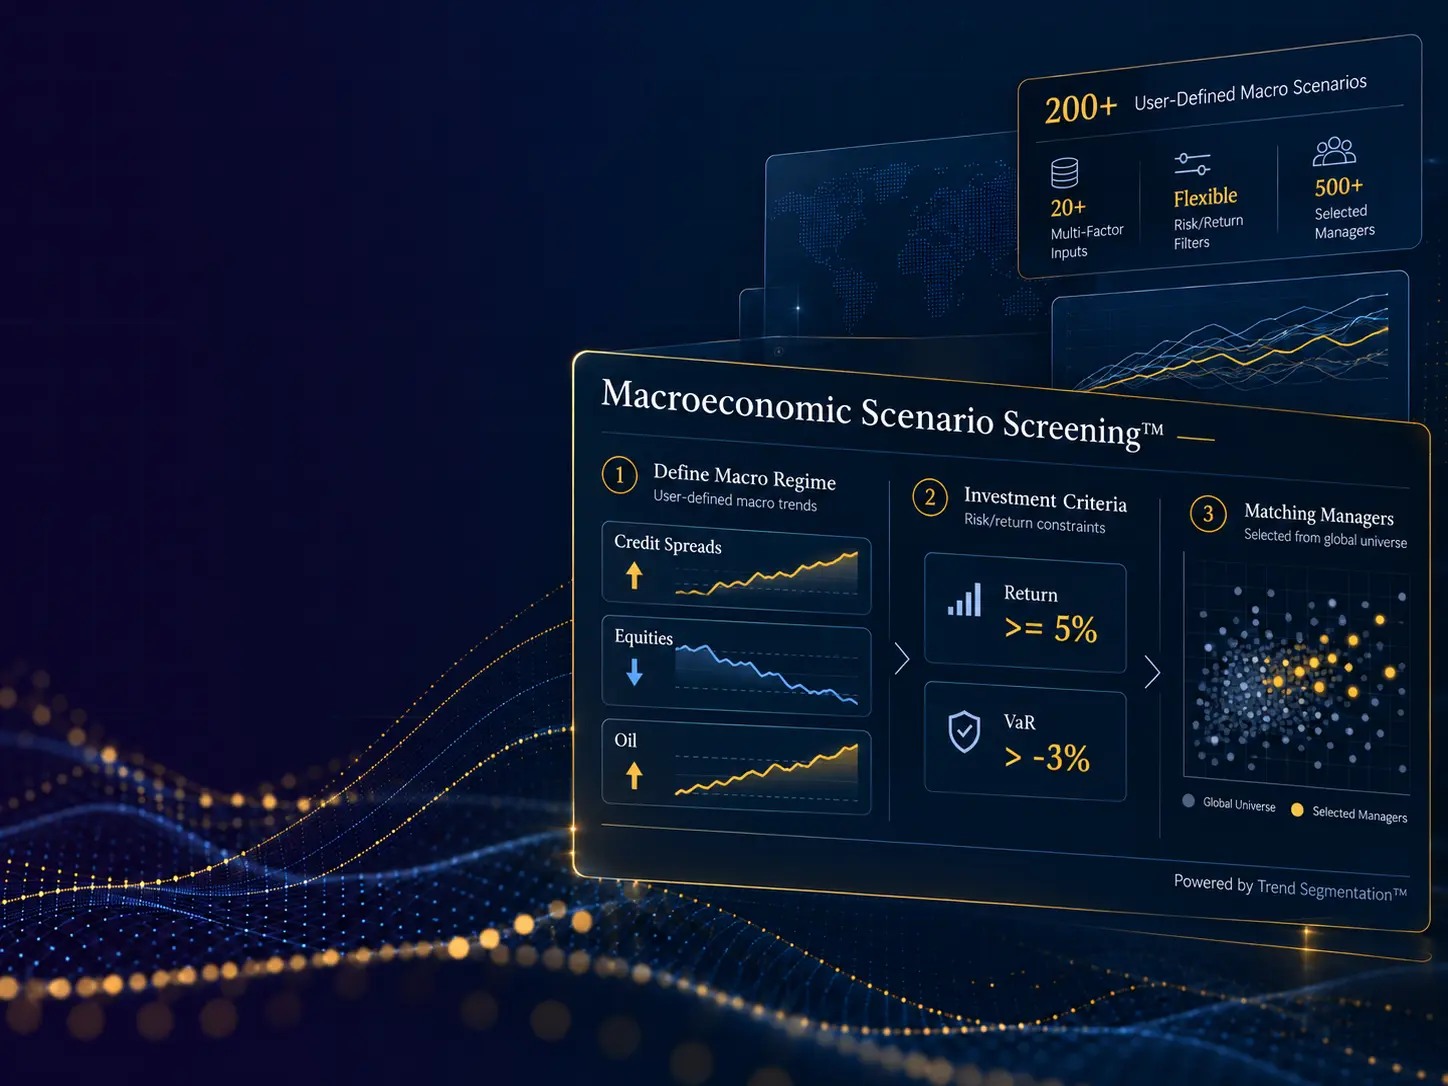
Credit Risk arises when the financial condition or perceived creditworthiness of an issuer or counterparty deteriorates. The resulting loss may occur through default, a rating downgrade, widening credit spreads or a reduction in the market value of instruments exposed to that credit.
For hedge funds investing in bonds, loans, structured credit or credit derivatives, credit risk can represent a major source of portfolio return and loss. A position may lose value well before an actual default if investors require a higher yield to compensate for increased credit risk. Consequently, credit analysis should consider both default risk and the effect of changes in credit quality on market prices.
Credit Risk should be assessed at the issuer or obligor level, with particular attention to default probability, rating migration, credit-spread changes and concentration of exposures to individual issuers, sectors or credit-quality groups. For portfolios containing bonds, loans, structured credit or credit derivatives, the analysis should determine how deterioration in underlying credit quality may affect both instrument values and aggregate portfolio losses.
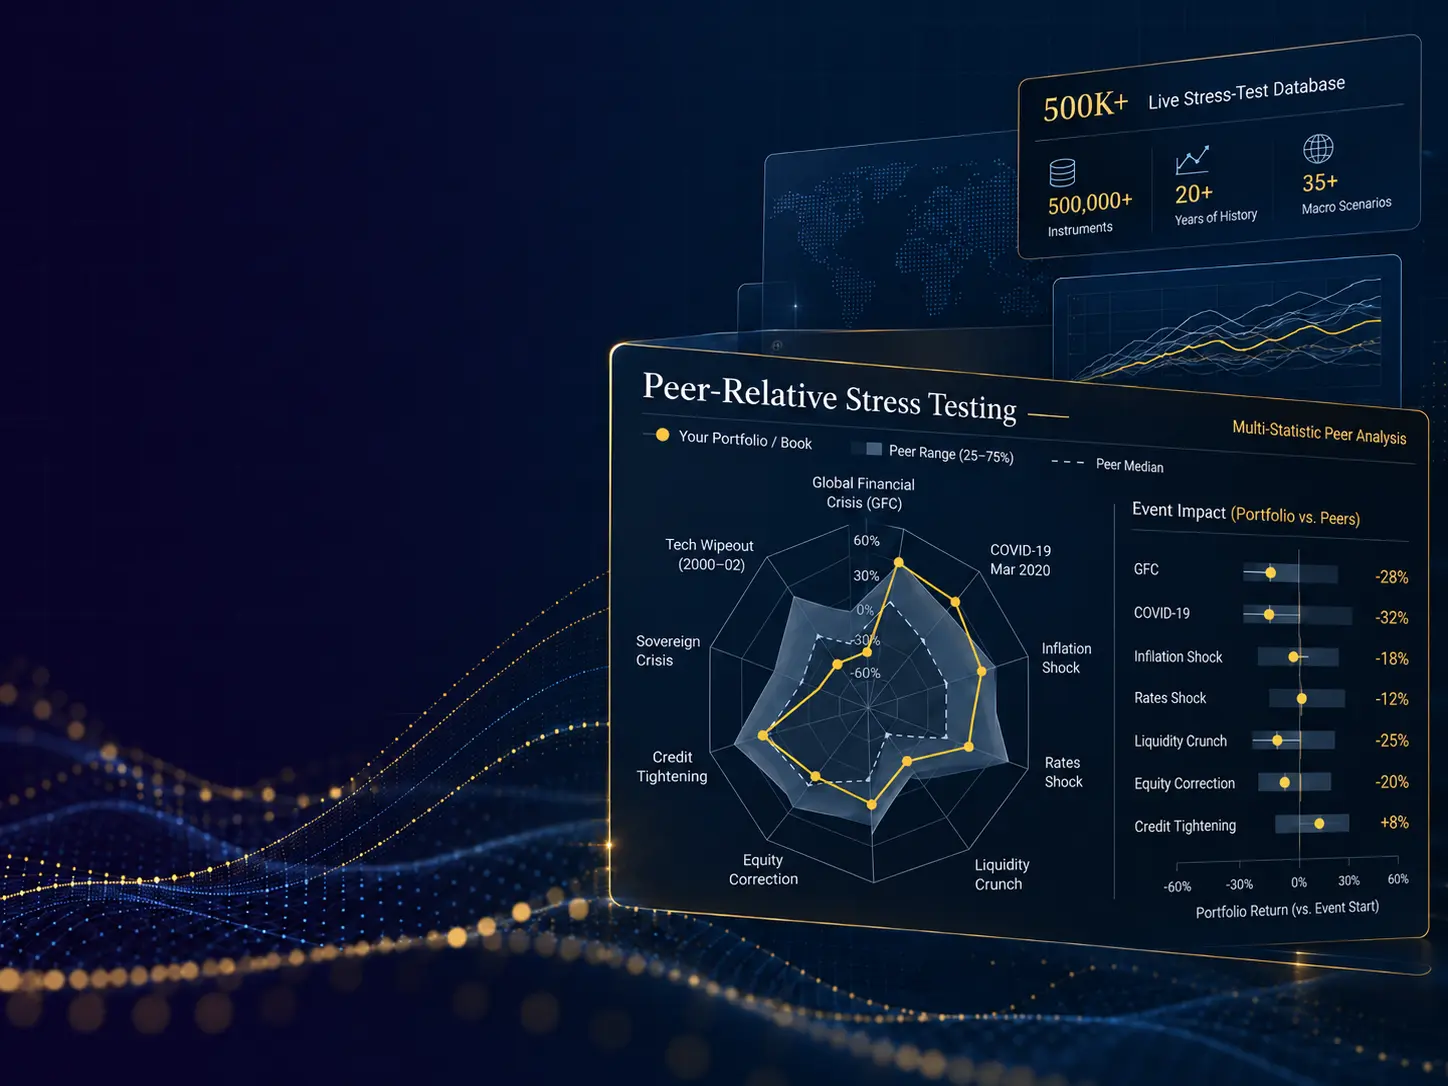
Credit risk can be assessed using issuer and counterparty limits, credit-quality analysis, spread sensitivity, concentration analysis, stress testing and quantitative portfolio models. VaR-based methods may also be applied to estimate losses resulting from changes in credit spreads or credit quality, although default and extreme credit events require separate consideration.
Due diligence should identify where credit exposure is concentrated, how the manager establishes and monitors limits, and whether changes in issuer or counterparty quality are reflected promptly in portfolio decisions. For leveraged or concentrated strategies, relatively small changes in credit conditions can have a disproportionate effect on portfolio value.