
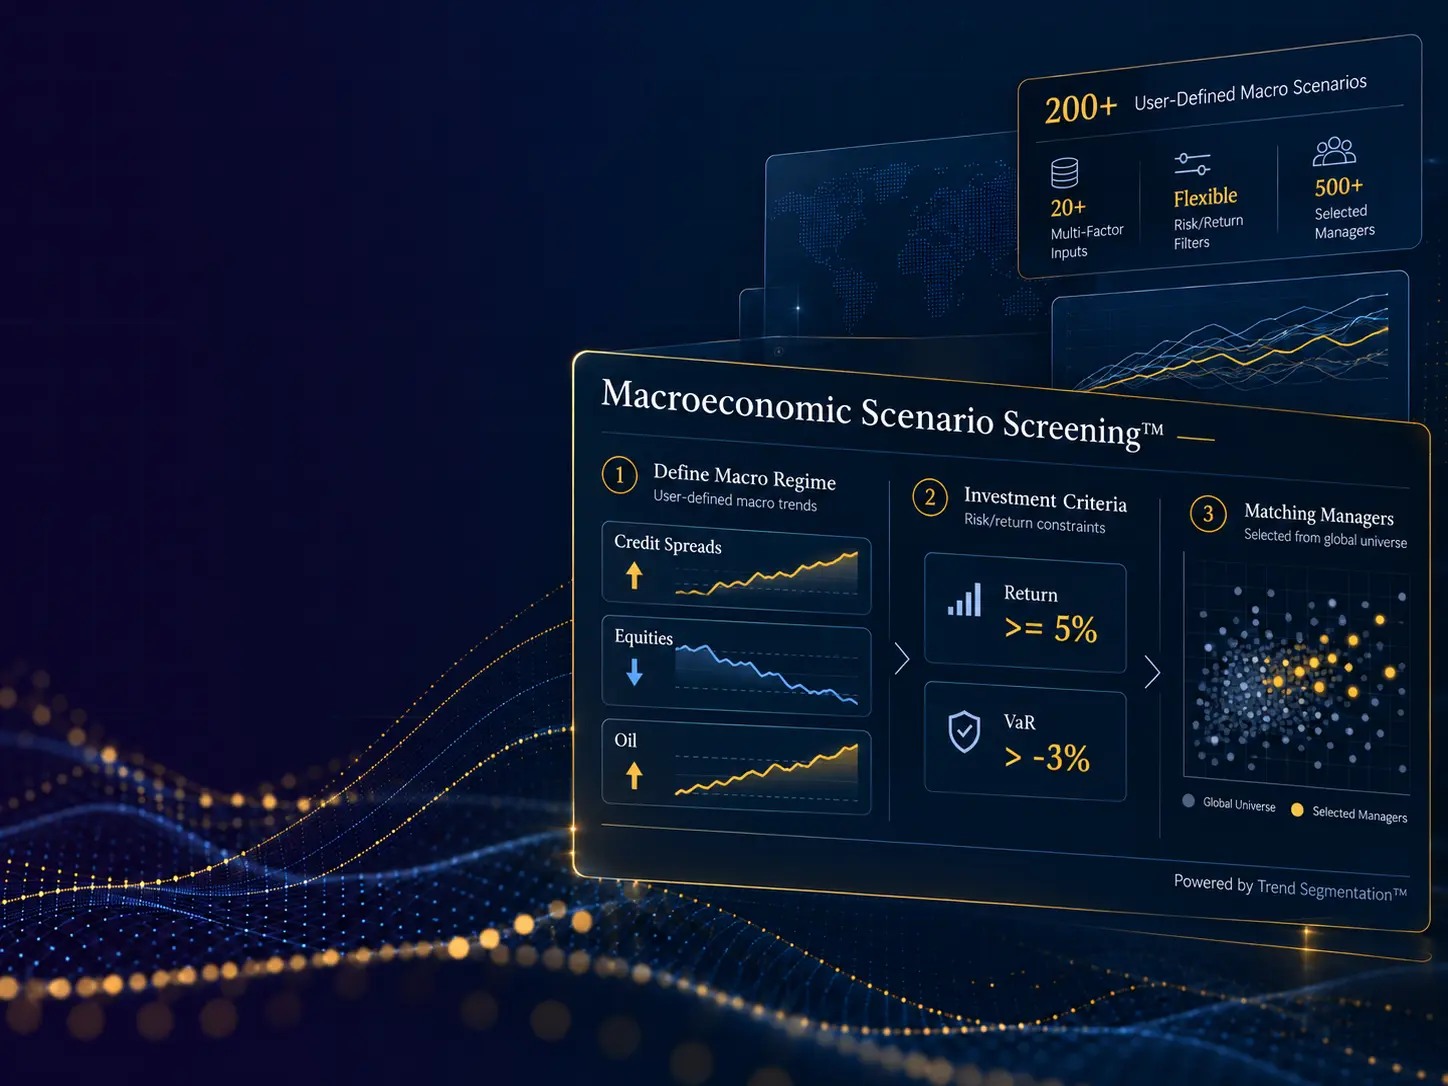
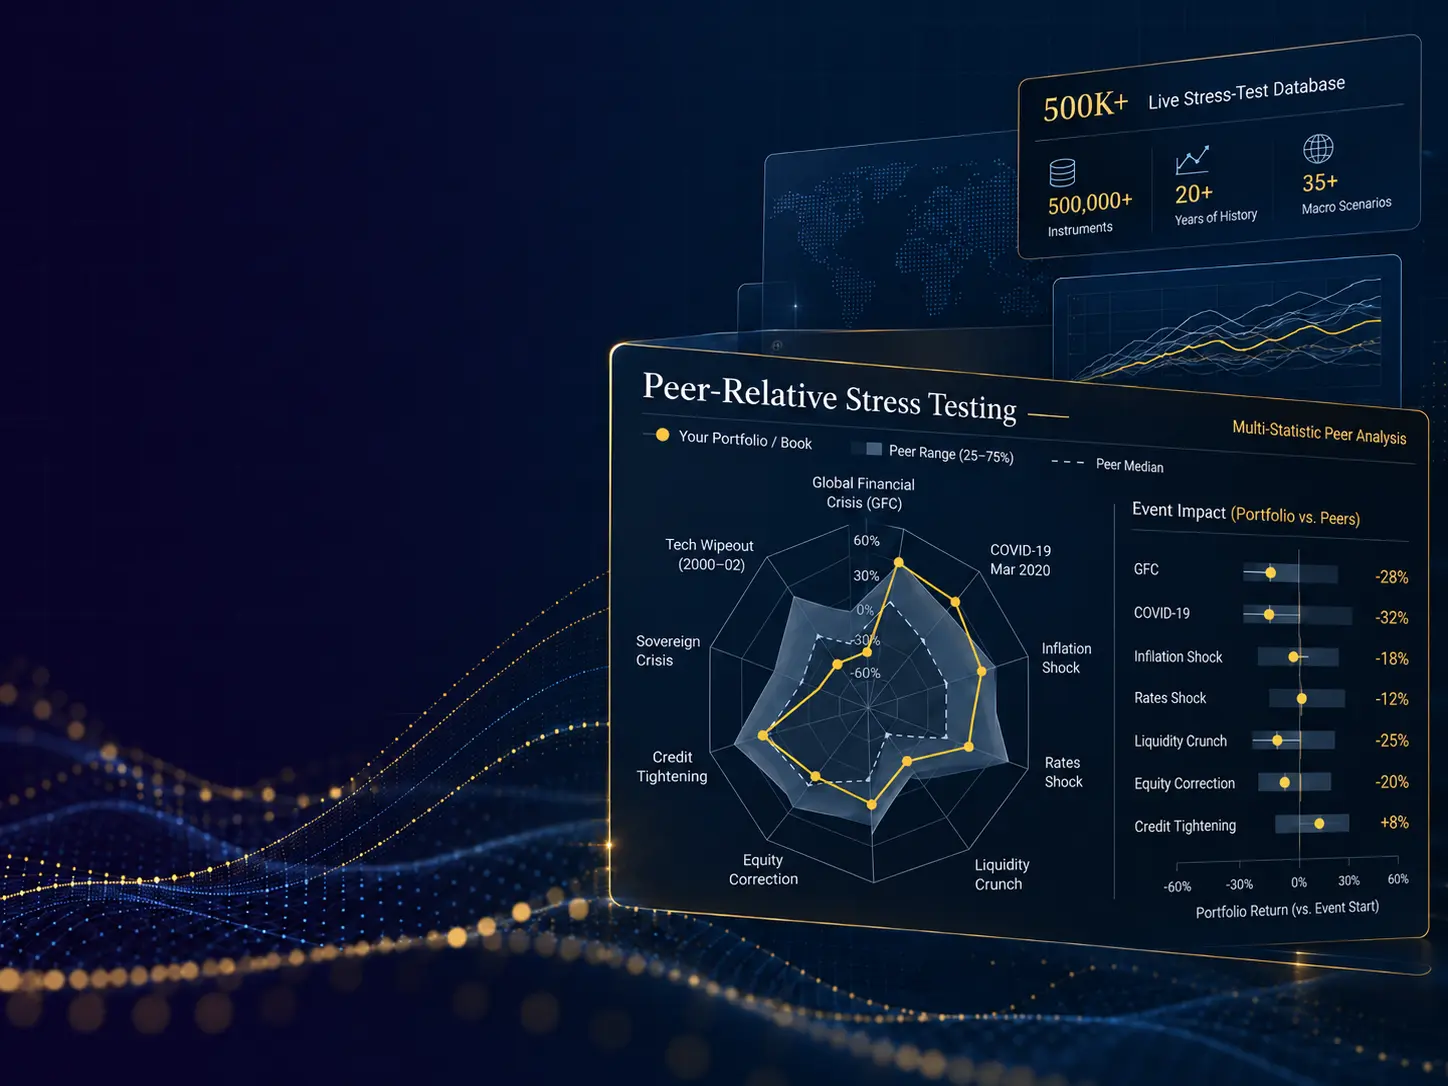
Market Risk arises from changes in market prices and other market factors that affect the value of a hedge fund's positions. Depending on the strategy, relevant exposures may include equity prices, interest rates, credit spreads, currencies, commodities and volatility. Leverage and derivatives can substantially increase the effect of relatively small market movements.
For traditional portfolios, market risk is often summarized using volatility, beta or Value-at-Risk (VaR). These measures are also useful for hedge funds, but they may provide an incomplete picture. Hedge fund returns frequently exhibit skewness, excess kurtosis and nonlinear behavior, particularly in strategies involving options, credit, arbitrage or dynamic trading rules. Two funds with similar volatility or VaR can therefore have materially different downside characteristics.
For this reason, hedge fund risk analysis should use several complementary statistics rather than rely on a single measure. Conditional Value-at-Risk (CVaR) estimates the average loss beyond the VaR threshold and therefore provides information about the severity of tail losses. Higher moments, particularly skewness and kurtosis, help identify asymmetric return distributions and unusually heavy tails that standard deviation does not capture.
Omega evaluates the return distribution relative to a selected threshold by comparing probability-weighted gains above that threshold with losses below it. Unlike measures based only on the first two moments of the distribution, it incorporates information from the complete observed return distribution and can therefore be useful when comparing hedge funds with materially different distribution shapes.
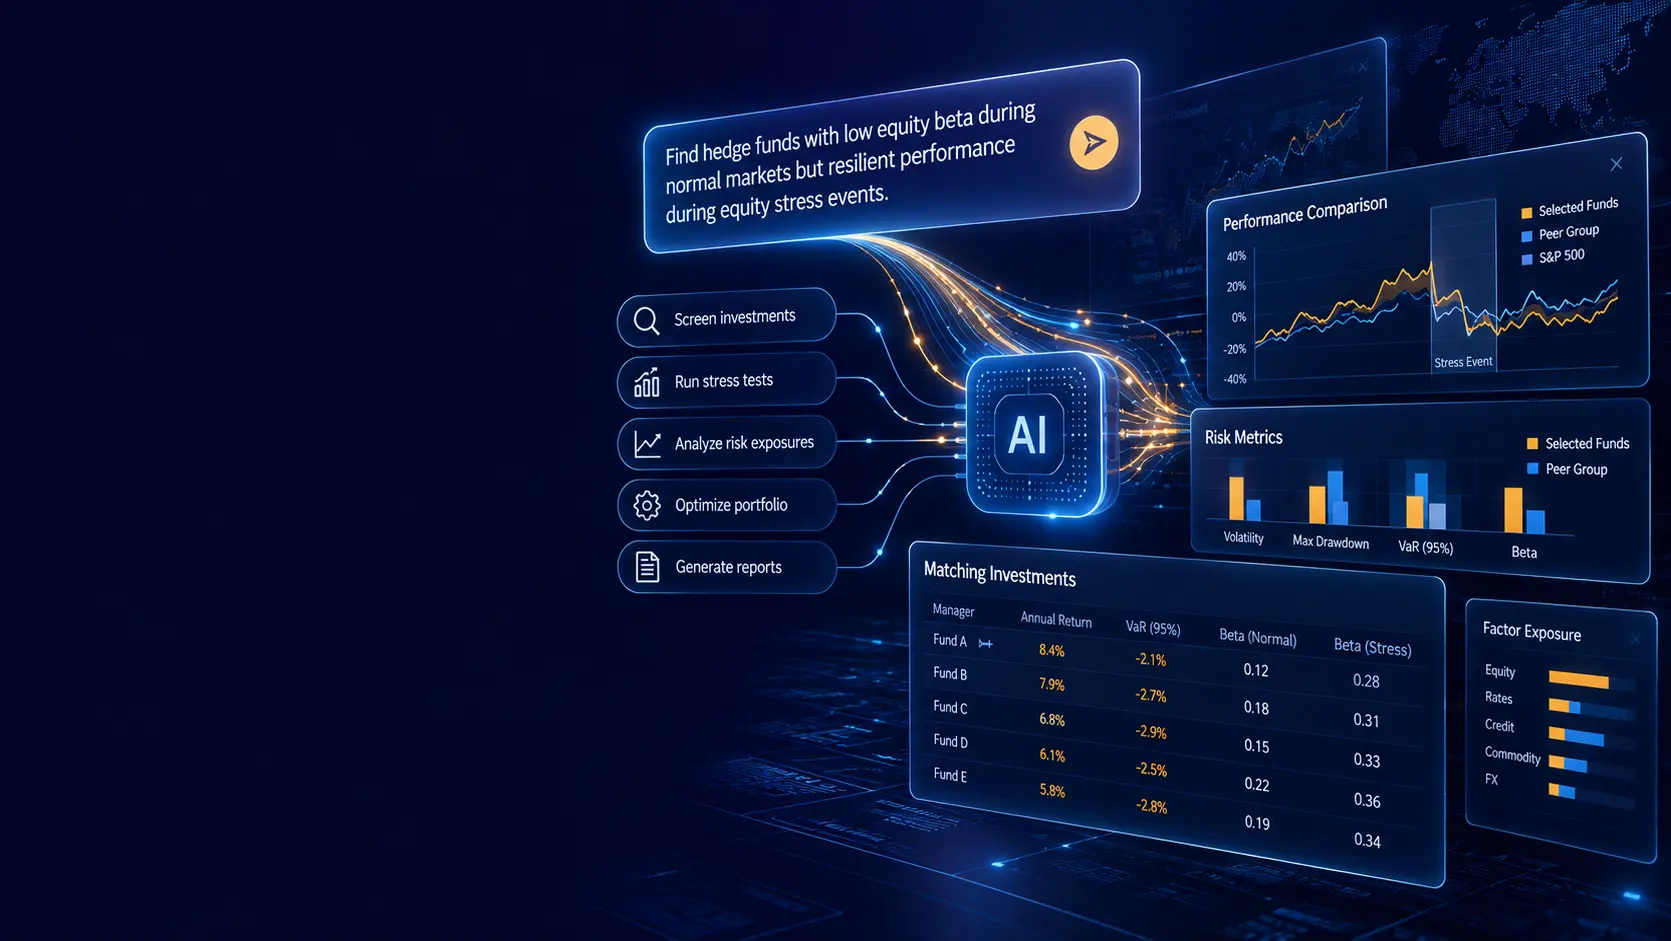
No single statistic provides a complete measure of market risk. VaR describes a loss threshold but not the magnitude of losses beyond it; volatility treats positive and negative deviations symmetrically; and higher moments can be unstable when estimated from short return histories. The appropriate approach is therefore to examine several measures together and determine whether they give a consistent picture of the fund's downside and tail-risk characteristics.
For hedge fund due diligence, market-risk assessment should focus on the actual behavior of the return distribution and the exposures generating it. Particular attention should be given to leverage, nonlinear payoffs, changing factor sensitivities and tail losses that may not be apparent from conventional volatility-based statistics.