
Volatility Risk refers to the effect of unexpected changes in market volatility on a hedge fund's positions or overall performance. The most direct exposure occurs in portfolios containing options and other derivatives whose prices depend on the expected volatility of the underlying assets. A change in volatility can therefore alter the value of these instruments even when the price of the underlying asset remains relatively stable.
However, volatility risk is not limited to portfolios holding derivatives. Many hedge fund strategies perform differently during low- and high-volatility periods. A strategy may produce stable returns under normal market conditions but experience substantially different results when volatility rises. This behavior may arise from the structure of the trading strategy itself rather than from an explicit position in volatility.
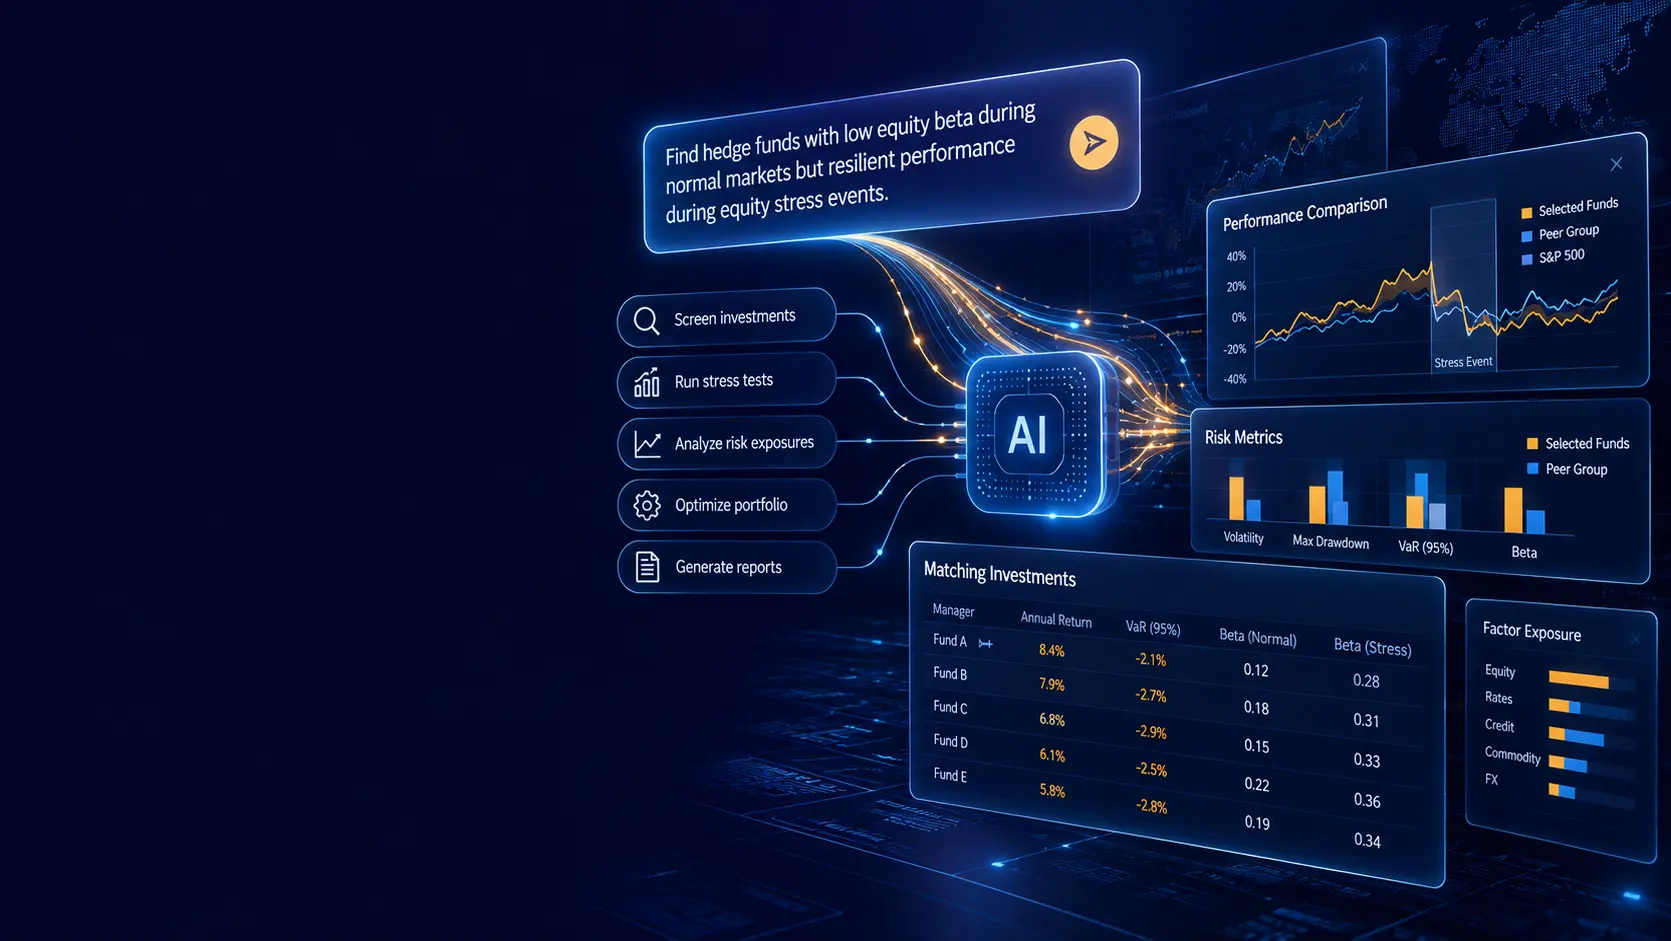
For this reason, hedge fund analysis should examine the relationship between historical fund returns and changes in market volatility. A persistent sensitivity may indicate that volatility is one of the important drivers of the strategy's performance. The relationship may also change over time, making rolling analysis more informative than a single correlation calculated over the entire return history.
Volatility sensitivity should not automatically be classified as undesirable. Its significance depends on the investment strategy and on the role of the fund within the overall portfolio. The important issue is whether the exposure is understood and whether a sharp change in market volatility could produce results materially different from those expected from the fund.