
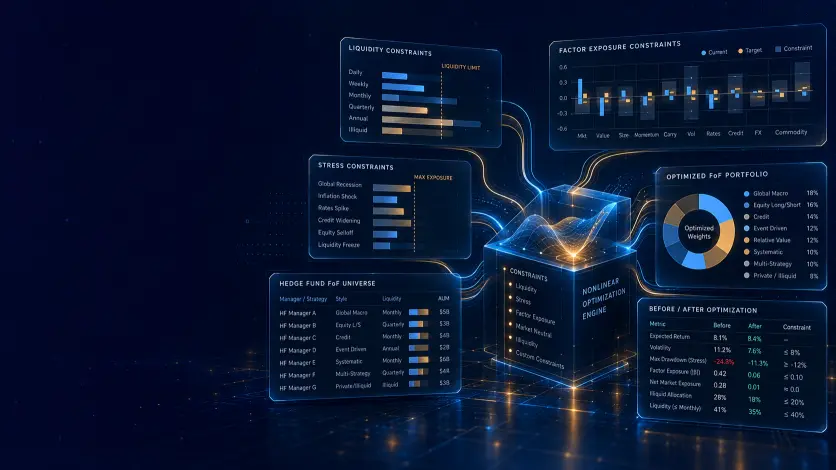
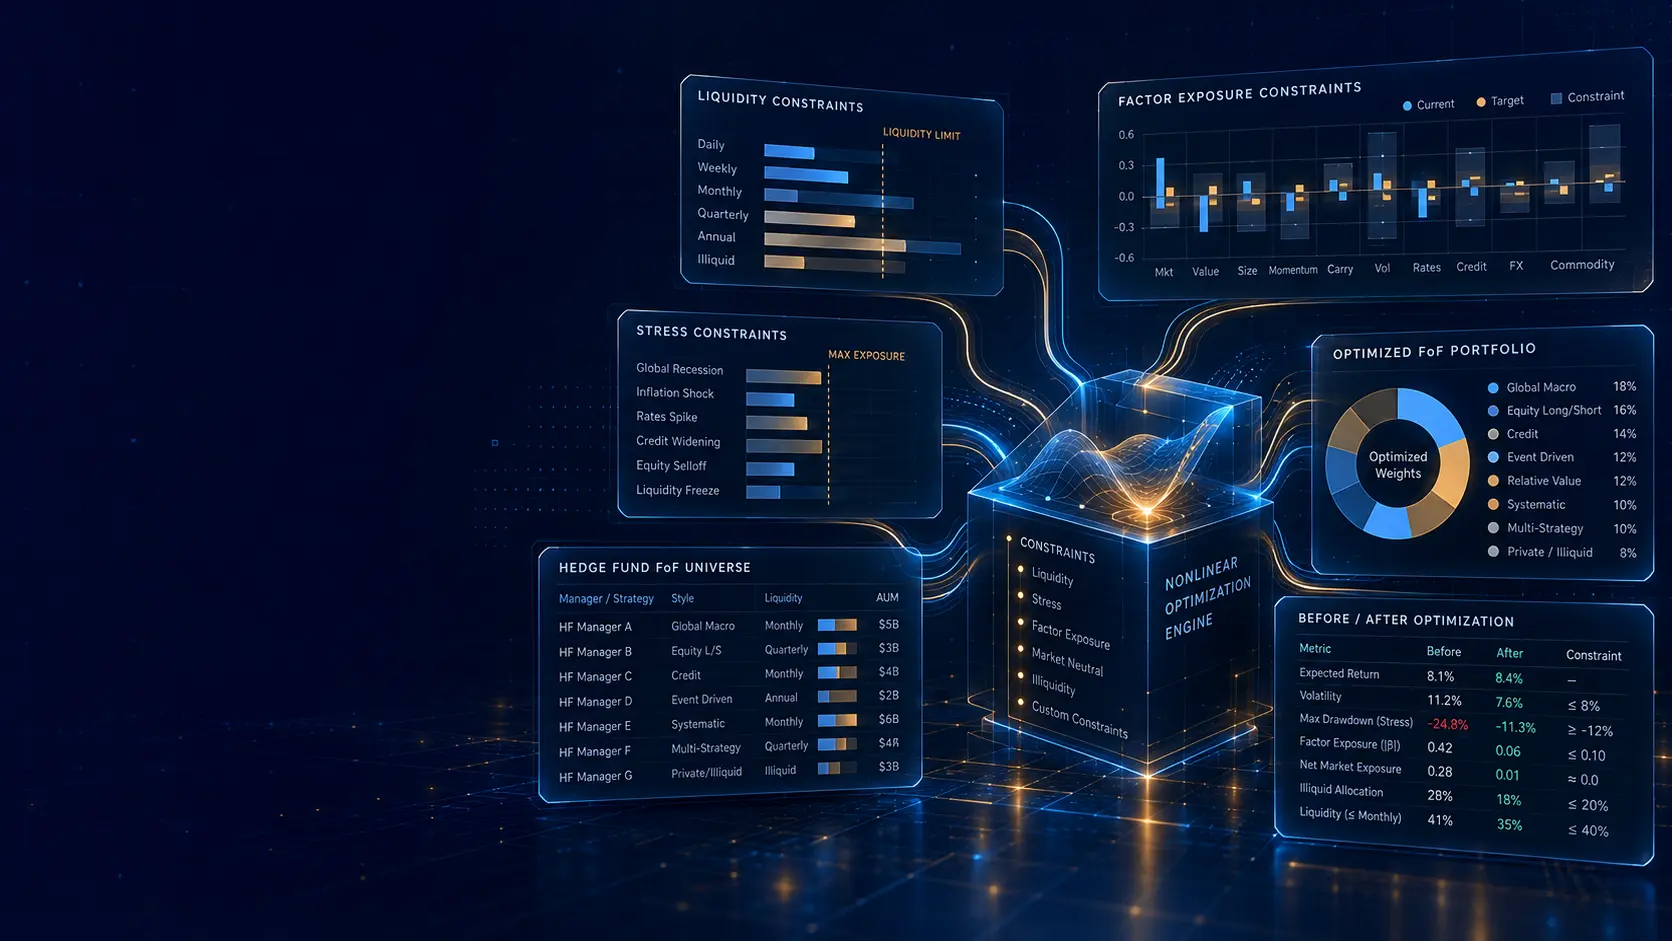
Strategy Risk arises when the actual sources of portfolio return and risk change materially from those implied by the fund's stated investment strategy. Such changes may result from deliberate repositioning, changes in the opportunity set, portfolio-manager decisions, leverage adjustments, changes in portfolio concentration or a gradual migration toward different markets, instruments or trading techniques.
A common quantitative manifestation of strategy risk is style drift: a change in the fund's sensitivity to the market factors that historically explained its returns. Returns-based factor analysis can be used to estimate these sensitivities, while rolling regressions show how factor coefficients change through time. A fund may, for example, exhibit increasing equity beta, credit-spread sensitivity, duration exposure or dependence on another systematic risk factor even though its reported strategy classification remains unchanged.
Style drift is not necessarily evidence of deteriorating investment discipline. Hedge fund strategies are frequently dynamic, and changes in factor exposure may represent an intentional response to changing market conditions or investment opportunities. The relevant due-diligence question is whether the observed change is consistent with the stated mandate, investment process and risk limits, and whether the manager can explain the economic source of the new exposure.
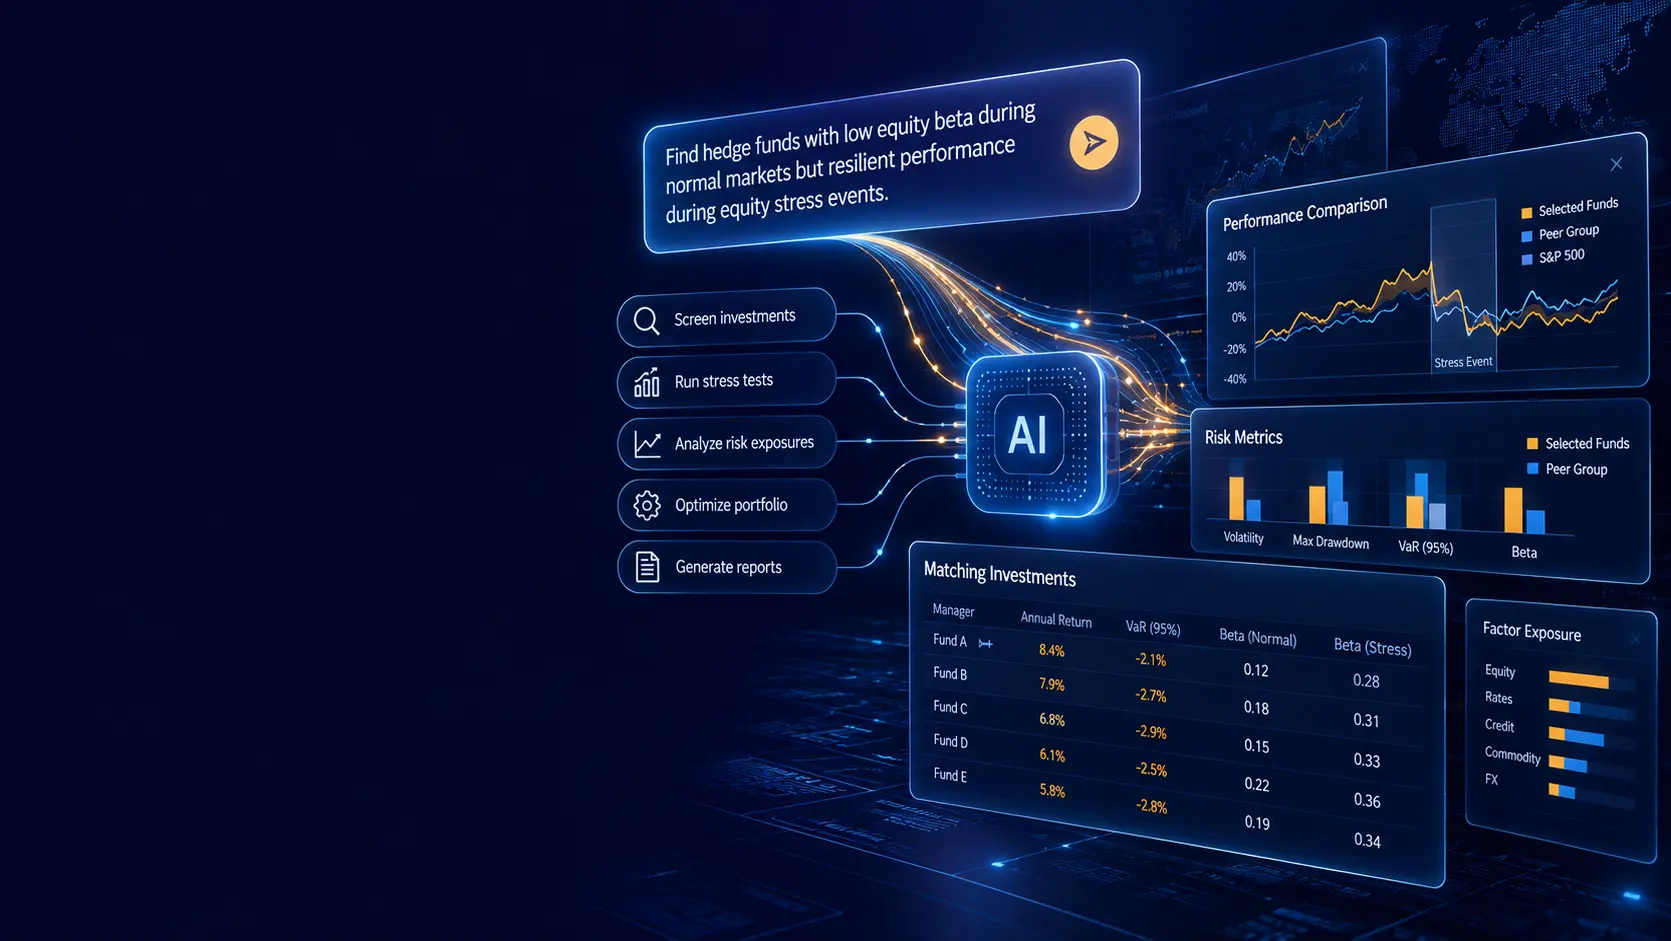
Unexpected or persistent drift requires closer analysis because it can alter the role of the fund within a multi-manager portfolio. A manager selected for low equity sensitivity, for example, may become materially more correlated with equity markets after increasing directional exposure. Similar changes in credit, volatility, liquidity or leverage characteristics can increase portfolio-level risk even where the fund's standalone volatility remains relatively stable.
Strategy-risk monitoring should therefore combine rolling factor exposures with leverage, concentration, drawdown, correlation and stress-test analysis. Factor models also require careful interpretation: estimated exposures depend on the selected factors and observation window, and linear models may not fully capture option-like or other nonlinear return profiles.
The objective is not to classify every change in exposure as undesirable, but to determine whether changes are economically significant, consistent with the manager's stated process and acceptable within the investor's portfolio. Material unexplained drift may indicate a change in strategy, risk appetite or portfolio construction that requires further investigation.