
Event Risk arises when an investment or portfolio is exposed to severe market conditions outside the range represented by normal historical observations. Credit crises, emerging-market collapses, abrupt currency or interest-rate shocks and major equity-market dislocations can produce losses that bear little relation to risk estimates obtained under normal market conditions.
Conventional statistics such as annualized return, standard deviation and the Sharpe Ratio are largely inapplicable to Event Risk. They summarize historical return characteristics but do not estimate how an investment would respond to a specified extreme event. Even VaR and other distribution-based measures may materially understate losses when market behavior departs from the assumptions or historical sample used in their estimation.
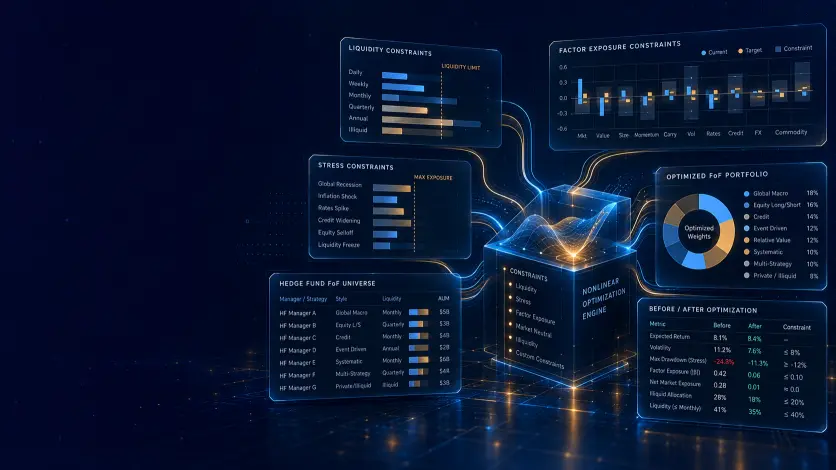
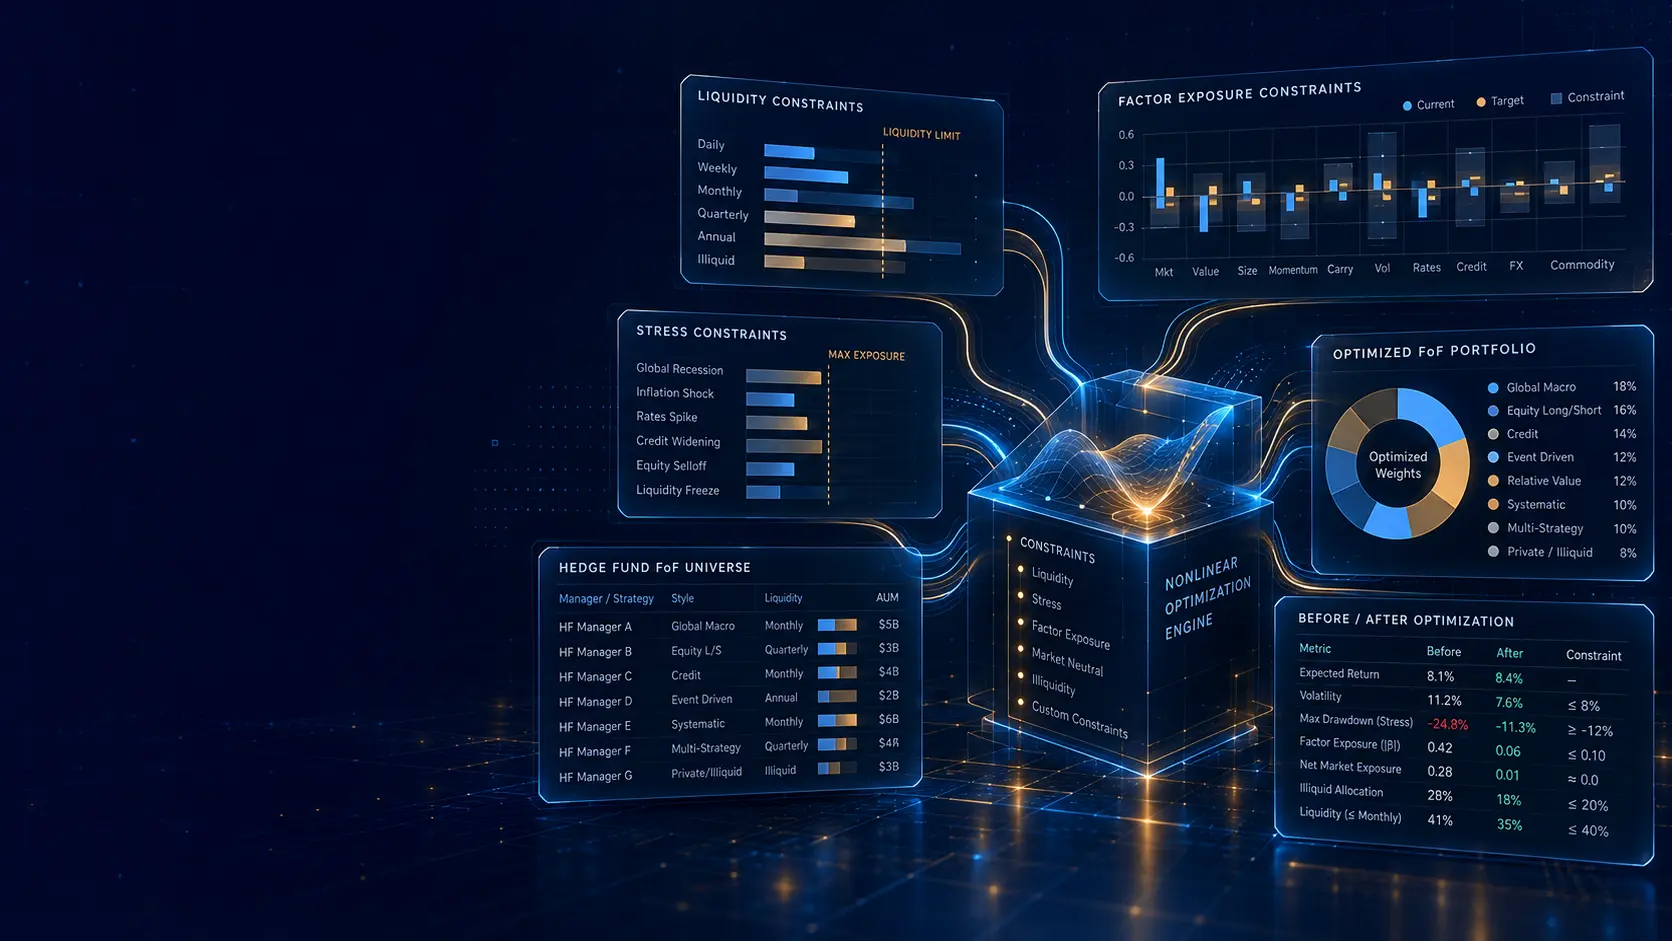
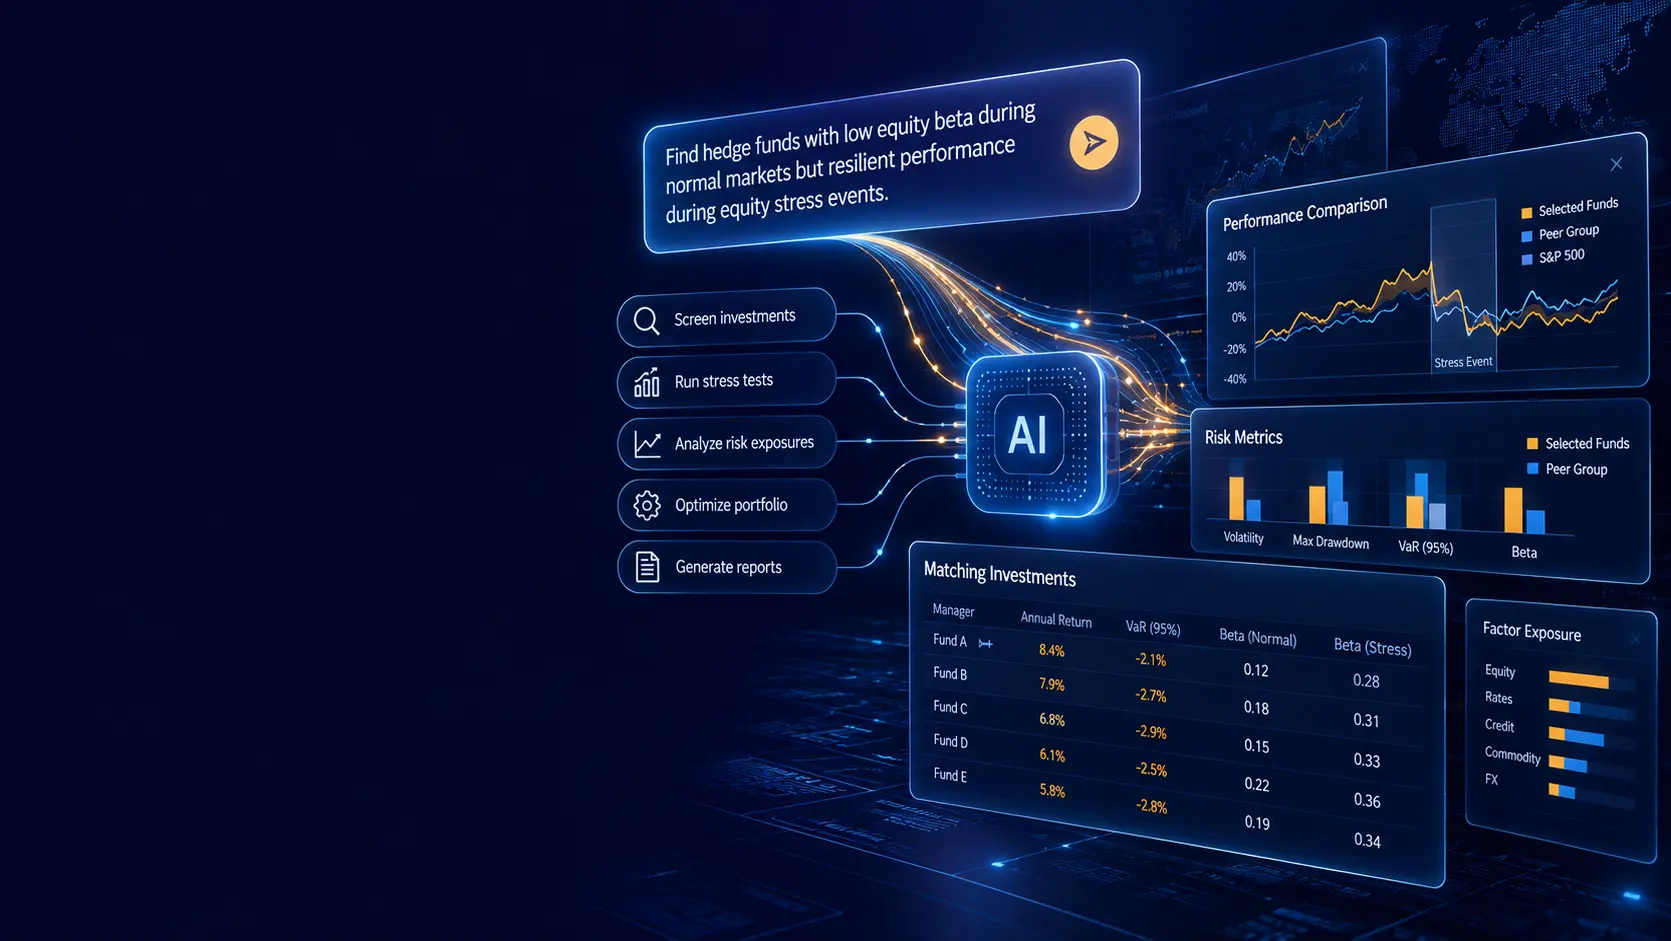
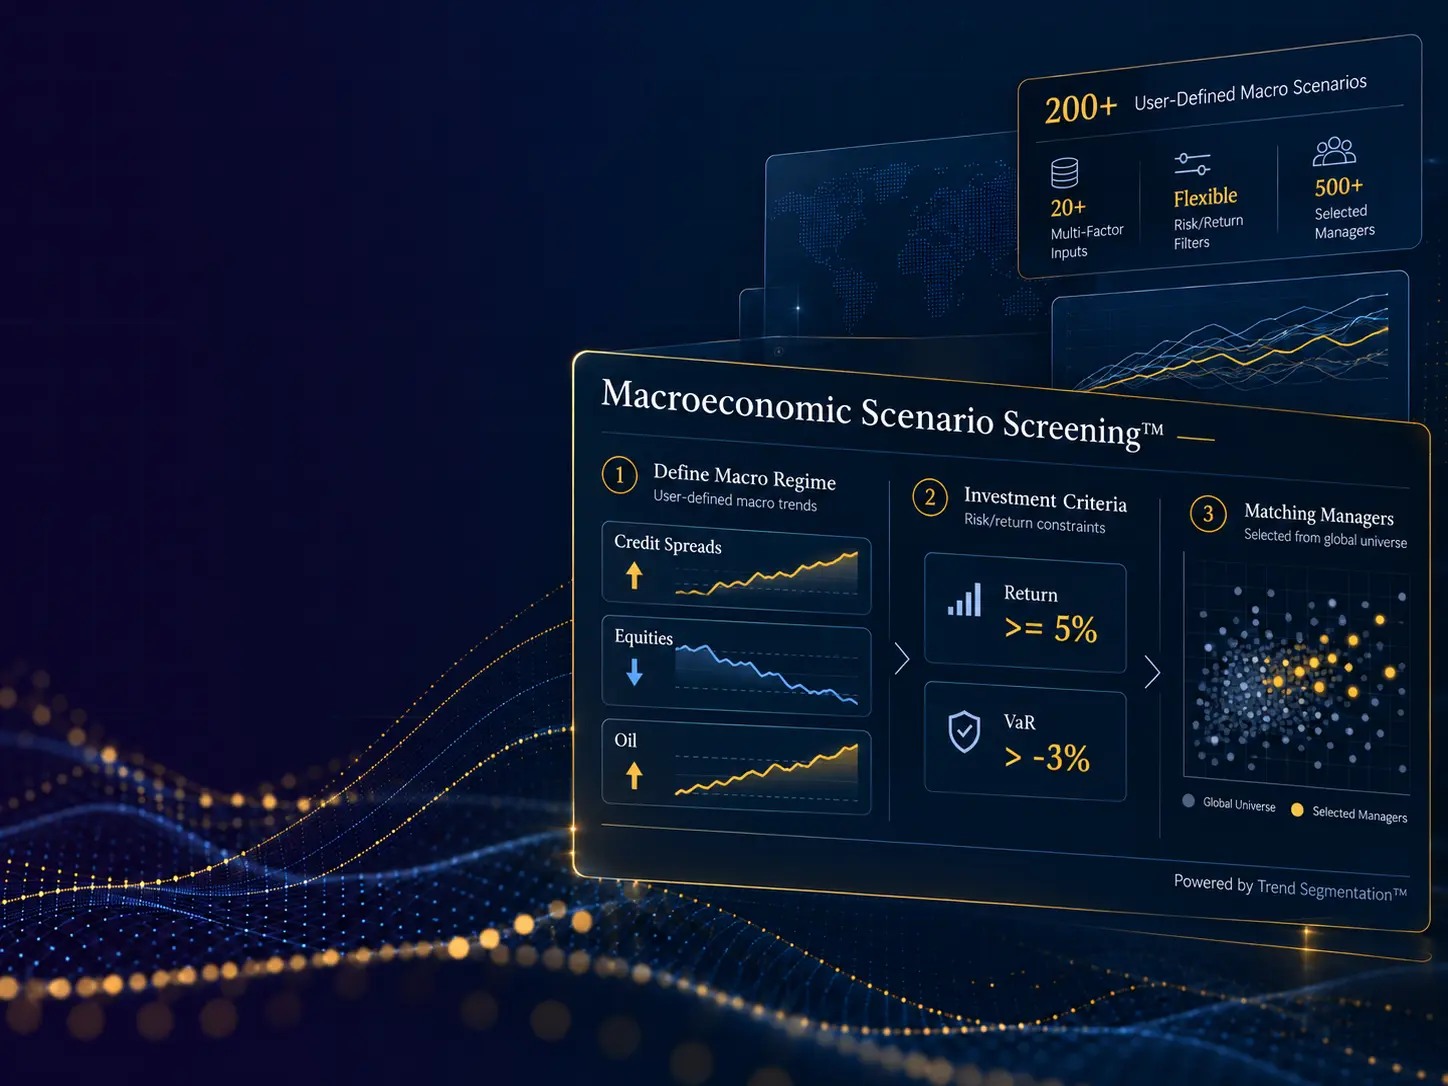
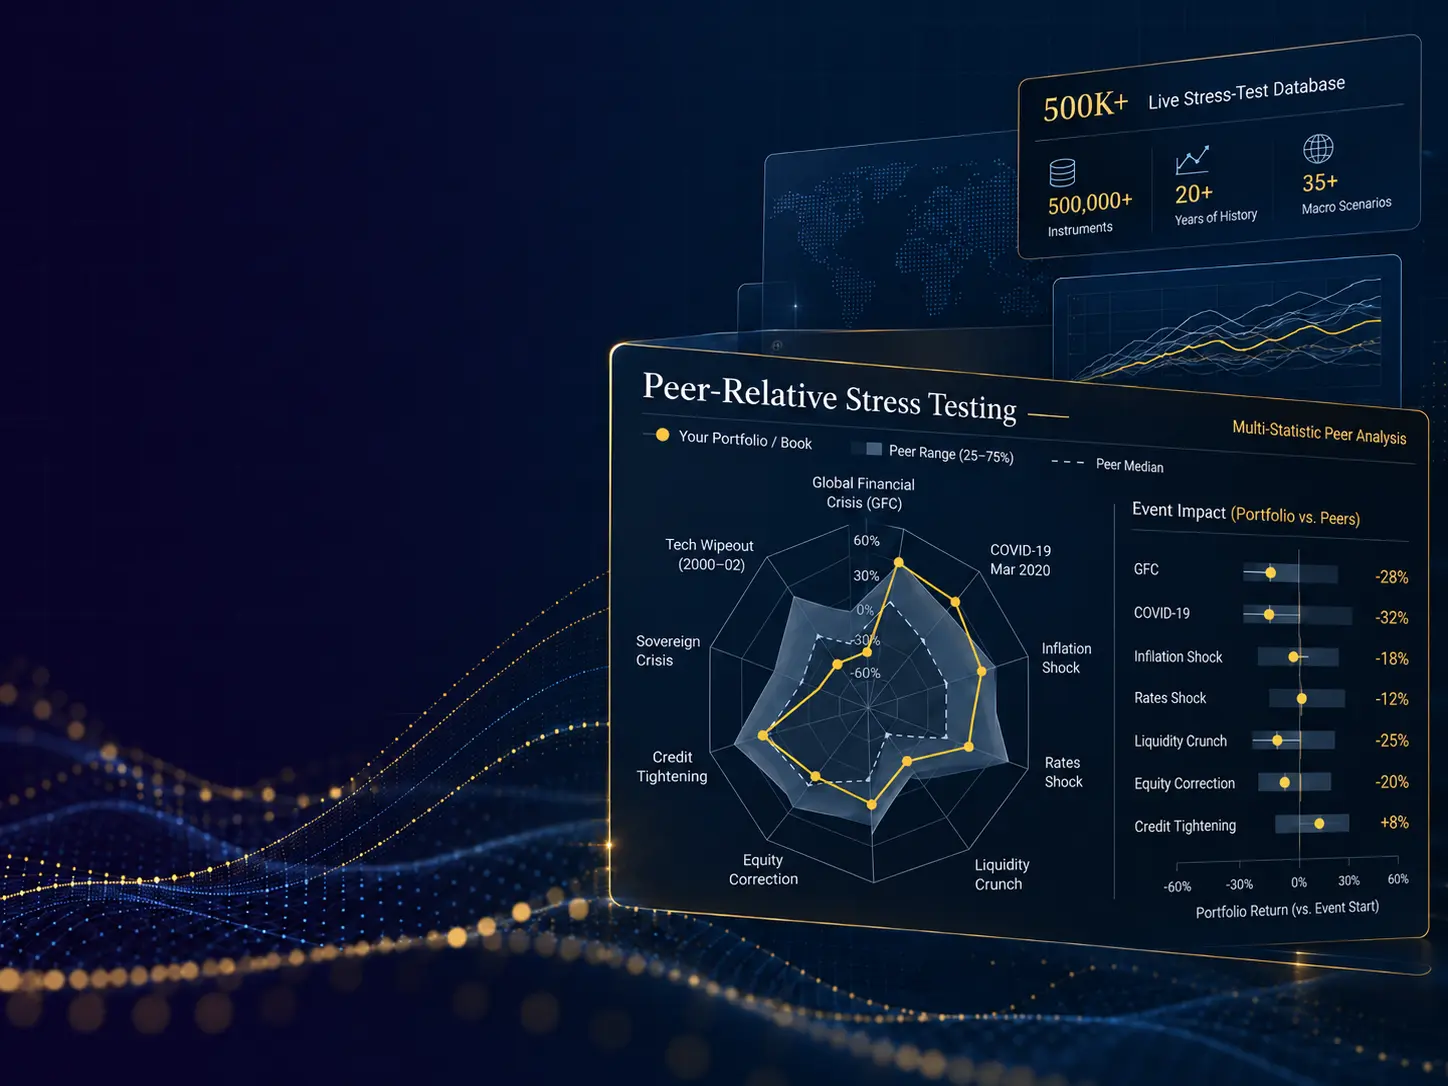
Stress Testing is therefore the principal technique for assessing Event Risk. Historical stress tests apply market shocks observed during previous crises to the current investment or portfolio. Hypothetical "what-if" stressing scenarios apply user-defined changes in market factors to examine exposures that may not have occurred together historically.
For hedge funds, Event Risk may be amplified by leverage, nonlinear positions, concentrated factor exposures and changes in correlations during stressed markets. Diversification observed under normal conditions may also deteriorate when several assets or strategies become exposed to the same adverse market factors.
Event Risk analysis should therefore focus on the estimated portfolio impact of explicitly defined extreme scenarios rather than on extrapolation from conventional historical statistics. Stress tests should be repeated as portfolio composition and factor exposures change.