
Liquidity Risk arises when the liquidity of a hedge fund's assets is insufficient relative to its cash obligations. The principal issue is the mismatch between the time required to convert portfolio holdings into cash and the time within which the fund must satisfy redemptions, margin calls, financing requirements or other payments.
A fund may hold investments that can be sold only over an extended period or only at a substantial discount during stressed markets. If investor redemptions or other cash requirements occur before those positions can be liquidated efficiently, the manager may be forced to sell the most liquid assets first, obtain additional financing or restrict redemptions. This can change the composition and risk characteristics of the remaining portfolio.
Liquidity risk is therefore closely related to market and credit risk. When positions cannot be reduced or closed in a timely manner, the fund remains exposed to adverse price movements or deterioration in the credit quality of its investments. Forced sales can also increase realized losses where market depth is insufficient to absorb the required transaction size.
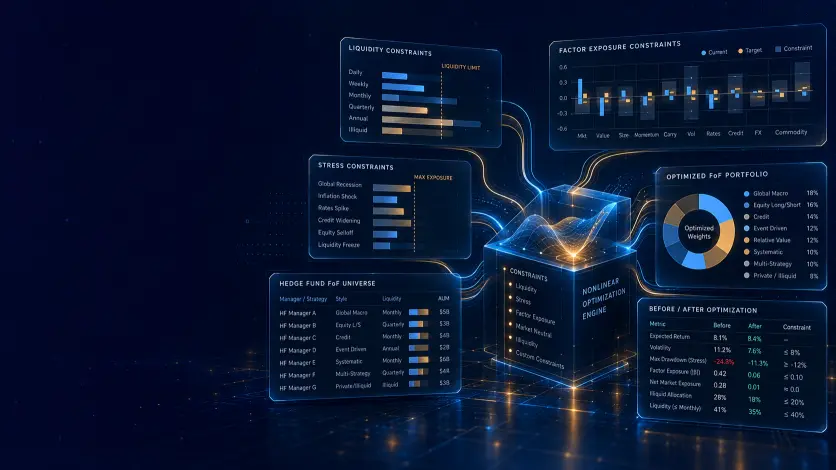
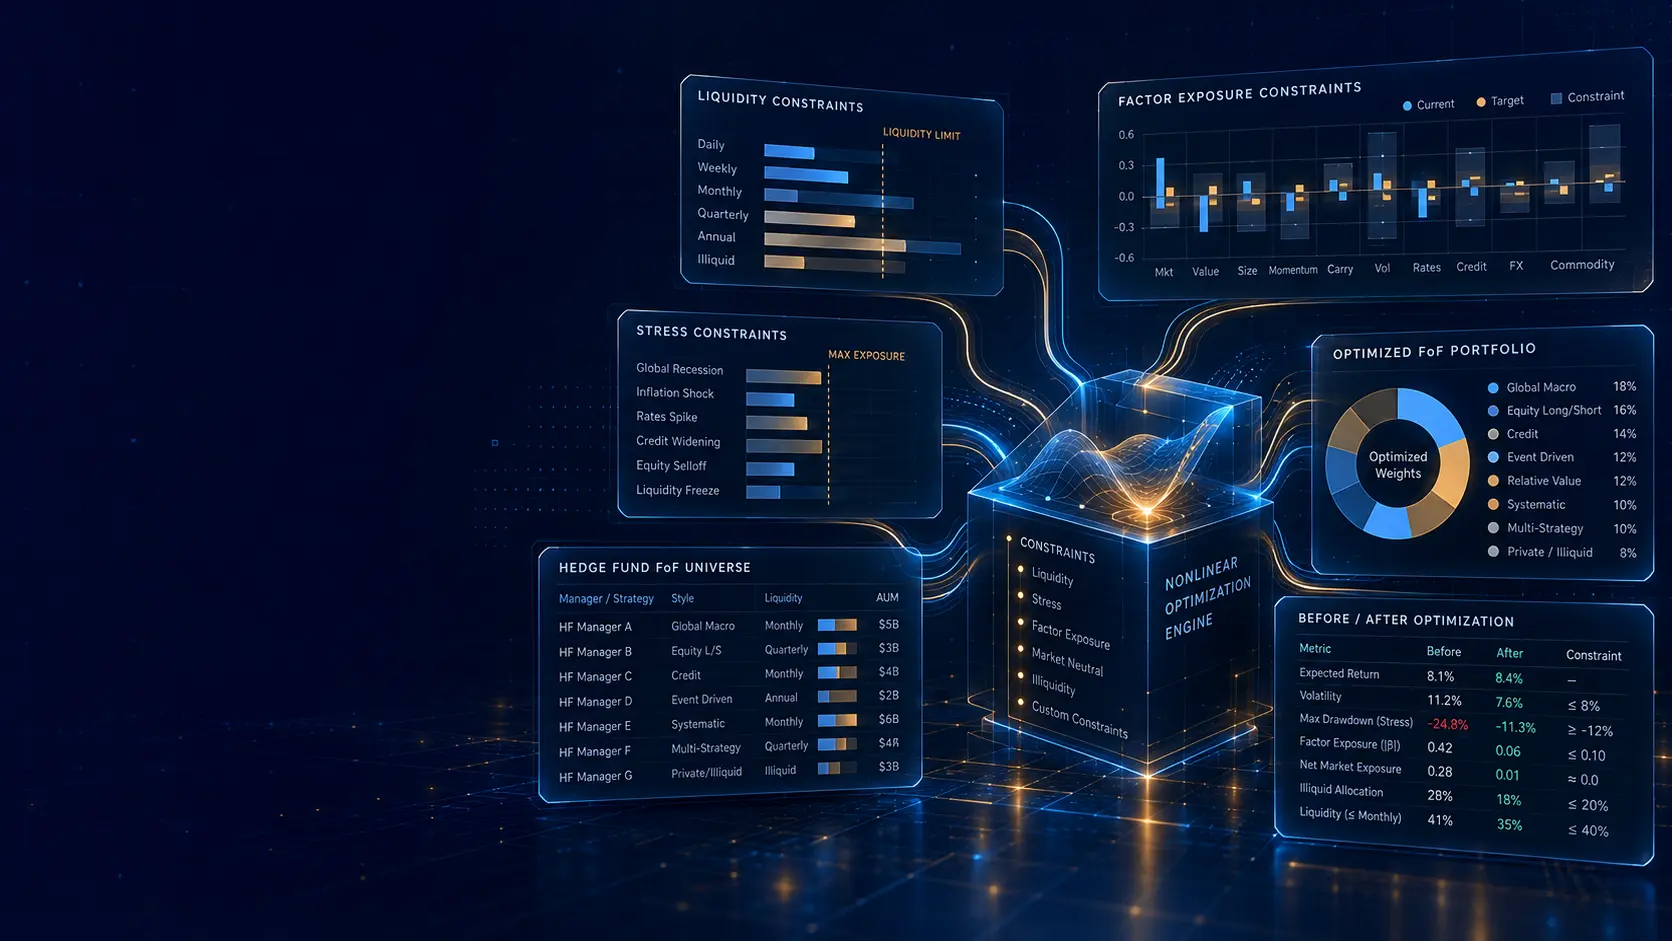
For a fund of hedge funds, liquidity analysis must also consider the redemption terms of the underlying funds. Notice periods, lock-ups, redemption frequency, gates and other restrictions determine how quickly capital can be returned. A portfolio may appear diversified by manager or strategy while still having a significant concentration of assets subject to similar redemption constraints.
Liquidity risk should therefore be assessed from both sides of the balance sheet: the expected liquidity of portfolio assets and the timing of cash obligations. The objective is to determine whether the fund can meet foreseeable liquidity requirements without materially changing the portfolio or realizing losses caused primarily by the need to raise cash.