ABC Quant ABC Quant
  • Home
  • Products
    • Risk Shell
    • Risk Shell AI
    • FoF Manager
    • Financial Data
    • Risk Shell Editions
      • Editions & Configurations
      • Institutional Investors / FoF
      • Family Offices
      • Due Diligence Managers
      • Hedge Fund Marketers
      • Traditional Managers
      • Research Houses
    • Risk Shell Components
      • Risk Shell AI
      • Macroeconomic Scenario Screening™
      • Asset & Manager Selection
      • Peer Group Analysis
      • FlexiRank
      • Factor Analysis
      • Stress Testing
      • Portfolio Construction
      • Portfolio Optimization
      • Portfolio What-If
      • Private Equity
      • Holdings-Based Analysis
      • CRM & Document Manager
      • Index Builder
      • Custom Assets
      • Report Builder
      • All Risk Shell Modules
    • FoF Manager Components
      • Liquidity Analysis
      • Limit Control
      • Strategy Classification
      • Exposure Analysis
      • Transactions
      • Transaction Audit Trail
      • Portfolio Blotter
      • Class Manager
      • Cash Projection
    • Financial Data
      • Data Coverage
      • Data Feeds
      • Custom Databases
      • Database Integration
    • Platform Tools
      • Custom Assets
      • Report Builder
      • Index Builder
      • CRM & Document Manager
  • Services
    • Shadow Accounting
    • Training & Tutorials
      • Risk Shell Training
      • Tutorials
    • Family Office
      • Family Office Webinars
      • SFO & MFO Programs
    • Custom Development
      • On-Demand Programs
      • Database Integration
      • Custom Deployment
    • Investment Research
      • Research On-demand
      • Research Programs
      • Fund Risk Assessment
      • Portfolio Risk Assessment
      • Due Diligence
      • Portfolio Construction
      • Portfolio Optimization
      • Style Analysis
      • Strategy Enhancement
  • About
    • About ABC Quant
    • Our Clients
    • Available Positions
    • Why Join Us
  • Resources
    • Case Studies
    • Knowledge Base
    • FAQs
    • News and Insights
    • Blog
    • Risk Management
    • Asset Allocation
    • Due Diligence
  • Webinars
    • Webinars This Month
    • Risk Shell Introduction
    • Family Offices
    • Portfolio Construction
    • FoF Risk Management
    • FoF Shadow Accounting
  • Search

Demo Request


  Mail is not sent.   Your email has been sent.
ABC Quant ABC Quant
  • Home
  • Products

    PRODUCT LINES

    • Risk Shell
    • Risk Shell AI
    • FoF Manager
    • Financial Data
    • Risk Shell Editions
    • Editions & Configurations
    • Institutional Investors / FoF
    • Family Offices
    • Due Diligence Managers
    • Hedge Fund Marketers
    • Traditional Managers
    • Research Houses

    RISK SHELL

    • Macroeconomic Scenario Screening™
    • Asset & Manager Selection
    • Peer Group Analysis
    • FlexiRank
    • Factor Analysis
    • Stress Testing
    • Portfolio Construction
    • Portfolio Optimization
    • Portfolio What-If
    • Private Equity
    • Holdings-Based Analysis
    • All Risk Shell Modules

    FoF Manager

    • Liquidity Analysis
    • Limit Control
    • Strategy Classification
    • Exposure Analysis
    • Transactions
    • Transaction Audit Trail
    • Portfolio Blotter
    • Class Manager
    • Cash Projection

    FINANCIAL DATA

    • Data Coverage
    • Data Feeds
    • Custom Databases
    • Database Integration
    • Platform Tools
    • Custom Assets
    • Report Builder
    • Index Builder
    • CRM & Document Manager
  • Services

    ACCOUNTING

    • Shadow Accounting
    • Training & Tutorials
    • Risk Shell Training
    • Tutorials

    INVESTMENT RESEARCH

    • Research On-demand
    • Research Programs
    • Fund Risk Assessment
    • Style Analysis
    • Strategy Enhancement

    OUTSOURCED CIO

    • Portfolio Risk Assessment
    • Due Diligence
    • Portfolio Construction
    • Portfolio Optimization

    DEVELOPMENT

    • On-Demand Programs
    • Database Integration
    • Custom Deployment
  • About

    OUR COMPANY

    • About ABC Quant
    • Our Clients

    CAREERS

    • Available Positions
    • Why Join Us
  • Resources

    INSIGHTS

    • News and Insights
    • Blog
    • Risk Management
    • Asset Allocation
    • Due Diligence

    RESOURCES

    • Case Studies
    • Knowledge Base
    • FAQs
  • Webinars

    WEBINARS

    • Webinars This Month
    • Risk Shell Introduction
    • Family Offices
    • Portfolio Construction
    • FoF Risk Management
    • FoF Shadow Accounting

    COMING WEBINAR

    Master and Feeder Portfolios


    Discover the capabilities of Risk Shell in advanced portfolio management by joining our upcoming webinar.


    04 Nov 2026
    09:00AM - 10:00AM
    Master and Feeder Portfolios
  • Search

Alternative Investment Management Software

Risk Shell

Institutional portfolio management, risk analytics and portfolio construction for alternative and multi-asset portfolios.

Integrated investment data, stress testing, portfolio optimization, alternative investment analytics and shadow accounting within one platform.

Request a Demonstration Explore Risk Shell
FoF Manager hero
FoF Manager

Shadow Accounting for Alternative Portfolios

Manage hedge funds, private equity and multi-asset portfolios with liquidity controls, custom classifications and flexible historical accounting.

35+ hedge fund liquidity settings
Explore FoF Manager
Optimization hero
Portfolio Optimization

Nonlinear Portfolio Optimization

Construct hedge fund-of-funds and multi-asset portfolios with stress-test, factor-exposure, liquidity and other user-defined constraints.

Custom Constraints for market-neutral and risk-controlled portfolio construction
Explore Portfolio Optimization
Risk Shell AI hero
Risk Shell AI

Natural-Language Access to Risk Shell

Use natural language to access investment research, risk analytics and portfolio workflows.

2.3B tokens in our in-house financial LLM
Explore Risk Shell AI
Macroeconomic Scenario Screening hero
Macroeconomic Scenario Screening

Select Assets for the Scenario You Define

Screen managers by risk and return targets under user-defined macroeconomic scenarios.

Trend Segmentation™ proprietary regime-analysis engine
Explore Scenario Screening
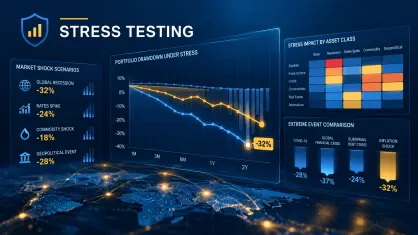
Peer-relative Stress Testing
Portfolio Stress Testing

Peer-Relative Stress Testing

Compare extreme-event outcomes with a relevant peer group.

500K+ live stress-tested instruments
Explore stress testing
  1. Home
  2. Products
  3. Risk Shell Components
  4. Asset & Manager Selection
  5. Screening
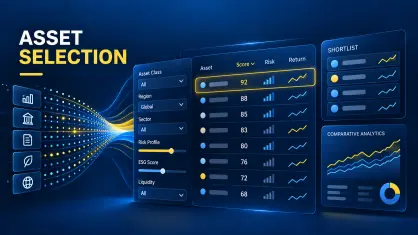
Quantitative Screening

Screen funds, managers and other assets using 100+ risk and performance measures over user-defined historical periods.

  • 100+ searchable risk and performance statistics
  • User-defined historical windows, fixed intervals and trailing periods
  • Variable confidence levels for applicable risk metrics
  • Upper, lower and bounded thresholds for individual screening criteria
Risk, Factor & Liquidity Filters

Screen hedge funds and other assets by factor exposures, liquidity profile and performance under historical stress events.

  • User-defined factor exposure filters
  • Liquidity profile and liquidity-based screening criteria
  • Historical stress-test results across extreme market events
  • Factor- and benchmark-relative metrics including alpha, beta, upside beta and downside beta
Manager & Fund Screening

Screen on descriptive fund and manager fields. Hundreds of searchable data points.

  • Strategy, substrategy, holding details and other descriptive fields
  • Dead and non-reporting funds
  • Vendor fields and custom user-defined manager fields
  • Qualitative and quantitative filters applied together
  • Tailored for hedge funds, fund of funds and multi-asset portfolios

Explore Screening Criteria

Click any segment to explore available filters and screening options.
 

Asset Screening Filters

Quantitative and qualitative filters run as one search, not as a screen followed by a manual cut. Risk statistics, factor and benchmark exposures, liquidity profile, stress-test results, strategy and reporting status are applied together, on a trailing period or a closed interval, across the selected hedge-fund and multi-asset universe.

  • Quantitative Screening

    Quantitative Screening

    Screen funds, managers and other assets using 100+ risk and performance measures over user-defined historical periods.

    • 100+ searchable risk and performance statistics
    • User-defined historical windows, fixed intervals and trailing periods
    • Variable confidence levels for applicable risk metrics
    • Upper, lower and bounded thresholds for individual screening criteria
  • Risk, Factor & Liquidity Filters

    Risk, Factor & Liquidity Filters

    Screen hedge funds and other assets by factor exposures, liquidity profile and performance under historical stress events.

    • User-defined factor exposure filters
    • Liquidity profile and liquidity-based screening criteria
    • Historical stress-test results across extreme market events
    • Factor- and benchmark-relative metrics including alpha, beta, upside beta and downside beta
  • Manager & Fund Screening

    Manager & Fund Screening

    Screen on descriptive fund and manager fields. Hundreds of searchable data points.

    • Strategy, substrategy, holding details and other descriptive fields
    • Dead and non-reporting funds
    • Vendor fields and custom user-defined manager fields
    • Qualitative and quantitative filters applied together
    • Tailored for hedge funds, fund of funds and multi-asset portfolios
  • Cross-Database Asset Search

    Cross-Database Asset Search

    Use risk-return filters to search assets acrows multiple databases

    • Global search across multiple vendor databases
    • Hedge funds and fund of funds
    • Long-only funds and CTAs
    • ETFs, closed-end and money market funds
    • Equities and other supported investment universes

Asset Selection FAQs

Can I combine quantitative and qualitative filters in Risk Shell?▼

Yes. Risk Shell allows complex searches that combine quantitative criteria with qualitative or descriptive fields. This makes it possible to narrow the search using characteristics such as asset type, strategy, classification, or other descriptive attributes together with numerical measures such as returns, volatility, liquidity, valuation, or risk statistics.

What is Factor Screening in Risk Shell?▼

Factor Screening identifies instruments with specified sensitivities, or betas, to selected economic factors, market indices, or benchmarks. It can be used to find assets with particular factor exposures and to support factor-based research, portfolio construction, and risk analysis.

Can I search for instruments based on their correlation or regression to another asset or benchmark?▼

Yes. Risk Shell provides regression-based search functionality that allows you to identify instruments within a specified correlation or regression range relative to a reference asset, index, or benchmark. This can be useful for finding instruments with similar, complementary, or specific market relationships.

Can I perform a quantitative search over a specific historical time period?▼

Yes. Risk Shell supports quantitative searches over defined historical periods, including both trailing and closed time intervals. This allows search criteria to be evaluated consistently over the period relevant to your analysis rather than relying only on current values.

Can I search using custom, user-defined data fields?▼

Yes. User-defined data fields can be included in Risk Shell searches in the same way as supported vendor data fields. This allows institutions to incorporate proprietary classifications, internal metrics, and other custom information into their screening criteria.

Are custom instruments included in Risk Shell searches?▼

Yes. Custom instruments and user-defined datasets can be organized as virtual databases within Risk Shell. They are integrated with vendor databases and can therefore be included in the same search and screening routines.

Can I screen funds and other investment instruments using quantitative criteria?▼

Yes. Risk Shell supports quantitative screening across a broad range of investment instruments and datasets. Depending on the available data, search criteria can include performance characteristics, risk measures, exposures, classifications, and other quantitative or descriptive fields.

Can I use risk and performance metrics as search criteria?▼

Yes. Risk Shell can use quantitative risk and performance measures as screening criteria. This allows users to search for instruments or funds according to characteristics such as historical performance, volatility, downside risk, tail-risk measures, and other available analytics.

Can I screen instruments by their exposure to market or economic factors?▼

Yes. Factor-based screening can be used to identify instruments according to their estimated sensitivities to selected market, economic, or benchmark factors. This provides a practical way to search for specific sources of systematic exposure rather than relying solely on asset-class or descriptive classifications.

Can I search for instruments with similar historical behaviour?▼

Yes. Risk Shell's quantitative search capabilities can be used to identify instruments with specified statistical relationships to a reference instrument or benchmark. Correlation, regression characteristics, factor sensitivities, and other available quantitative measures can help identify instruments with similar or contrasting historical behaviour.

Can I use multiple screening conditions in a single Risk Shell search?▼

Yes. Risk Shell is designed for multi-criteria searches, allowing users to combine several quantitative and descriptive conditions. Complex screening rules can therefore be used to narrow large instrument universes to a specific set of assets or funds matching the required characteristics.

Can Risk Shell search across multiple data sources?▼

Yes. Risk Shell can integrate data from supported vendor databases together with user-defined data and custom instruments. These datasets can be incorporated into the search environment, allowing screening criteria to be applied across a combined investment universe.

What can Risk Shell quantitative screening be used for?▼

Quantitative screening can support a wide range of institutional investment research tasks, including investment universe selection, manager and fund research, factor analysis, portfolio construction, benchmark-relative analysis, and identification of instruments with specific risk, return, correlation, or exposure characteristics.

Book Your Spot: Mastering Asset Selection

04 Nov 2026;
09:00AM - 10:00PM
Pros and cons of VaR
16 Nov 2026;
04:00PM - 05:00PM
Macroeconomic Scenario Screening
25 Nov 2026;
09:00AM - 10:00PM
Pros and cons of VaR
07 Dec 2026;
04:00PM - 05:00PM
Macroeconomic Scenario Screening
16 Dec 2026;
09:00AM - 10:00PM
Pros and cons of VaR

Risk Shell Components

Risk management and portfolio construction for alternative investments

Asset selection software for alternative investments

Asset Selection

Hundreds of quantitative and qualitative filters for building precise asset and investment manager screening criteria across alternative and multi-asset investment ...

Explore component
CRM and document manager for hedge funds

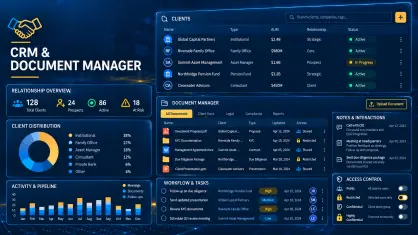
CRM & Document Manager

Document management and due diligence tools for alternative investments and multi-manager funds.

Explore component
Creating custom assets

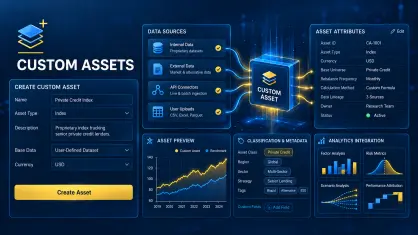
Custom Assets

Tools to create and maintain virtual databases of user-defined assets within the Risk Shell environment.

Explore component
Factor and attribution analysis

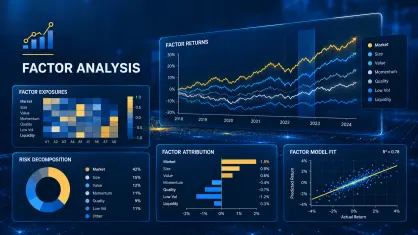
Factor Analysis

Multivariate Returns-Based and Holdings-Based Factor Analysis with Static and Dynamic Style Analysis for identifying the drivers of fund and portfolio returns, factor ...

Explore component
FlexiRank: user-defined risk statistics

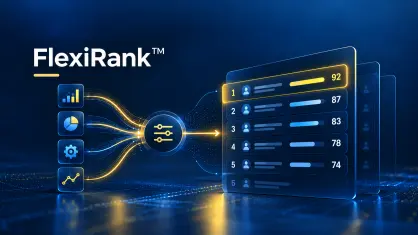
FlexiRank™

Asset ranking on user-defined synthetic risk statistics: several weighted measures combined into one rank, rather than a sort on a single conventional statistic.

Explore component
Holdings-based analysis

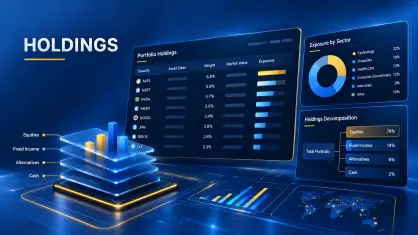
Holdings

Holdings-Based Analysis for hedge funds, funds of funds and multi-asset portfolios across equities, fixed income, commodities, derivatives and other asset classes.

Explore component
Custom financial indices

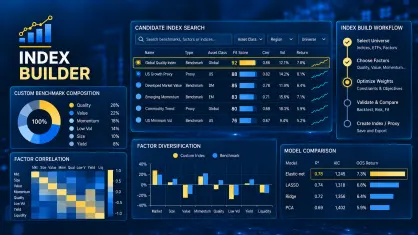
Index Builder

Advanced quantitative framework to create custom benchmarks and factor subsets that ensure the best fit for any asset.

Explore component
Reporting software for fund managers

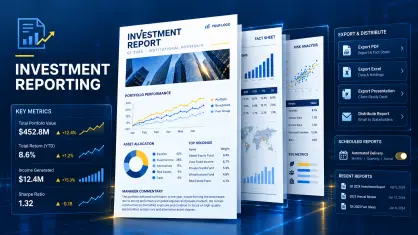
Investment Reporting

Report Builder delivers a flexible SaaS based investment reporting solution designed for fund managers and family offices.

Explore component

Macroeconomic Scenario ...

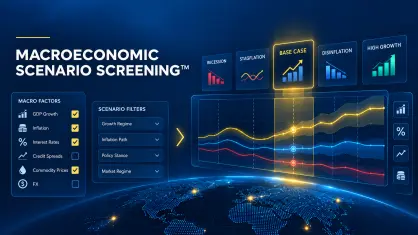
Macroeconomic Scenario Screening™

Macroeconomic Scenario Screening™ is Risk Shell's proprietary framework for selecting investments according to their historical ...

Explore component
Peer group analysis software

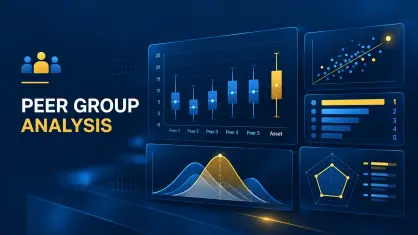
Peer Group Analysis

Multi-statistic and box-plot peer group analysis for hedge funds, fund of funds and multi-asset portfolios, with estimated stress-event losses used as peer statistics.

Explore component
Portfolio construction software for multi-asset funds

Portfolio Construction

Portfolio construction software for fund of funds and multi-manager portfolios, combining risk budgeting, diversification and correlation analysis, marginal risk ...

Explore component
Portfolio optimization software

Portfolio Optimization

Optimization of multi-manager funds, fund of funds and multi-asset portfolios across a broad range of objective functions.

Explore component
Portfolio what-if analysis

Portfolio What-If

Portfolio What-If Analysis to create and analyze hypothetical portfolios based on actual investment portfolios.

Explore component
Private equity software

Private Equity

Private equity risk management and portfolio management software, a part of the Risk Shell alternative investment platform.

Explore component

Risk Shell AI

Natural-Language Interface for Risk Shell

An AI assistance layer integrated with Risk Shell, combining natural-language interaction with platform knowledge, portfolio ...

Explore component
Stress testing of hedge fund of funds and multi-asset portfolios

Stress Testing

Historical and factor-based stress testing for hedge funds, fund of funds and multi-asset portfolios, with predictive scenario analysis and a continuously updated ...

Explore component
ABC Quant logo
1202 N. Market Street
Wilmington, DE 19801
  • +1-(302) 396-6855
  • hidden link
  • Risk Shell
  • FoF Manager
  • Data
  • RESEARCH
  • About Us
  • Contact Us
  • Clients
  • Case Studies
  • Blog
  • Webinars
  • Support
  • FAQs
  • T&C
  • Privacy Notice
  • Disclaimer
  • Cookie settings
Copyright © 2026 ABC Quant. All Rights Reserved.