






[yt_lightbox yt_title="Omega Ratio" align="left" type="none" style="" src="/images/content/articles/OmegaRatio2.jpg" video_addr="" width="30%" height="30%" lightbox="yes" description="Omega Ratio" ]
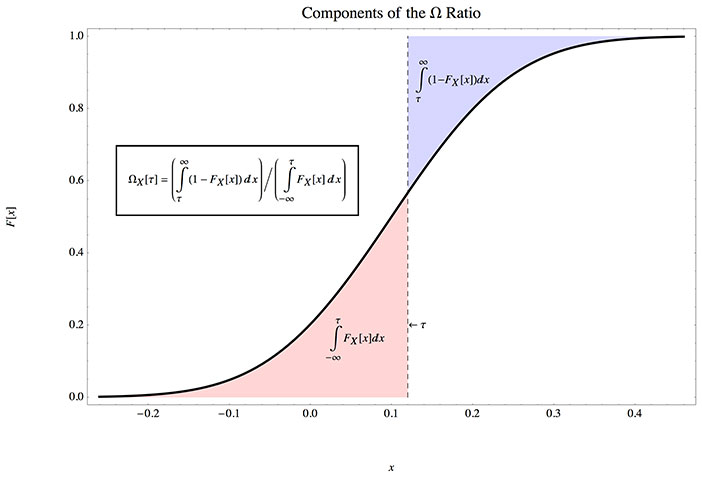
Introduced in 2002 by Keating and Shadwick, the Omega ratio is a relatively new addition in a hedge fund metrics library. By employing higher moments and taking into account actual shapes of distributions of returns, this measure is well-suited for hedge fund risk assessment, because of the non-normality of their distributions.
What are the Omega and Kappa ratios?
The Omega ratio is the ratio of probability weighted gains and losses about a specified return threshold. As shown in the diagram, it involves partitioning returns into loss and gain above and below a return threshold and then dividing the corresponding gain area into the loss area. In turn, the Kappa ratio presents a generalization of higher moments (n) relative to a return threshold:

It is easy to show that the Omega ratio is expressed via the Kappa ratio of the first moment, i.e.

The commonly used Sortino ratio is also the equivalent of the second moment Kappa ratio i.e.

The Omega and Kappa risk statistics are included in the following Risk Shell components and modules:
- Screening filters
- Risk engine
- Risk-return profile analysis (2D and 3D)
- Peer Group Analysis, as selectable statistics
- Side-by-Side – comparative analysis statistics
- Portfolio Optimization, the Omega statistic is one of the objective functions available
- Optimization Batch Backtesting
-
JOIN OUR WEBINAR
Omega Optimization In Practice: tips and techniques for alternative investment portfolios.
The ABC Quant video materials and tutorials available on or through this website are protected by copyright and international intellectual property laws. Your right to view the ABC Quant video materials and tutorials is strictly on invitation only basis. You may not download, distribute or otherwise publish, copy, transmit, modify, reverse engineer, or sublicense any video content and/or tutorials available on or through this website.