





Alternative Investment Management Software

Risk Shell

Institutional portfolio management, risk analytics and portfolio construction for alternative and multi-asset portfolios.

Integrated investment data, stress testing, portfolio optimization, alternative investment analytics and shadow accounting within one platform.

FoF Manager hero
FoF Manager

Shadow Accounting for Alternative Portfolios

Manage hedge funds, private equity and multi-asset portfolios with liquidity controls, custom classifications and flexible historical accounting.

35+ hedge fund liquidity settings
Explore FoF Manager
Optimization hero
Portfolio Optimization

Nonlinear Portfolio Optimization

Construct hedge fund-of-funds and multi-asset portfolios with stress-test, factor-exposure, liquidity and other user-defined constraints.

Custom Constraints for market-neutral and risk-controlled portfolio construction
Explore Portfolio Optimization
Risk Shell AI hero
Risk Shell AI

Natural-Language Access to Risk Shell

Use natural language to access investment research, risk analytics and portfolio workflows.

2.3B tokens in our in-house financial LLM
Explore Risk Shell AI
Macroeconomic Scenario Screening hero
Macroeconomic Scenario Screening

Select Assets for the Scenario You Define

Screen managers by risk and return targets under user-defined macroeconomic scenarios.

Trend Segmentation™ proprietary regime-analysis engine
Explore Scenario Screening
Peer-relative Stress Testing
Portfolio Stress Testing

Peer-Relative Stress Testing

Compare extreme-event outcomes with a relevant peer group.

500K+ live stress-tested instruments
Explore stress testing

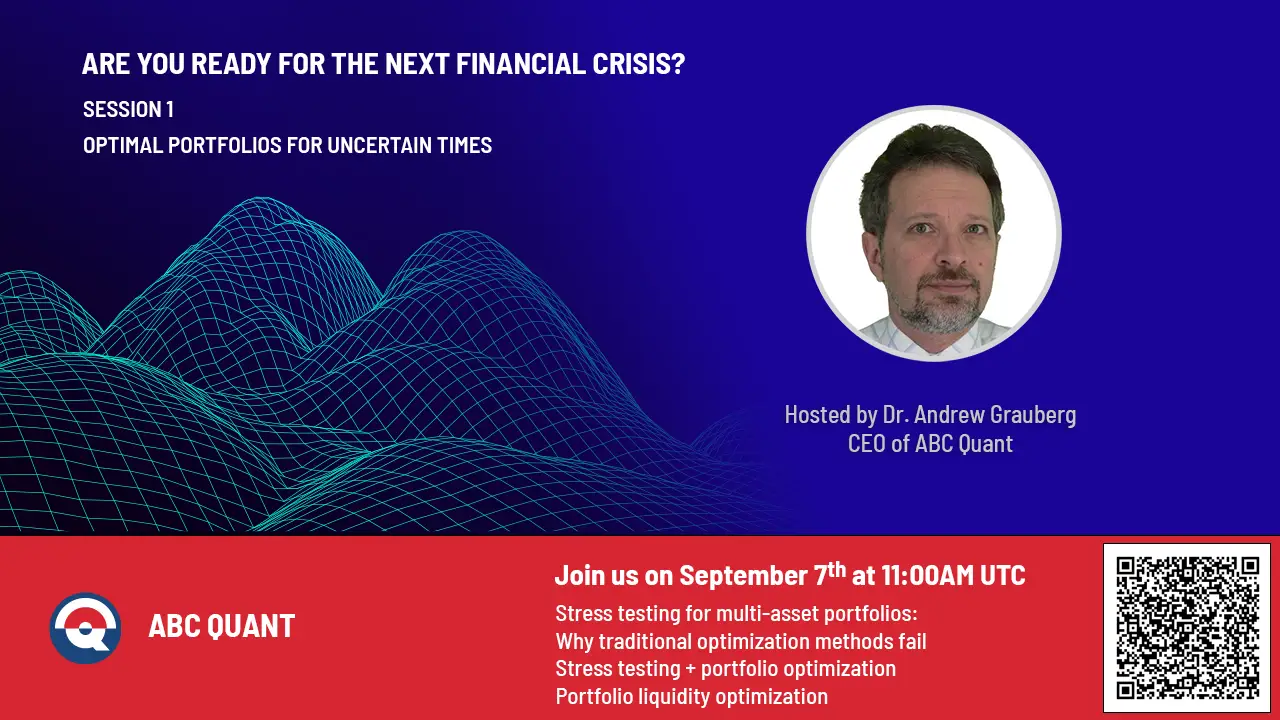
Special event: portfolio optimization for the next crisis

Special Event: Portfolio Optimization for Extreme Market Conditions

August 17, 2023 - Wilmington, DE - In response to the growing demand for constructing market-neutral portfolios resilient to extreme market shocks, ABC Quant presents proprietary models of combining of portfolio optimization and stress testing frameworks, which used to be available exclusively to Risk Shell clients. For the first time in the industry, we've integrated stress test data into portfolio optimization models—empowering users to construct portfolios that not only optimize risk and return but also withstand macroeconomic extreme events.

AGENDA

  • Why traditional optimization methods fail.
  • Non-linear portfolio optimization.
  • Beta constraints (market factor exposures) for constructing market-neutral portfolios.
  • Integrating Stress Testing with Portfolio Optimization.
  • Market-neutral portfolios (hedge fund of funds and multi-asset): defining the optimization model.
  • Portfolio Liquidity and Exposure Optimization.


WHEN

September 7, 2023, 11:00AM UTC | 4:30AM IST | 1:00PM CEST | 3:00PM GST.

POTENTIAL AUDIENCE

fund of funds investors, multi-asset portfolio manager, risk managers, quantitative research analysts, CIOs, advanced family offices, endowments. Free registration for professional, accredited or institutional investors only. Registrations submitted from public emails are not accepted.

The webinar agenda and a direct registration link.