






Special Event: Are Private Credit Funds Risky For Your Porfolio?
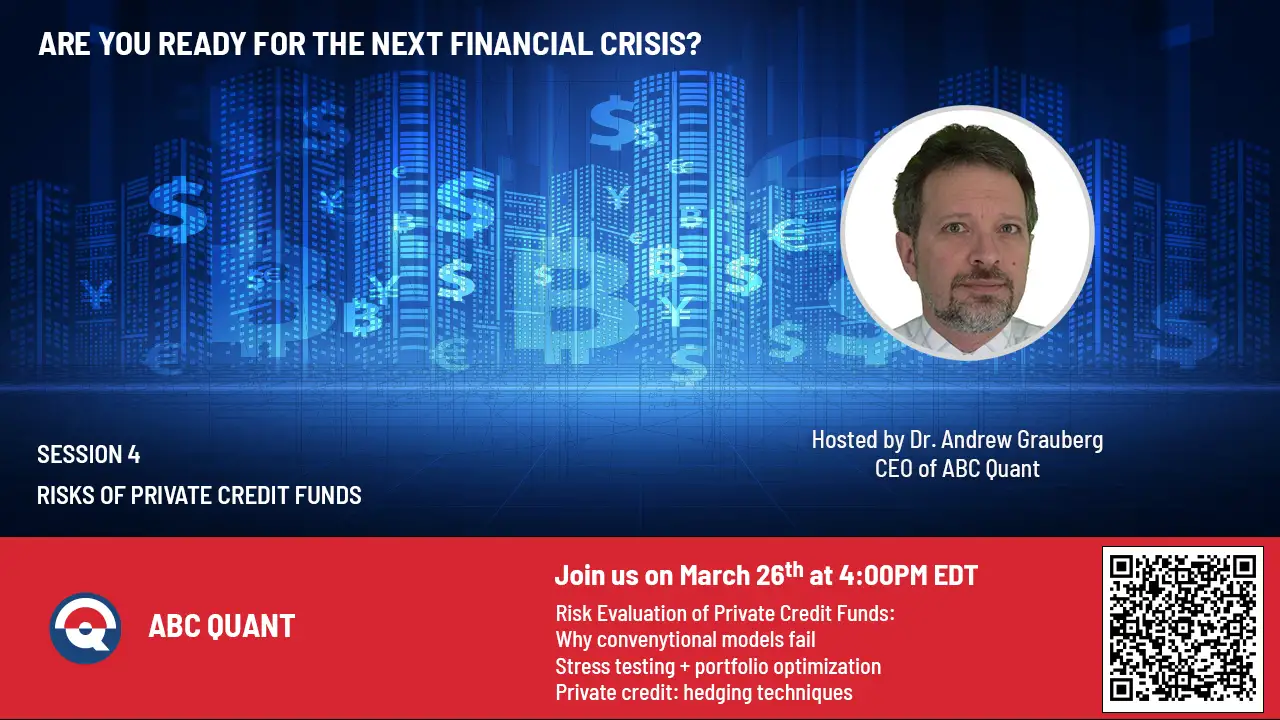
February 27, 2024 - Wilmington, DE - ABC Quant presents an exclusive event, the fourth webinar in the "Are you ready for the next financial crisis?" series. This session is dedicated to the ABC Quant's risk valuation frameworks of private credit funds.
AGENDA
Introduction to Private Credit
- Private credit vs. traditional bank lending and private equity.
- The structure of private credit.
- Evolution of private credit funds.
- Main investor categories in private credit instruments.
- Hedge fund databases: coverage of private credit funds.
Challenges of Private Credit Risk Assessment
- Credit risk assessment problems of non-rated instruments.
- Can we use conventional credit risk valuation methods?
- Stress testing of private credit: why bank stress testing frameworks fail.
Stress Testing of Private Credit Funds in Risk Shell
- Macroeconomic Scenario Screening for private credit instruments.
- Multi-factor models and stress testing.
- Extreme event and correlation stressing.
Integrating Stress Testing with Portfolio Optimization
- Why combining stress testing and optimization in a single framework.
- Basics of factor-based stress testing.
- Stress constraints in optimization models.
- Explaining factor models and the ways of selecting factor pre-sets..
- Introducing stress test statistics.
- Filtering assets based on stress test statistics
- Multi-statistic Peer Group Analysis with stress test metrics.
- Introducing Multi-statistic Ranking Framework.
- Integrating Stress Testing with Portfolio Optimization.
WHEN
March 26, 2024, 1:00PM PDT | 4:00PM EDT | 8:00PM GMT | 9:00PM CET.
POTENTIAL AUDIENCE
Institutional portfolio managers, hedge FoF and multi-asset portfolio managers, risk managers, CIOs, advanced family offices. endowments. Free registration for professional, accredited or institutional investors only. Registrations submitted from public emails are not accepted.
Linkedin registration page.
The direct registration link.