
Training Curriculum
Risk Measurement & Alternative Investments
- Value-at-Risk and tail-risk measures
- Drawdown and downside-risk analysis
- Distribution characteristics of hedge fund returns
- Autocorrelation and serial dependence
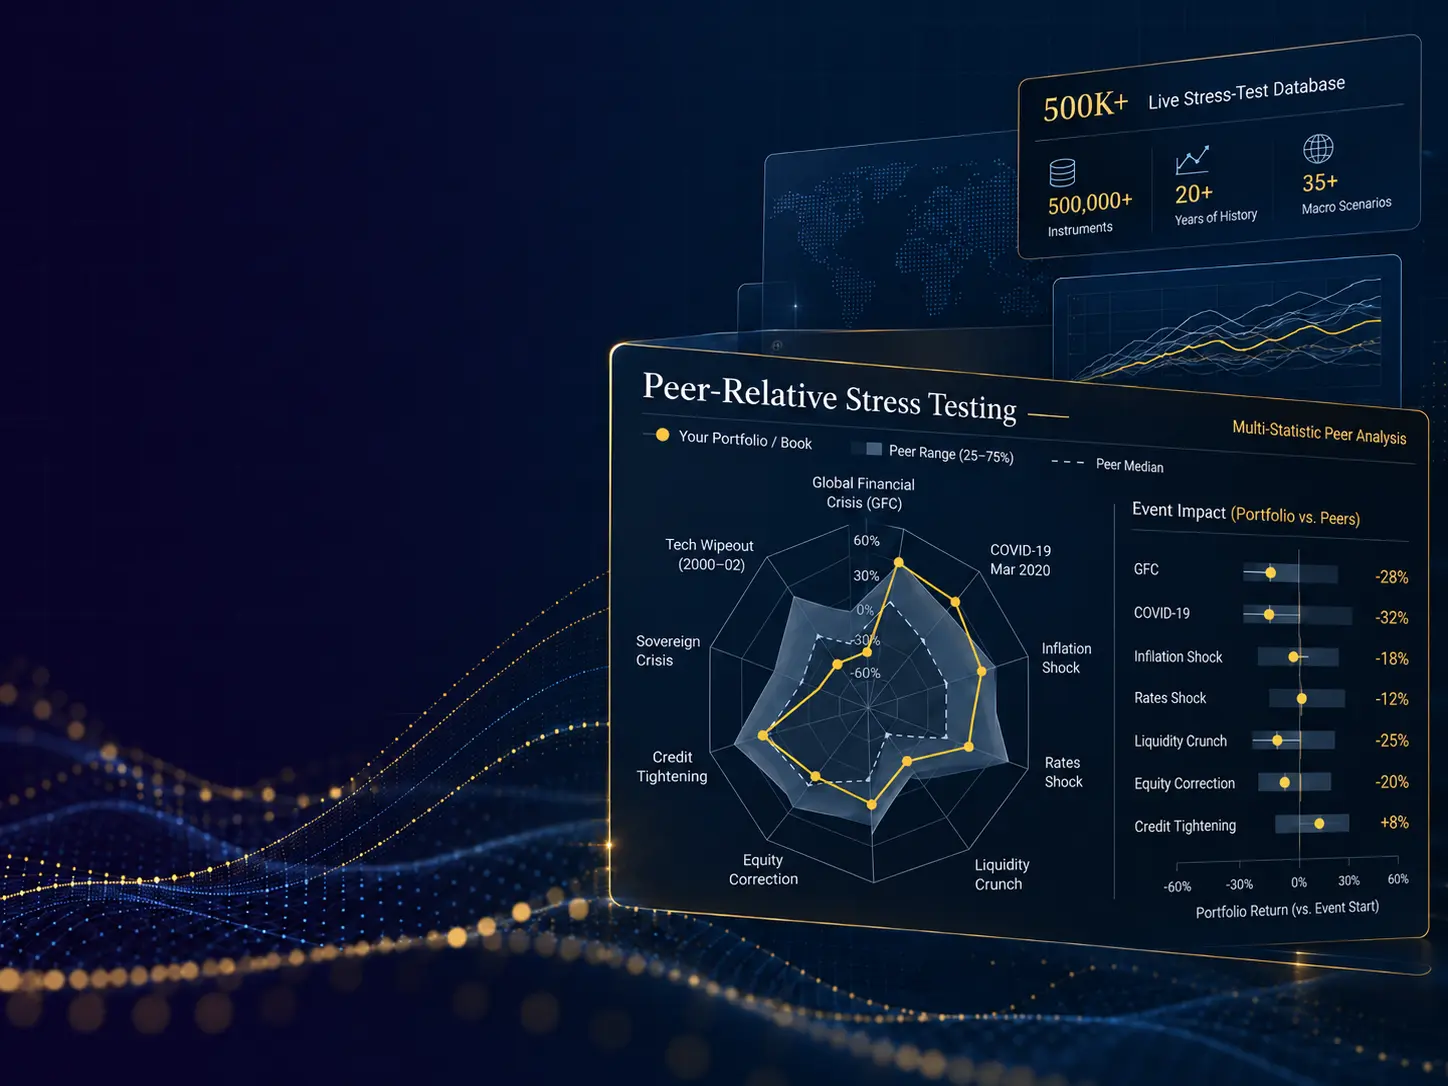
- Peer-relative risk assessment
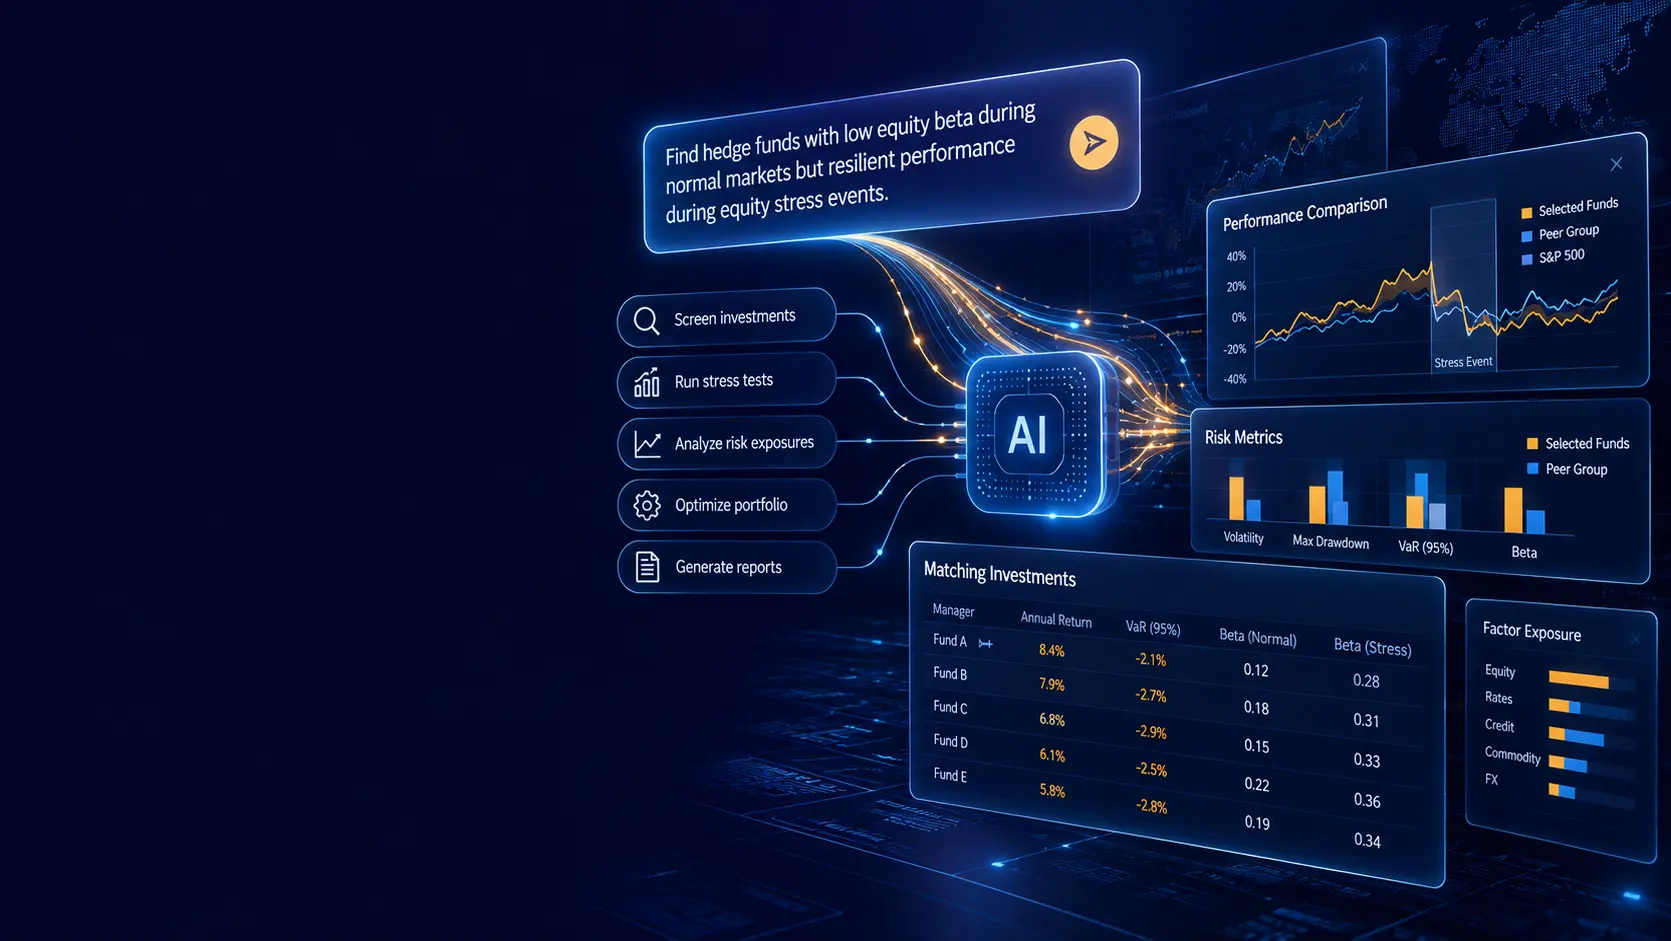
- Risk measures used in manager screening
Factor & Style Analysis
- Static and Dynamic Attribution Analysis
- LASSO, PCA, AIC and Ridge factor models
- Kalman-filter models
- Factor selection and model diagnostics
- Style drift and Trend Segmentation™
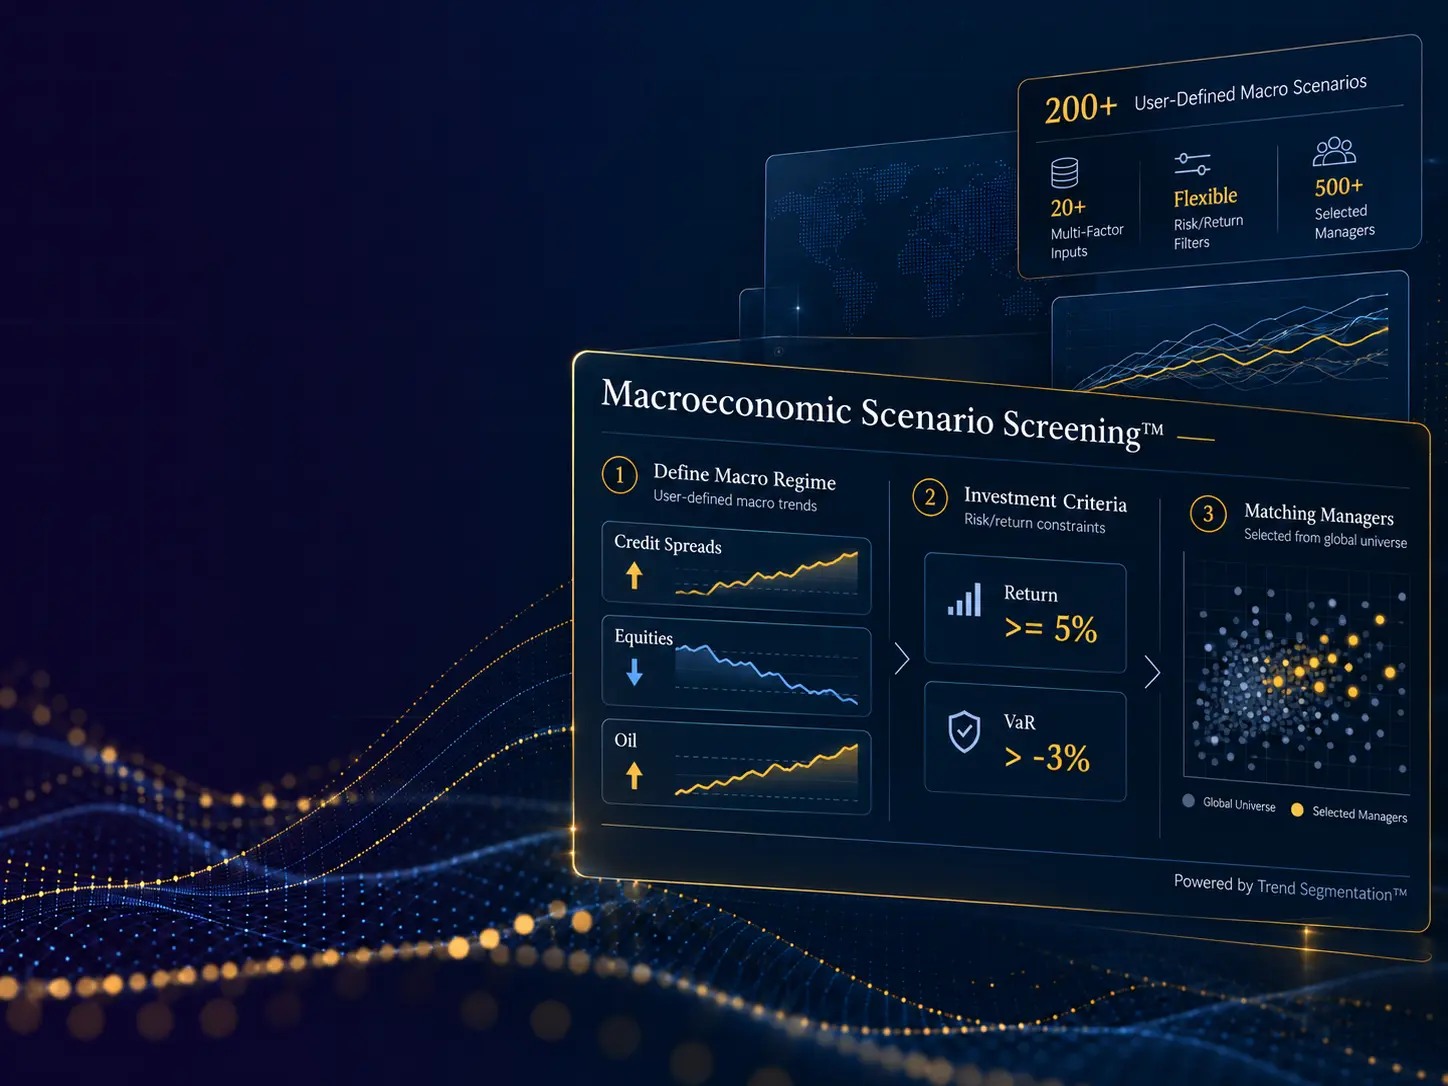
- Macroeconomic Scenario Screening™
Portfolio Construction & Optimization
- Portfolio construction workflow
- Marginal risk contribution and diversification
- Risk Budgeting and Equal Risk Contribution
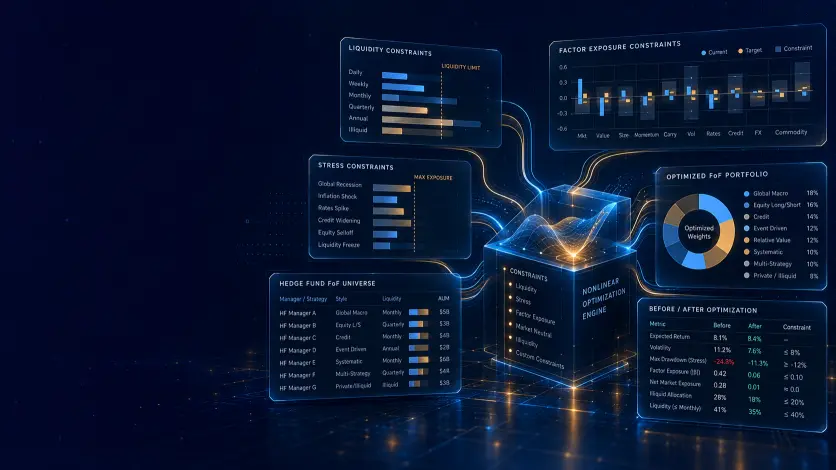
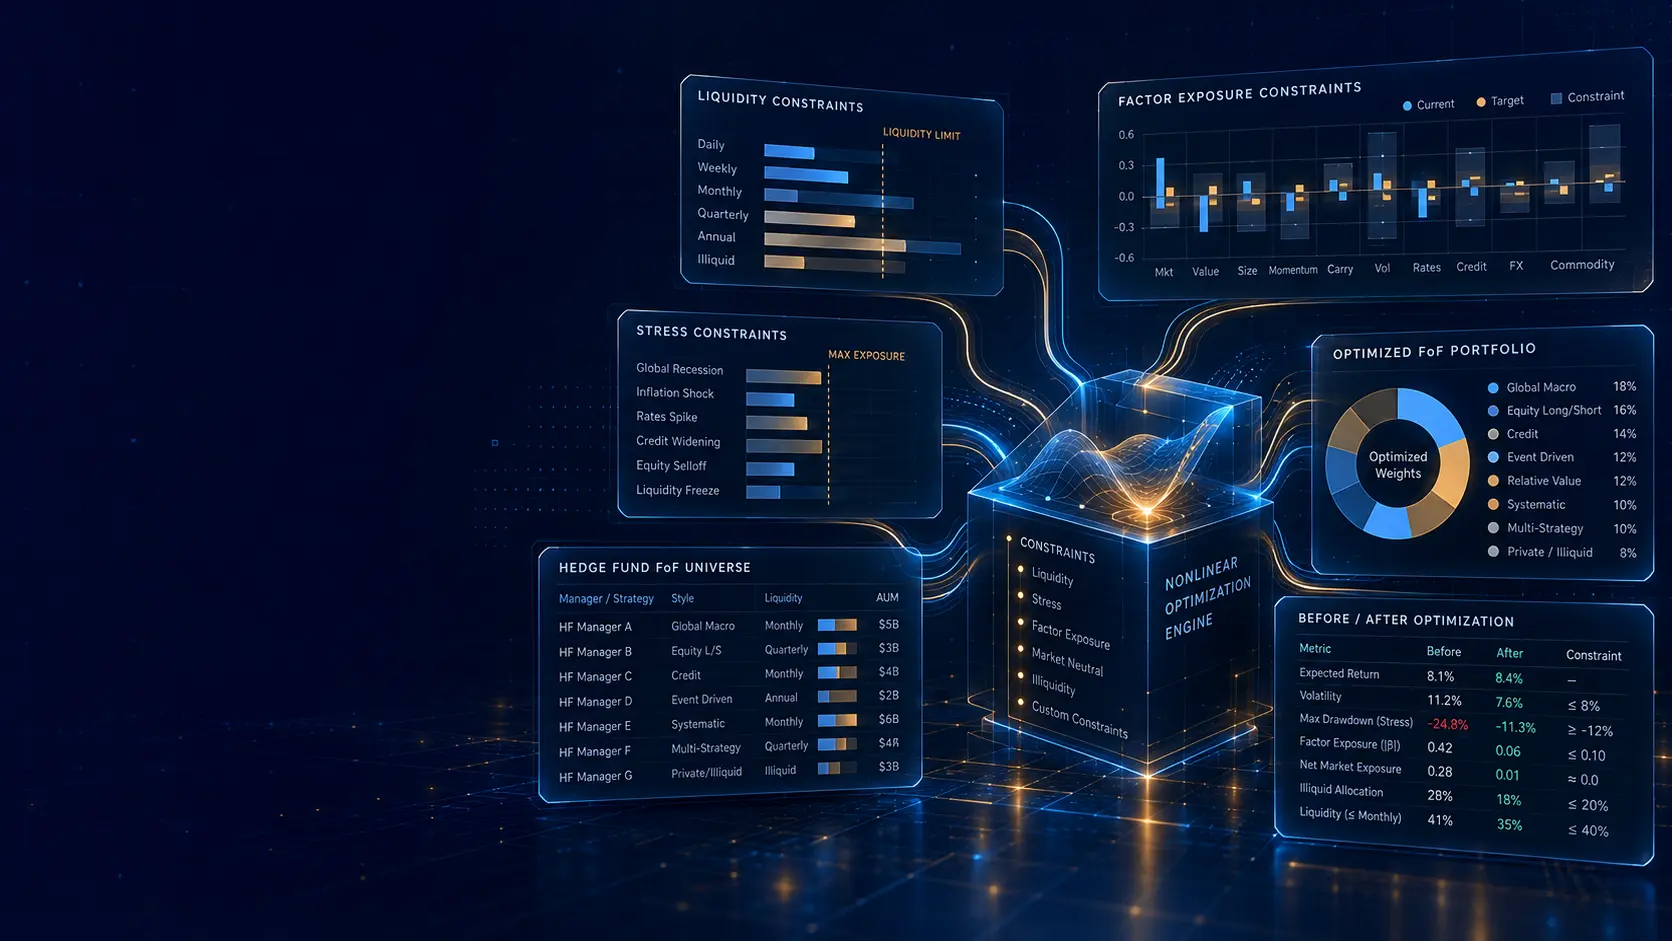
- Nonlinear Portfolio Optimization
- Factor, stress-test and liquidity constraints
- Optimization backtesting and rebalancing
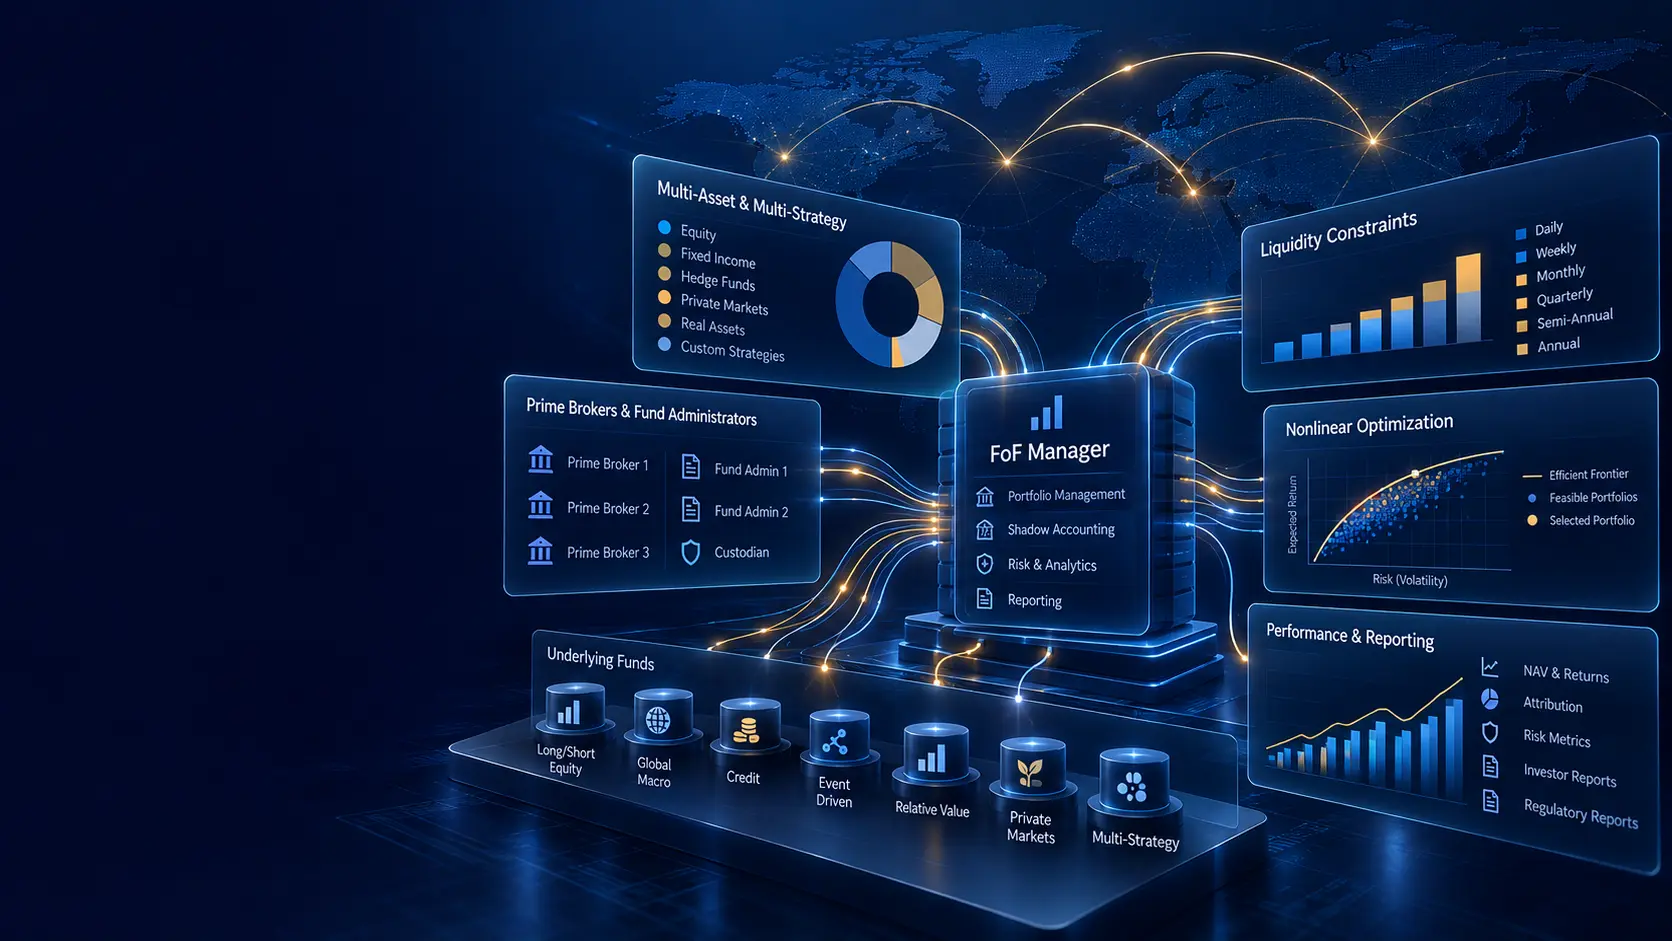
FoF Manager & Portfolio Management
- Portfolio exposure analysis
- Liquidity profile and cash-flow projections
- Portfolio limit control
- Transaction processing
- Fund classes and master-feeder structures
- Shadow accounting workflows