hedge fund problems

  • Biases in fund databases present another serious problem originated from the following reasons. First, databases include only a part of the whole hedge find population that varies from 30 percent to 50 percent. Second, some biases are derived from the peculiar terms of counting hedge funds and their respective returns.

  • Based on the Markowitz’s mean-variance model, the Capital Asset Pricing Model (CAPM) inherits all the shortcomings of the latter in addition to its own assumptions that makes it hardly applicable for hedge funds and non-linear assets. While the CAPM still emerges as the most commonly used approach for both institutional and private investors, using it for hedge funds could be disastrous.

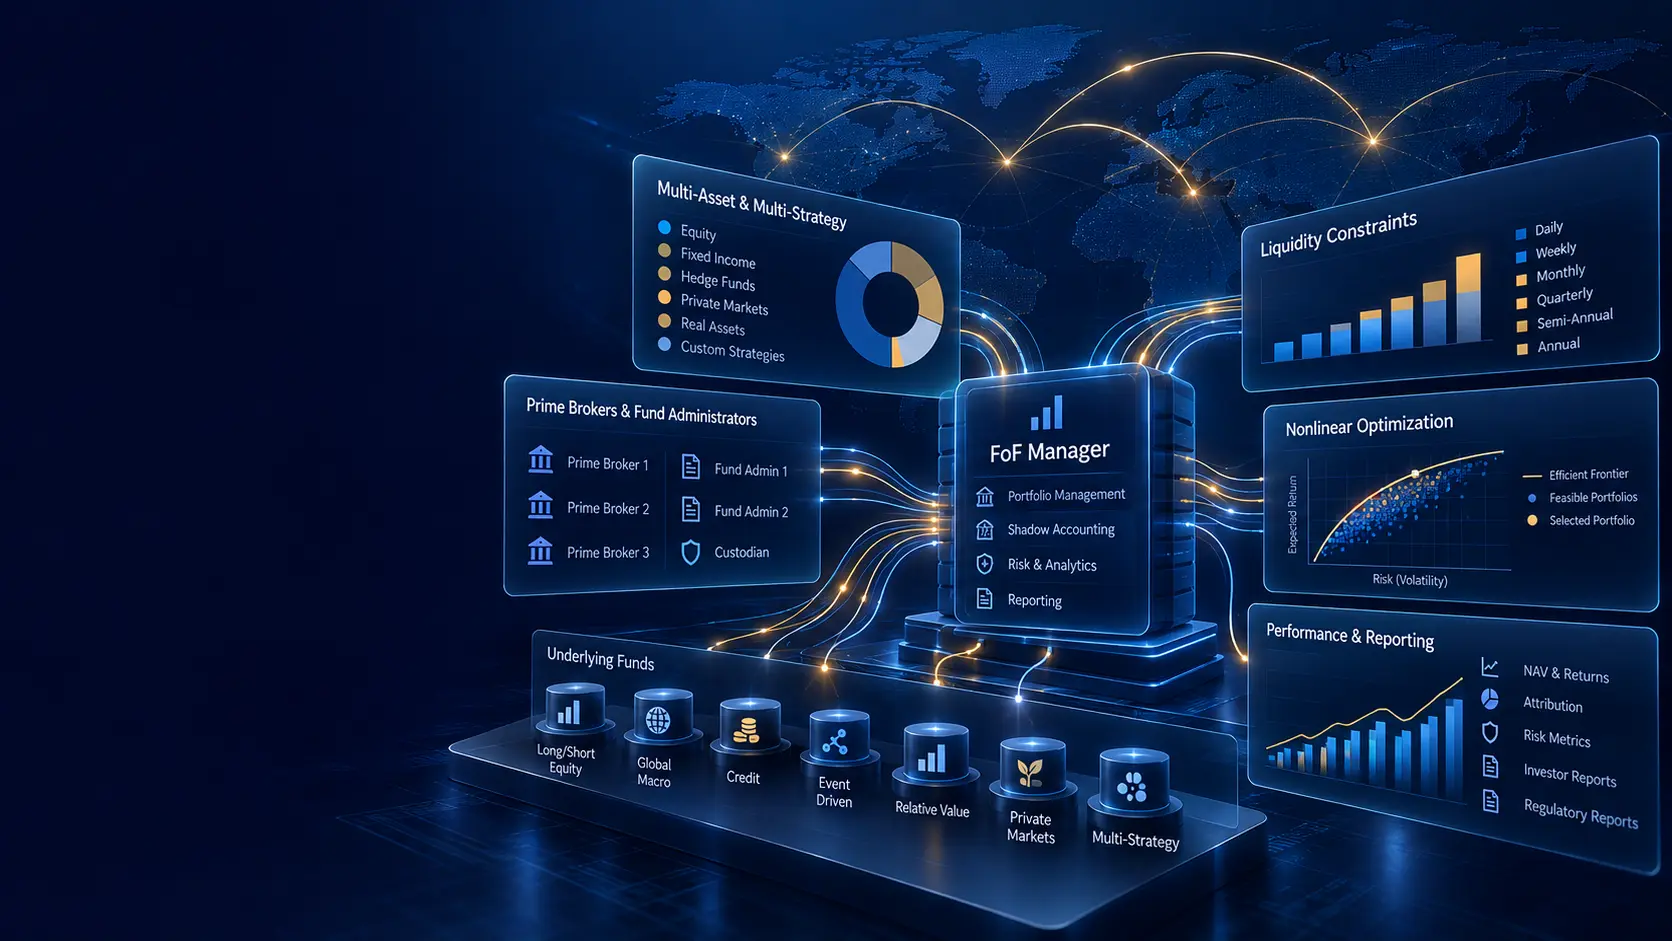
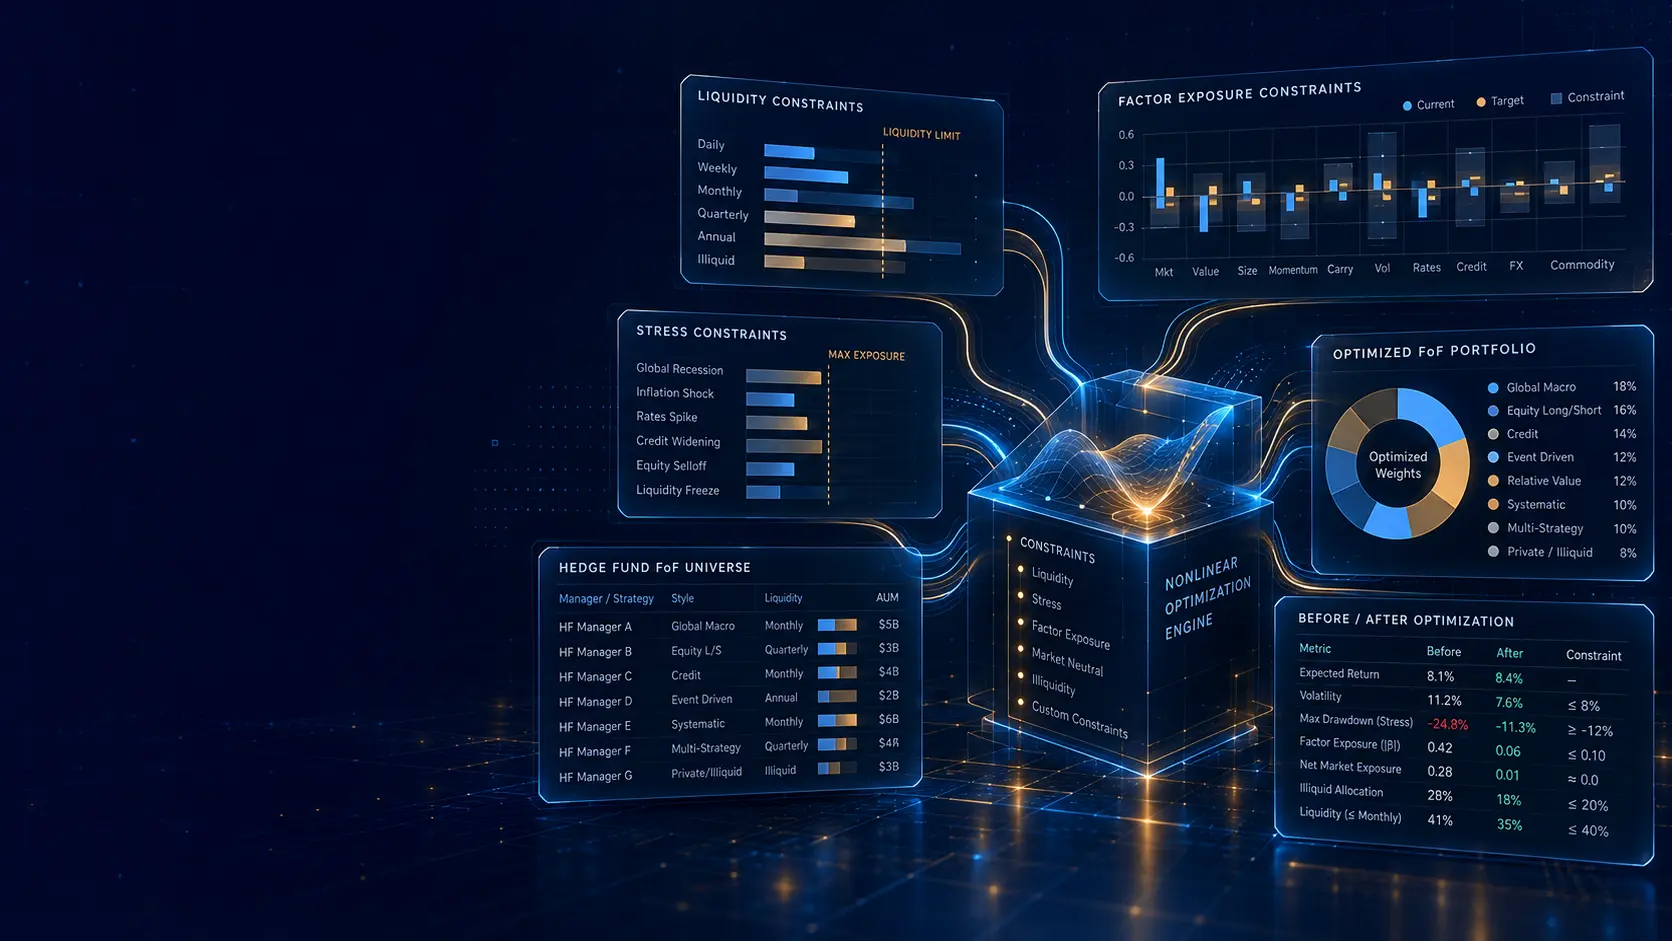
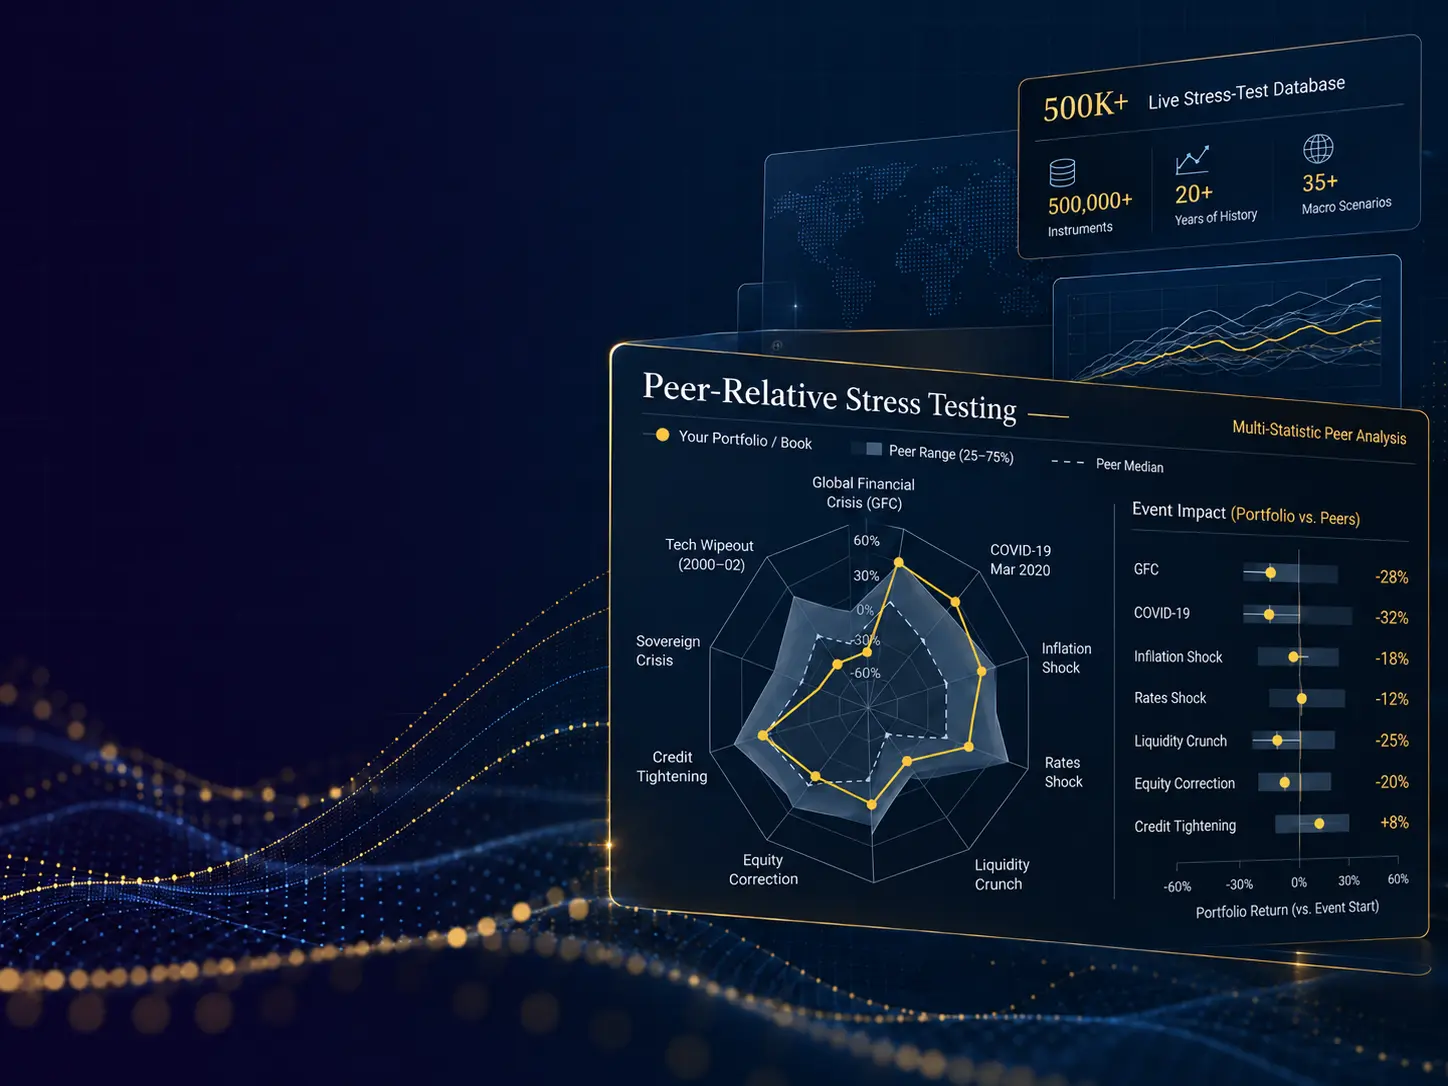
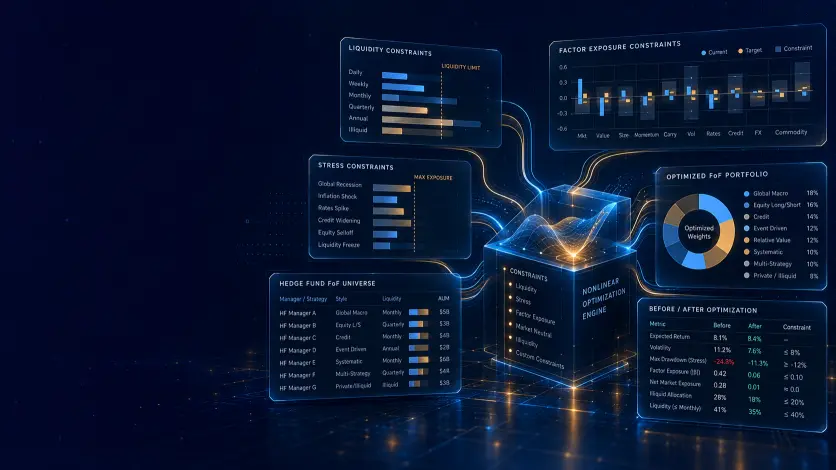
  • Typical mistakes in hedge fund valuation and risk assessment arise from neglecting their unique properties: non-normal return distributions, low transparency, bizzarre hedge fund indices, inapplicability of the mean-variance methodology, numerous data biases etc. The distinct hedge fund valuation and risk management problems can be outlined as follows...

  • Is Dubai witnessing a notable surge in hedge funds relocating or establishing their base in the region? What are the best hedge funds operating in Dubai? How do these hedge funds stack up against their peers in the emerging market strategies? Let's find out.

  • The Markowitz’s mean-variance methodology is hardly applicable for hedge fund risk assessment. Since its introduction, the mean-variance methodology became the primary tool for portfolio diversification used by the majority of pension and mutual funds globally. However, despite its popularity, the mean-variance approach suffers important drawbacks...

  • Value at Risk (VaR) is widely used but has key limitations, including sensitivity to estimation methods, lack of coherent risk aggregation, and inability to capture extreme tail losses. These issues have motivated alternatives such as Conditional Value at Risk (CVaR).

  • Is the Sortino Ratio an effective comparative risk measure? Explore its nuances, advantages, and limitations in our latest article. Discover insights from a comprehensive study and learn about Risk Shell's innovative FlexiRank framework, offering a nuanced approach to asset comparison.

  • The hardest aspect about hedge fund properties is to understand that they present an entirely distinct category of financial instruments, therefore, deploying a traditional methodology commonly used for stocks and bonds, will lead to the unexpected and most questionable results.