
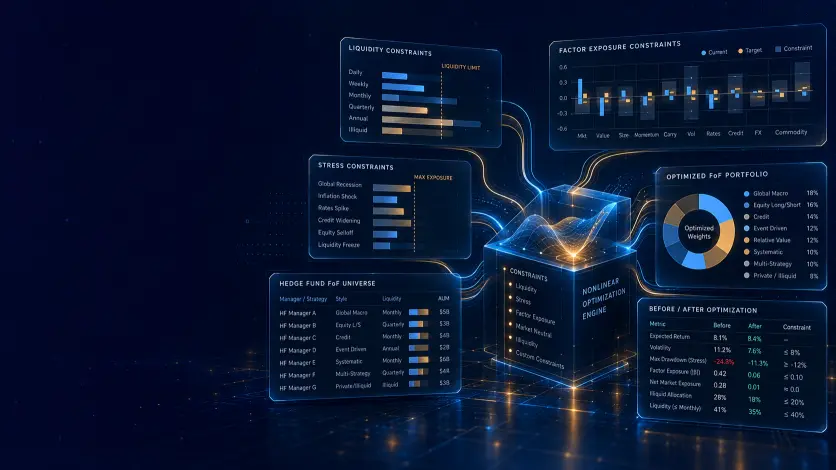
Alternative Investment Management Software
Institutional portfolio management, risk analytics and portfolio construction for alternative and multi-asset portfolios.
Integrated investment data, stress testing, portfolio optimization, alternative investment analytics and shadow accounting within one platform.
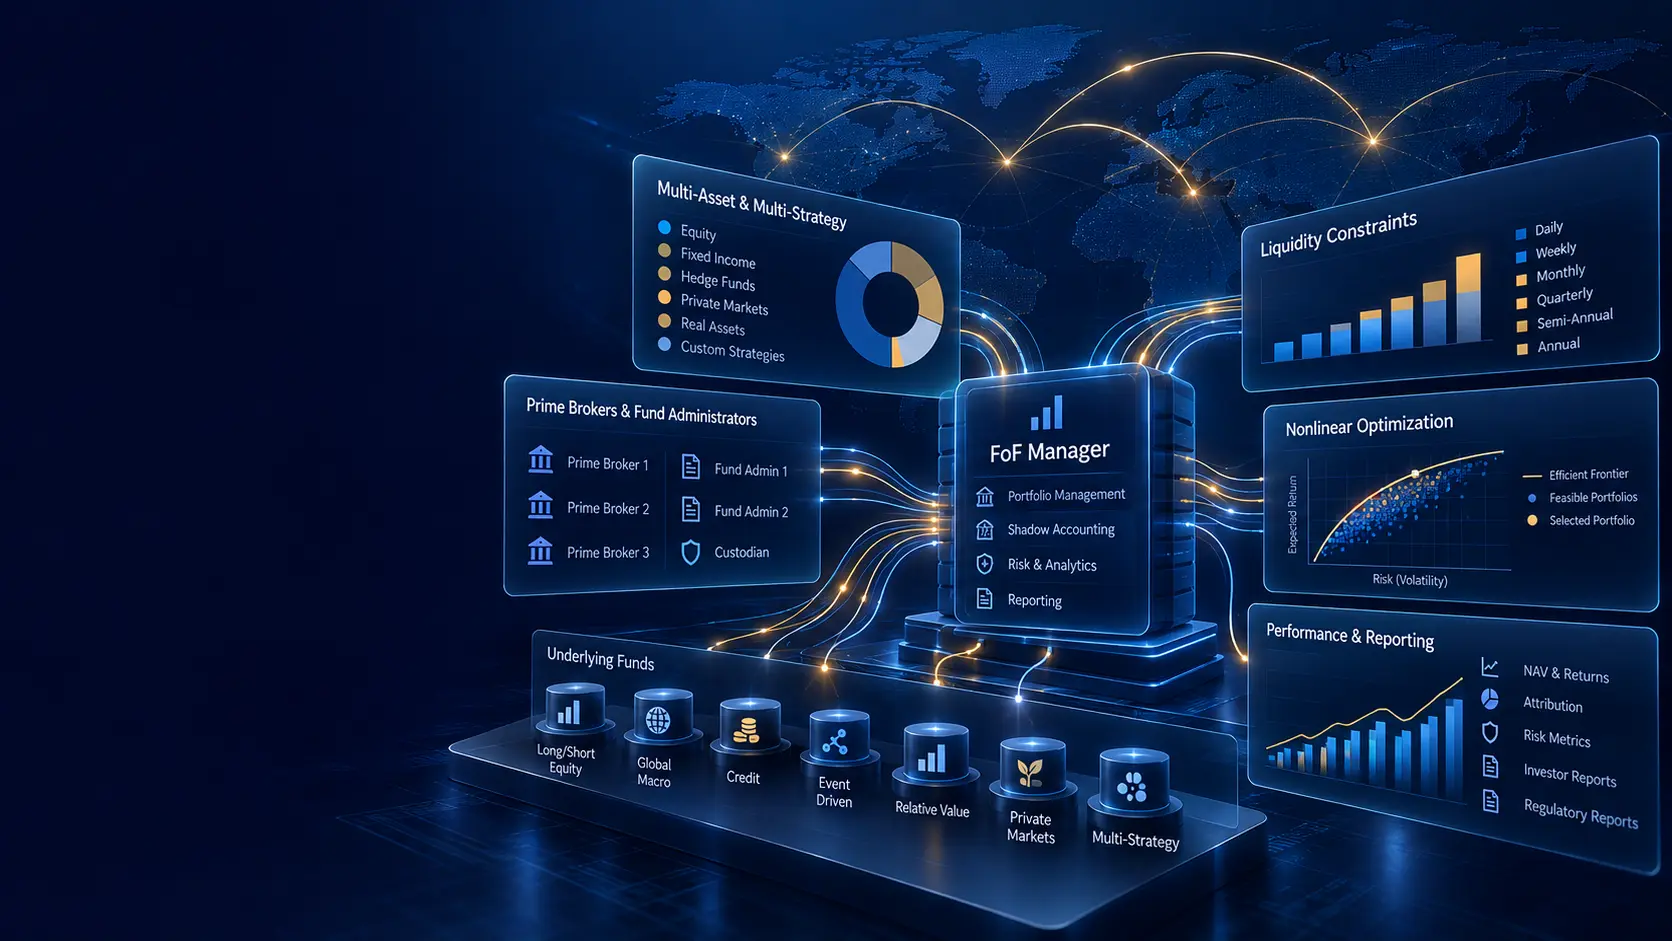
Shadow Accounting for Alternative Portfolios
Manage hedge funds, private equity and multi-asset portfolios with liquidity controls, custom classifications and flexible historical accounting.
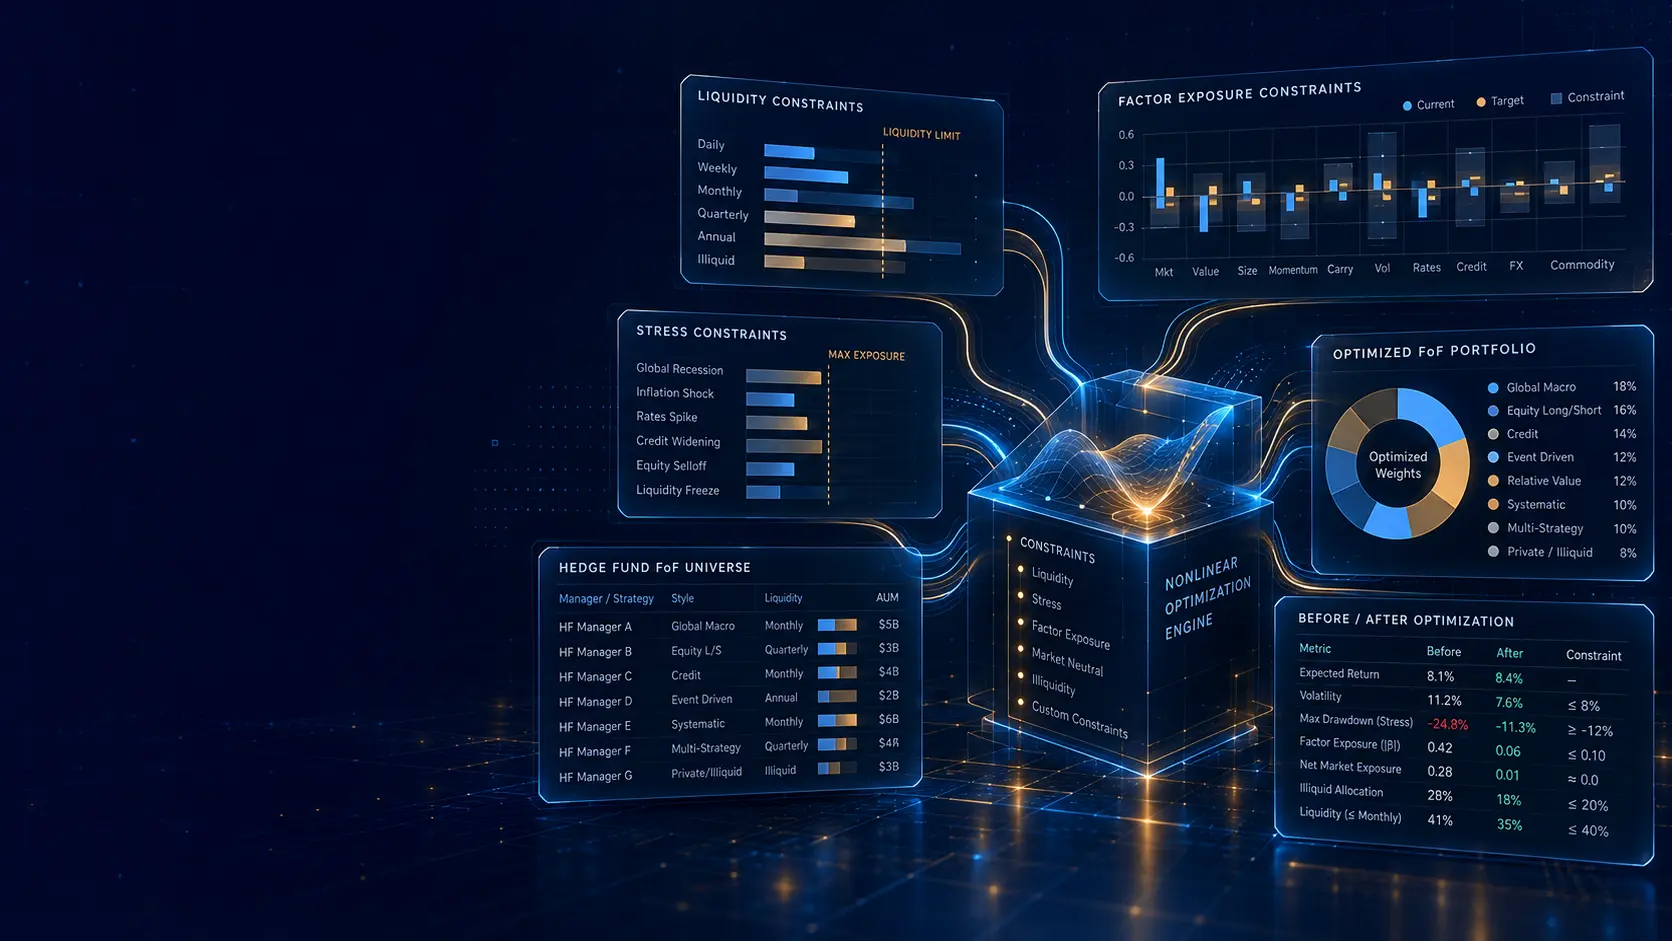
Nonlinear Portfolio Optimization
Construct hedge fund-of-funds and multi-asset portfolios with stress-test, factor-exposure, liquidity and other user-defined constraints.
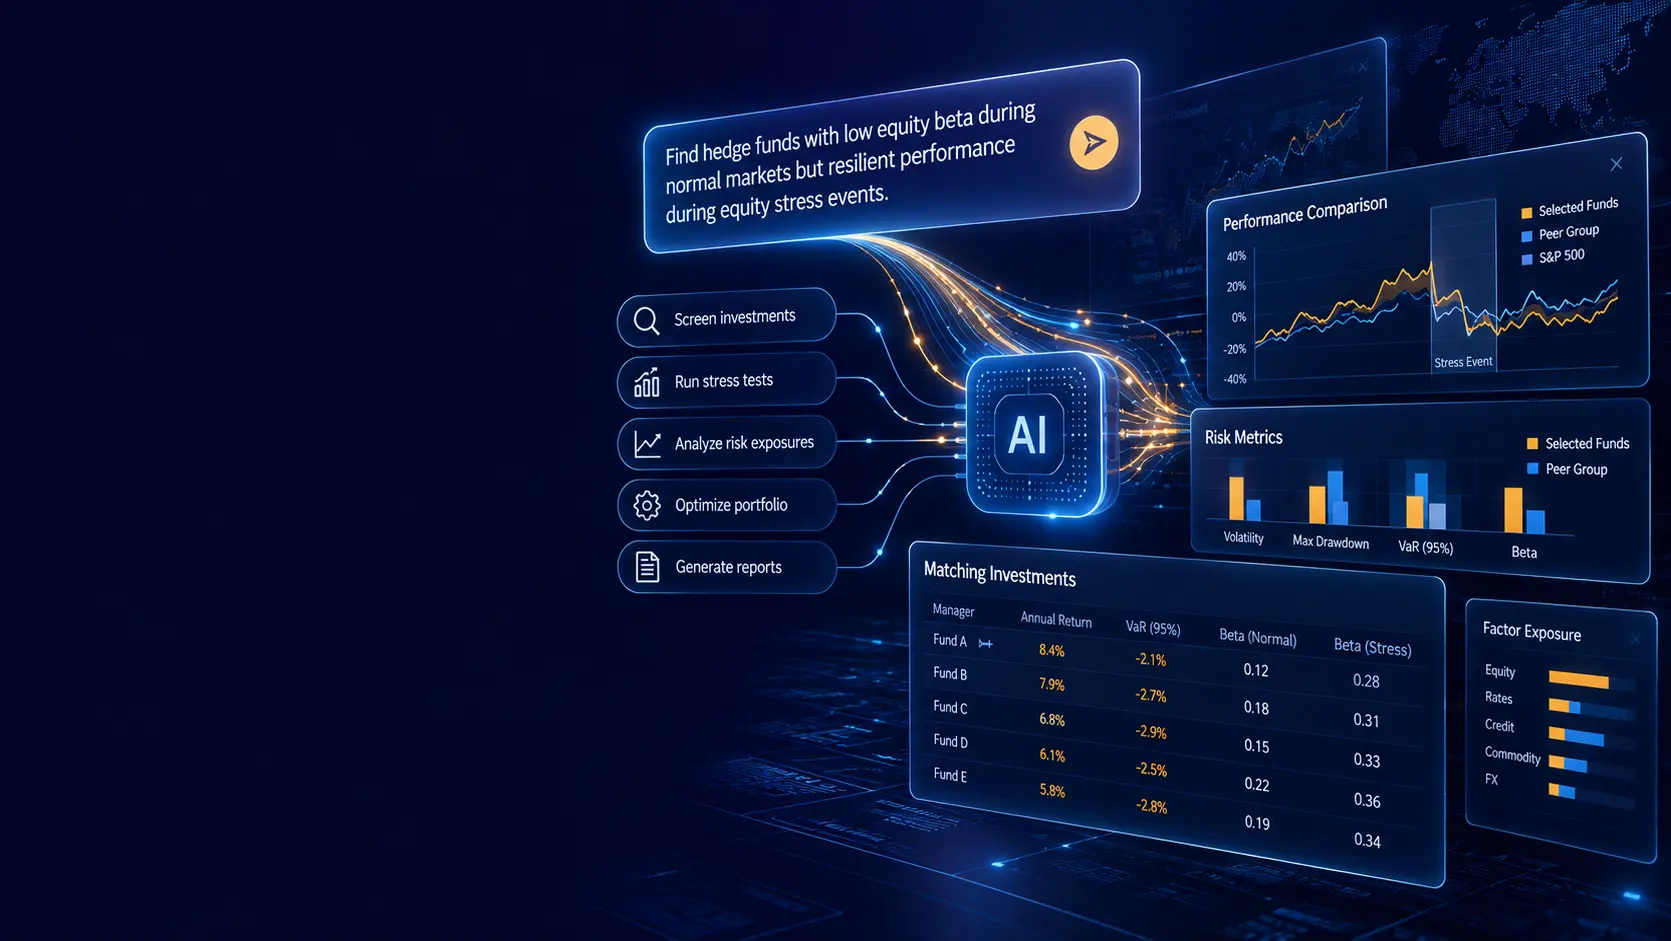
Natural-Language Access to Risk Shell
Use natural language to access investment research, risk analytics and portfolio workflows.
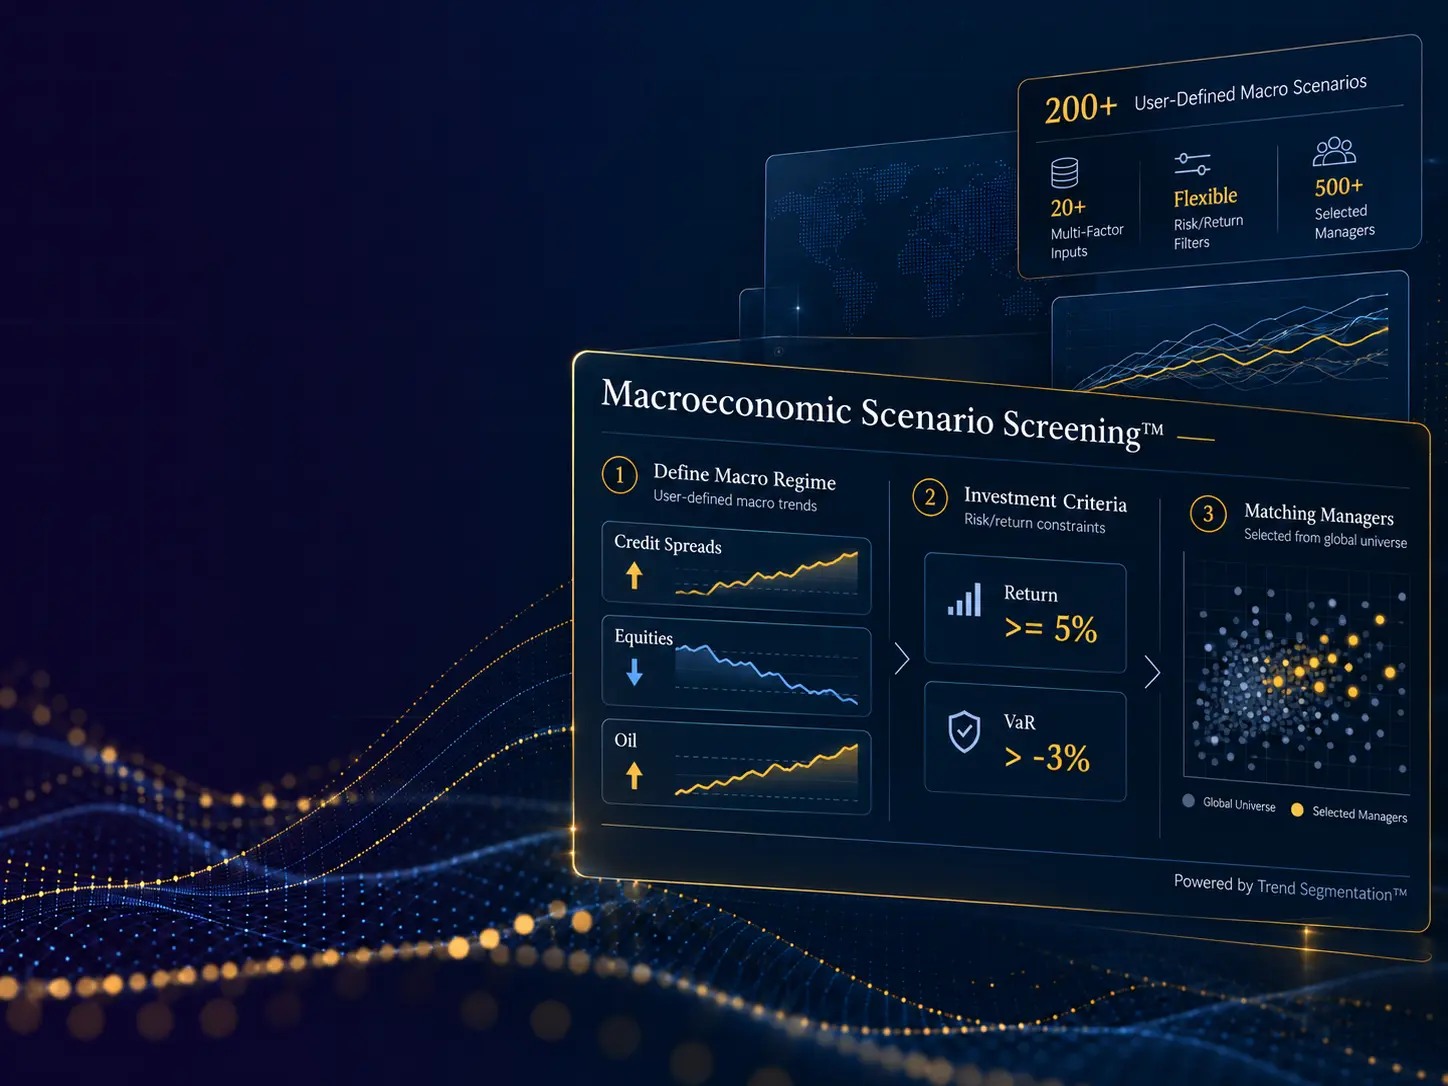
Select Assets for the Scenario You Define
Screen managers by risk and return targets under user-defined macroeconomic scenarios.
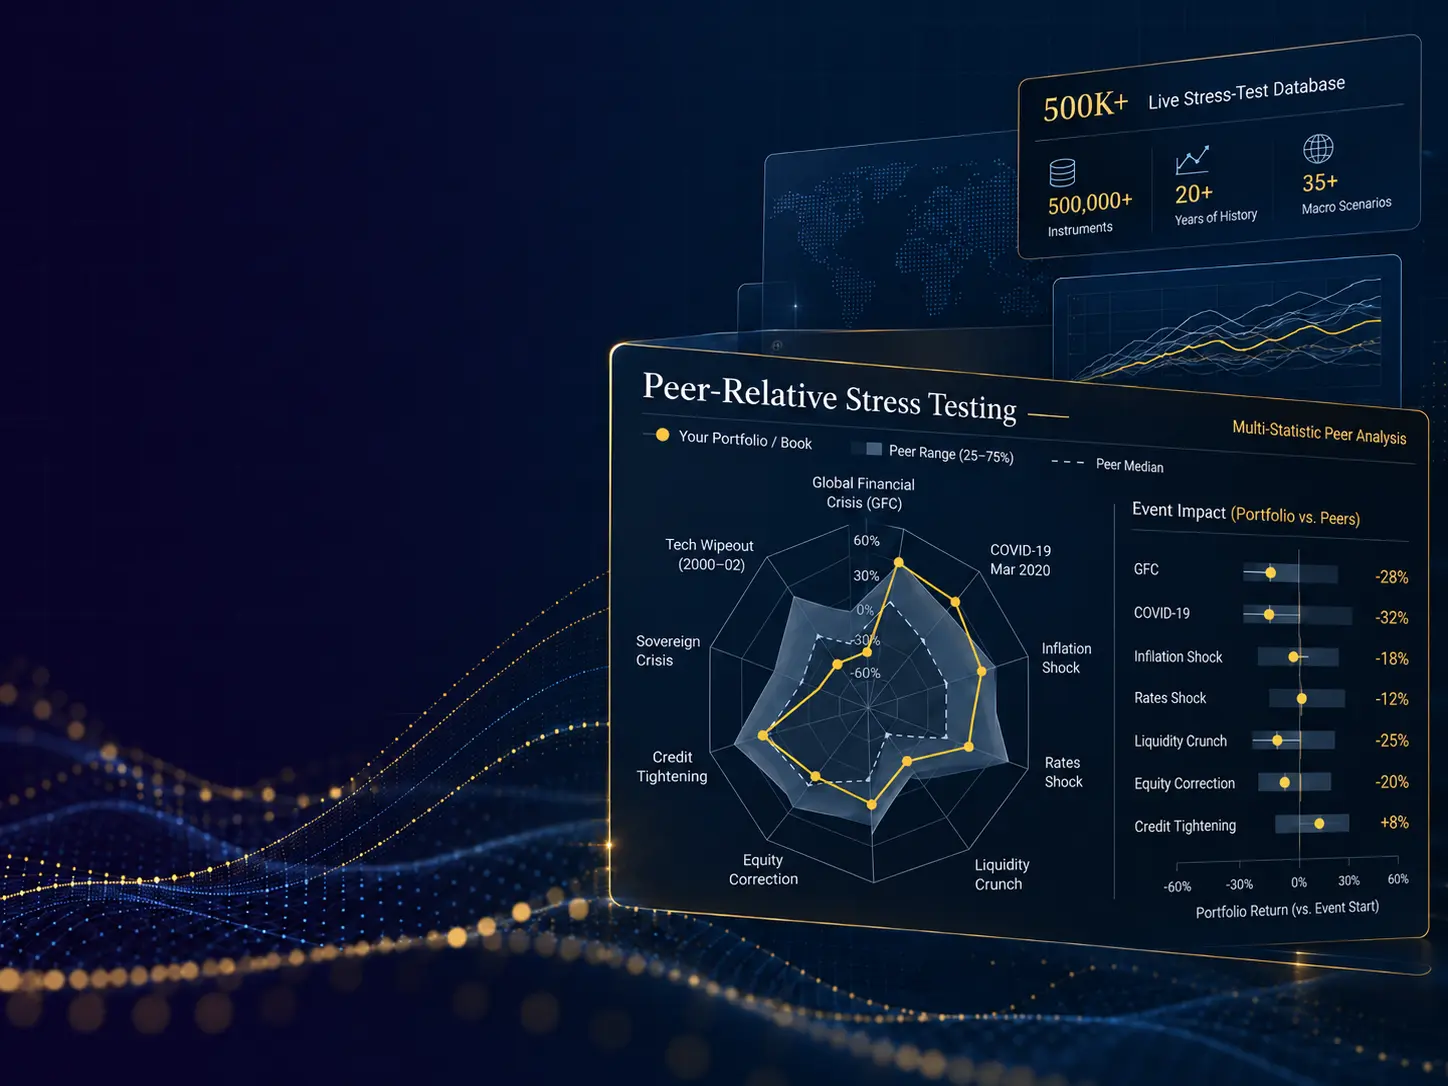
Peer-Relative Stress Testing
Compare extreme-event outcomes with a relevant peer group.